
GeneDx Holdings (WGS) Research And Mirum Deal Lead Focus, Is It A Bargain?
GeneDx Holdings (WGS) is back in focus after new research showed its exome and genome sequencing informed clinical management in over 60% of tested patients, alongside a new Mirum Pharmaceuticals partnership that offers no-cost rare disease testing.
GeneDx Holdings sits at US$52.37 per share after a mixed stretch, with a 1-day share price return of 0.96% but a year-to-date share price decline of 60.42% and a 1-year total shareholder return fall of 59.11%, even though the 3-year total shareholder return is very large at over 30x. Recent quarterly earnings showing ongoing losses, alongside refreshed full year guidance and the Mirum rare disease testing partnership, frame the latest research update as one more data point investors are weighing in light of that volatile track record and changing views on risk and growth potential.
Scan how GeneDx Holdings fits within the broader rare disease and genomics story by comparing it to a curated set of 36 healthcare AI stocks that are moving on similar healthcare AI themes.
GeneDx Holdings now trades at a steep discount to both analyst targets and some intrinsic value estimates, after a sharp pullback. Is that a bargain on misunderstood progress, or a fair warning about persistent losses and risk?
Most Popular Narrative: 44% Undervalued
On the analyst consensus Narrative on Simply Wall St, GeneDx Holdings screens as materially undervalued, with a fair value of $93.50 against a last close of $52.37, so the gap really comes down to whether the core growth levers actually deliver.
Growing payer reimbursement support, highlighted by commercial genome coverage moving from about 47% to approximately 87% of commercial lives and exome coverage of about 98%, leaves a wide gap to GeneDx’s 70% collection rate goal. This creates room for higher realized reimbursement and improved net margins if outpatient collection rates rise from current levels near 32%.
See why 25 investors see GeneDx Holdings as 44% undervalued.
Result: Fair Value of $93.50 (UNDERVALUED)
Still, the GeneDx Holdings story can shift quickly if payer cost controls tighten, or if outpatient collection rates remain stuck near current low levels.
Find out about the key risks to this GeneDx Holdings narrative.
Another View: GeneDx Holdings Through The P/S Lens
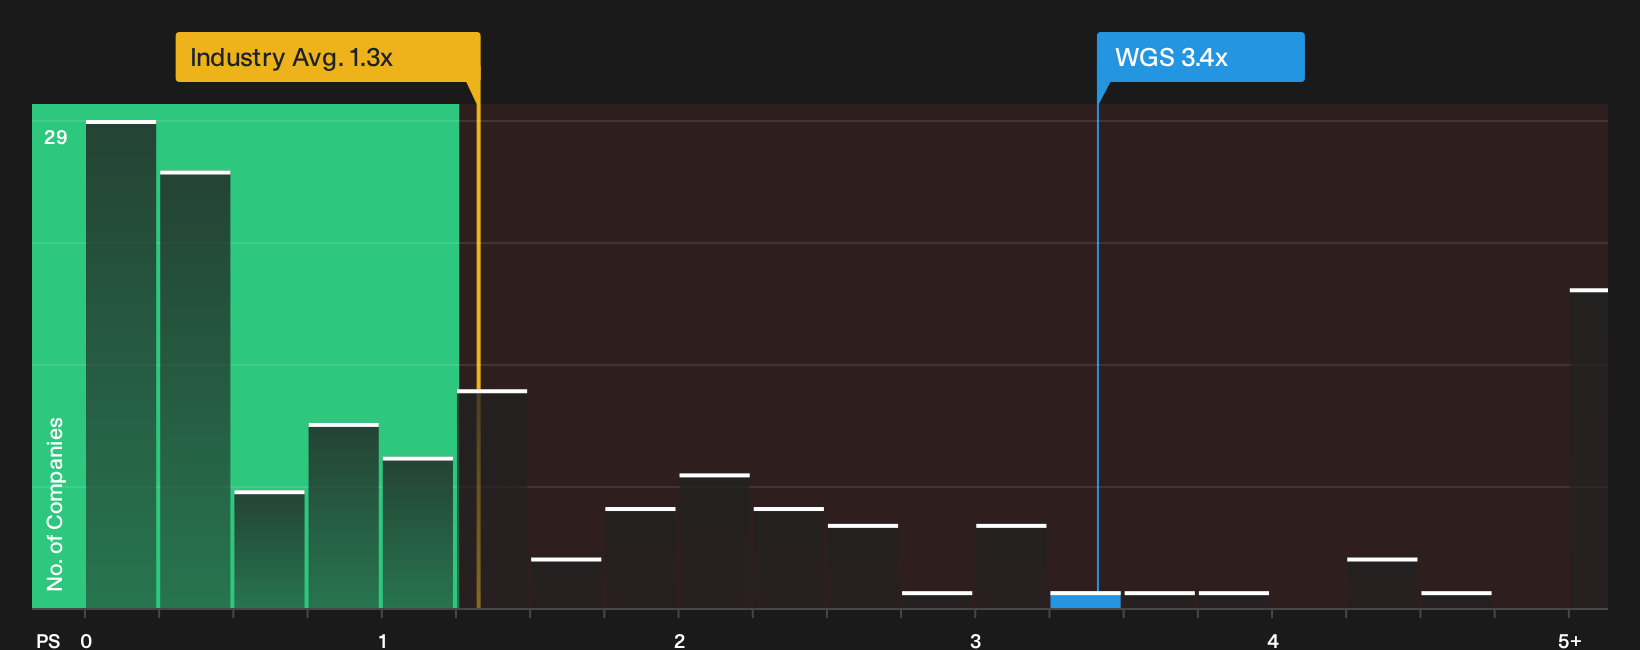
That 44% DCF style discount tells one story for GeneDx Holdings, yet the simple P/S ratio paints a very different picture. At about 3.4x sales, WGS trades at more than double the US Healthcare sector on 1.3x and well above peers on 0.8x, which points to meaningful valuation risk if sentiment cools.
For investors weighing that gap, the key question is whether GeneDx’s rare disease position and growth forecasts justify paying more than the wider industry for every dollar of revenue.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around GeneDx Holdings can pull you in both directions, so give yourself a short window to review the underlying numbers and sentiment before making a call. To see how the balance of concerns and potential upside stacks up in one place, walk through the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond GeneDx Holdings?
GeneDx Holdings gives you one angle on rare disease genomics, but you leave a lot on the table if you stop your research there.
- Target potential mispricing by scanning a focused pool of 34 high quality undervalued stocks that combine quality fundamentals with compressed expectations.
- Sharpen your income game by tracking 6 dividend fortresses that aim to pair strong cash generation with higher yielding payouts.
- Limit downside risk by reviewing a 29 resilient stocks with low risk scores that filters for resilient balance sheets and more stable trading profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com