
Did Dividend Guidance Rise Just Shift NYK Line's (TSE:9101) Investment Narrative?
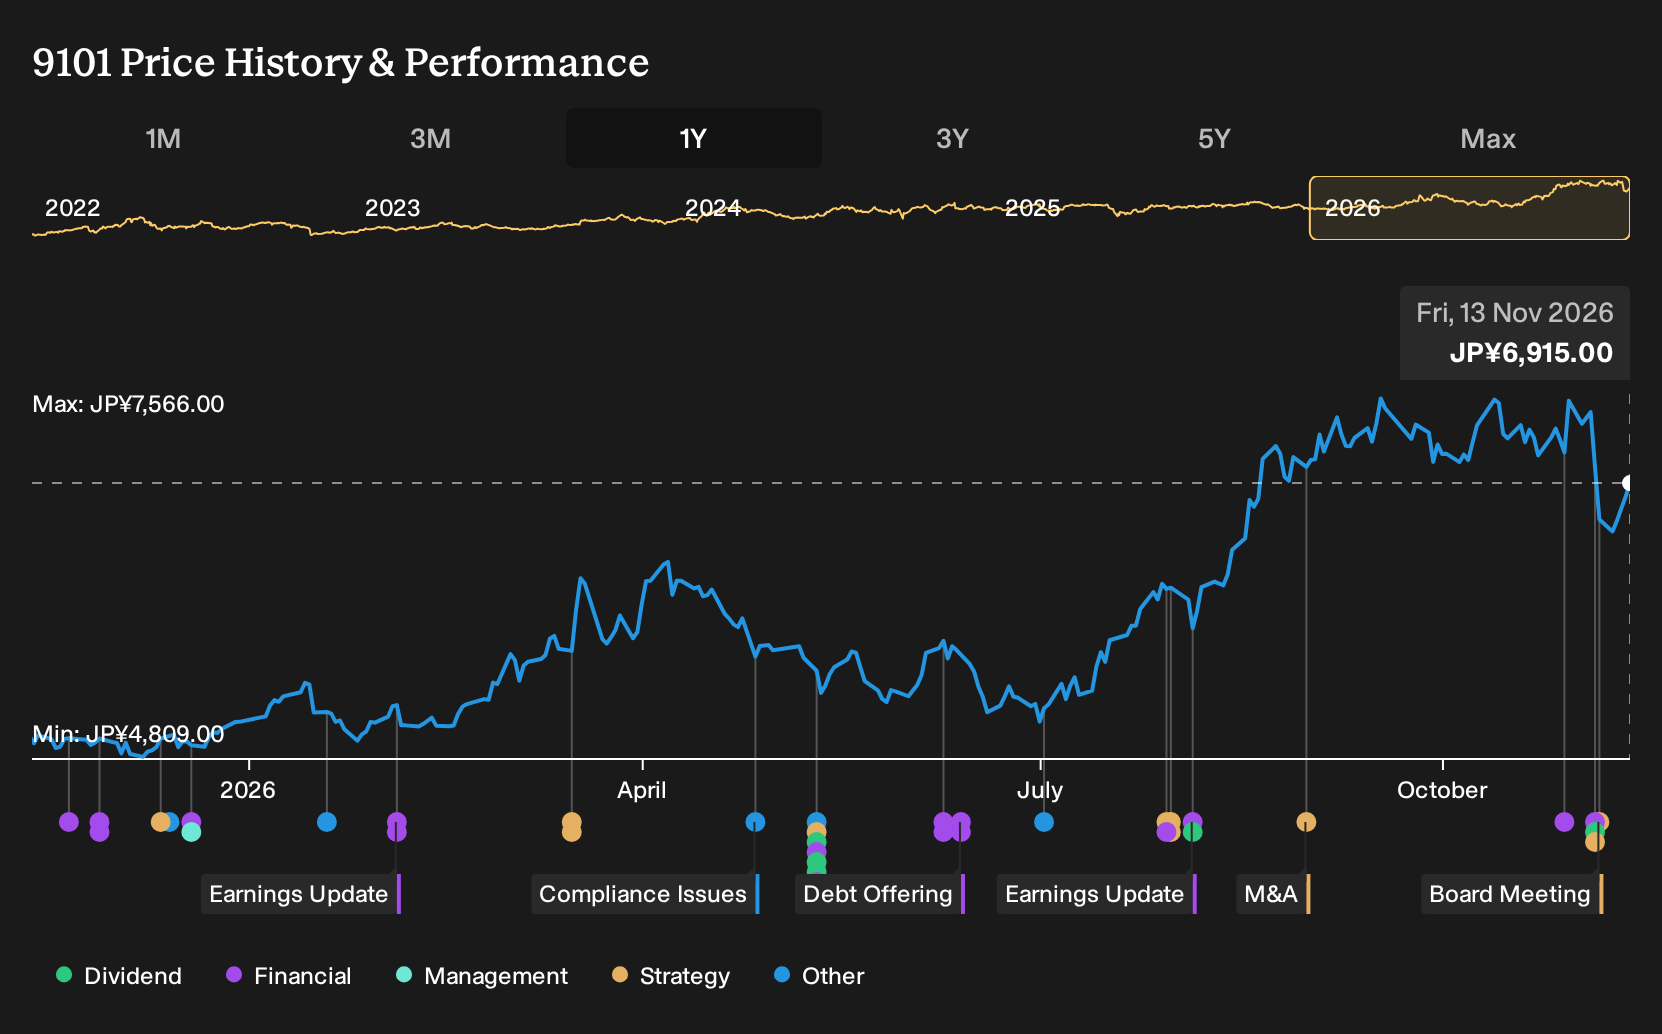
- Nippon Yusen Kabushiki Kaisha reported half year sales of JPY 1,505,025 million and net income of JPY 203,481 million, and raised both interim and full year dividends for the fiscal year ending March 31, 2027, citing its dividend policy and recent performance.
- The move to lift the interim dividend to JPY 165 per share and signal an annual JPY 330 payout places Nippon Yusen Kabushiki Kaisha’s cash return policy and earnings quality under sharper focus for income oriented investors.
- The next step is to observe how Nippon Yusen Kabushiki Kaisha’s stronger half year earnings and higher dividend guidance influence its broader investment narrative.
Compare Nippon Yusen Kabushiki Kaisha's latest dividend move with other income focused opportunities by scanning our hand picked 29 dividend fortresses now woven around resilient cash return profiles.
Nippon Yusen Kabushiki Kaisha Investment Narrative Recap
To own Nippon Yusen Kabushiki Kaisha, you need to believe the shipping cycle, fuel costs and route disruptions can be managed through contract mix, surcharges and scale. The analyst consensus narrative on Simply Wall St focuses on execution of the enlarged midterm investment plan and integrations such as Walden to support more stable earnings despite forecast pressure on profit.
The latest half year results show higher sales and net income alongside a larger interim dividend, which keeps near term attention on cash generation and capital discipline. Key near term risk still sits around voyage costs, congestion and fuel prices, so the core catalyst remains execution on cost control and integration rather than this single dividend step.
The revised dividend guidance to ¥165 per share at both interim and year end for the fiscal year ending March 31, 2027 is the announcement most tied to the current discussion. It directly links to the stated 40% payout ratio policy and a minimum ¥200 annual dividend floor, which investors can compare with earnings volatility and one off items.
For you as a shareholder, the higher dividend runs alongside catalysts such as the planned NS United Kaiun Kaisha acquisition and LNG carrier investment plan, while risks include pressured Automotive and Logistics margins and earnings forecasts that are expected to decline over the next 3 years. Execution on these projects and cost management will likely matter more than any one dividend reset for the medium term story.
Nippon Yusen Kabushiki Kaisha’s current earnings are ¥228.6 billion. Analyst assumptions point to revenue growth of 6.9% a year and consensus earnings of ¥256.5 billion by 2029. This implies an earnings increase of about ¥27.9 billion on revenues forecast to reach ¥3,113.7 billion in that same year.
Uncover why Nippon Yusen Kabushiki Kaisha's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
You may see Nippon Yusen Kabushiki Kaisha’s dividend hike and board focus on the tender offer as a clear win, yet the most cautious analysts were already framing heavy capex and higher debt as the key swing factor. Their October view pencilled in revenue of ¥2,867.0b and earnings slipping toward ¥198.6b by 2029. Those projections came before this dividend reset and governance news, so it is worth checking several viewpoints to see how opinions might shift from here.
Explore another Nippon Yusen Kabushiki Kaisha fair value estimate, including one that suggests as much as 22% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research and using your own judgment.
- A great starting point for your Nippon Yusen Kabushiki Kaisha research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Nippon Yusen Kabushiki Kaisha. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nippon Yusen Kabushiki Kaisha's overall financial health at a glance.
Looking for more investment ideas beyond Nippon Yusen Kabushiki Kaisha?
If Nippon Yusen Kabushiki Kaisha is only one piece of your income and total return puzzle, use the Simply Wall St Screener to line up other candidates and compare them on the same footing.
- For investors who want potential income without ignoring quality, scan a 29 dividend fortresses that focus on payout strength and balance sheet resilience.
- If downside risk control sits higher on your checklist, filter for 19 resilient stocks with low risk scores that pair steadier fundamentals with more measured volatility profiles.
- When you want ideas that the broader market may have overlooked, sort through 72 high quality undiscovered gems and see which companies match your own thesis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com