
Vodafone (LSE:VOD) Stock Looks Below Fair Value On Sales
Vodafone Group has delivered a strong run over the past few years, even as the telecom group works through a large reported loss and a major reshaping of its operations. After that kind of performance, the live question is whether the current share price is adequately supported by the sales Vodafone is generating today.
- Vodafone Group has returned 89.5% over 3 years. This puts real pressure on the numbers to show that revenue can carry this higher market value.
- The recent €3.6b loss came alongside 11% revenue growth and a higher dividend, which can change how investors think about the durability and profitability of Vodafone's sales base.
- The analysts covering Vodafone Group have run their own numbers. See what analysts think Vodafone Group's shares could be worth.
The issue now is whether Vodafone Group's current share price is justified by its sales when set against the Fair Ratio benchmark.
If you are weighing Vodafone Group against other sales focused opportunities, it can help to compare its current setup with companies in the 13 high quality undervalued stocks.
Is Vodafone Group a Bargain on Sales?
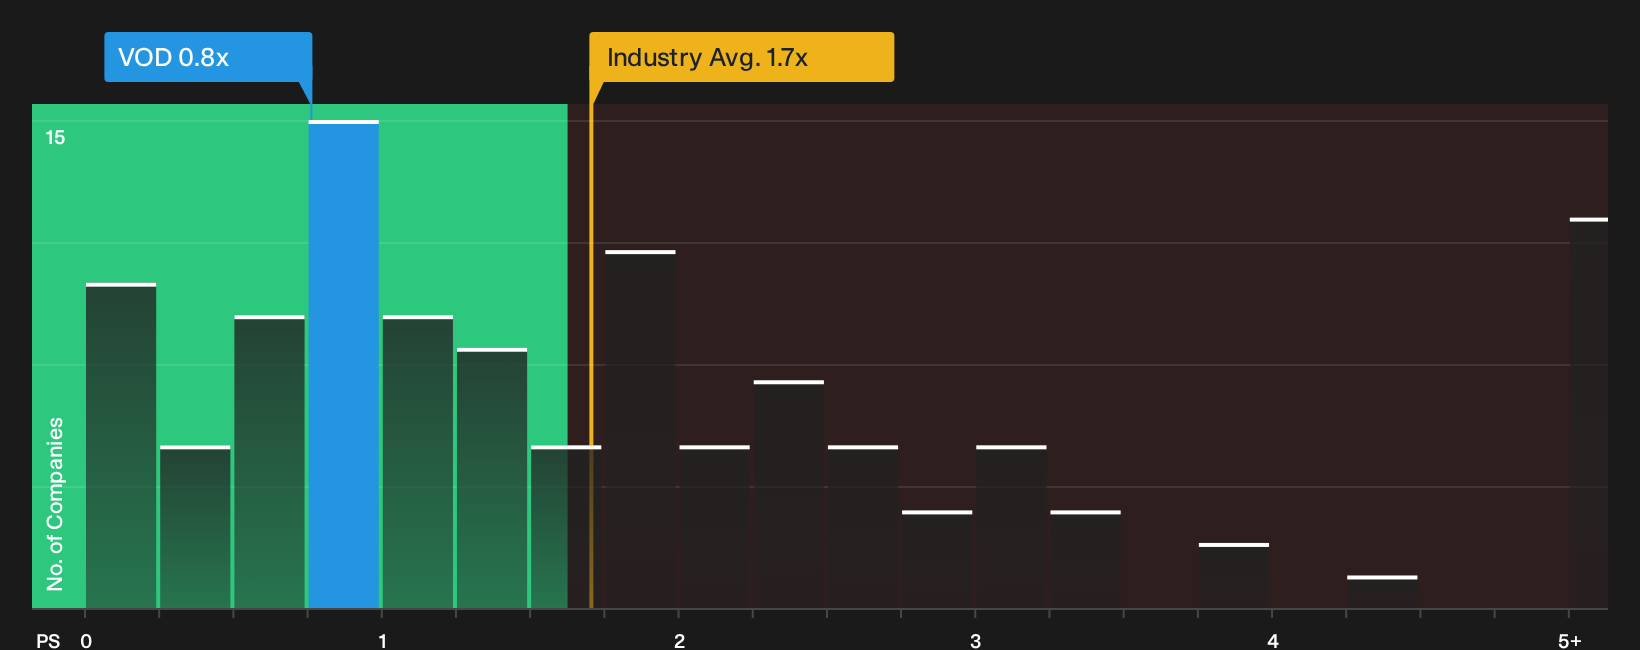
The P/S ratio fits Vodafone Group because investors often look at sales when earnings swing around large one off items. On this metric, the stock trades on a P/S of 0.8x, which is far below the Wireless Telecom industry average of 1.7x and also below the peer group on 2.3x. That gap means the market values each euro of Vodafone Group revenue at a clear discount to much of the sector.
Despite the recent €3.6b reported loss and upgraded guidance, the current P/S sits under the level suggested by a Fair Ratio that blends Vodafone Group’s growth profile, profitability, scale and risks. For anyone focused on top line based valuation, the shares currently price the telecom group’s revenue stream cautiously relative to both the modelled benchmark and typical sector pricing. Explore the numbers behind Vodafone Group's P/S valuation.
The Vodafone Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that P/S puzzle for Vodafone Group leaves off and spell out which future paths on growth, margins and earnings would need to play out for the stock to be worth materially more or less than today's price. Each scenario anchors a fair value estimate to a clear storyline about Vodafone Group's potential catalysts and key risks, so you can track over time which version of events appears to be unfolding.
The two Vodafone Group Narratives line up on the same facts but differ on how much slack is left in the story if things go wrong.
Bull case: roughly fairly valued
This view comes from the analyst consensus Narrative on Simply Wall St, which pulls together Street targets and forecasts into a single storyline.
"The integration of VodafoneThree in the U.K., with increased annual cost and CapEx synergy ambitions of £800 million by FY2030 and a path to £1b by FY2032, is expected to improve net margins and free cash flow…"
Discover why this Narrative puts Vodafone Group at roughly fairly valued.
Bear case: 23% overvalued
This angle is set out in the bearish analyst Narrative on Simply Wall St, which leans on the most cautious forecasts and price targets.
"Although Vodafone Group points to continued good growth in adjusted EBITDAaL and free cash flow and has set an ambition for double digit free cash flow growth, the expectation that Germany's EBITDA will decline again in FY 27 due to TV and mobile pricing headwinds introduces a risk that group earnings fall short of these goals if the largest European market does not stabilise as assumed…"
Explore why this Narrative puts Vodafone Group at 23% overvalued.
One more piece of the Vodafone Group story to check before you move on
Valuation only tells part of the Vodafone Group picture, and Simply Wall St's checks have flagged specific risk signals that deserve a look before you lean on any price metric too heavily. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com