
What Lamar Advertising Stock's Updated Earnings Guidance Means For Shareholders
- Lamar Advertising reported third quarter 2026 results with sales of US$624.47 million and net income of US$161.87 million, and updated full year 2026 guidance to diluted EPS of US$6.01 to US$6.04 and net income of US$611.03 million to US$614.03 million.
- The mix of higher third quarter sales and a full year earnings outlook in a tight range gives investors fresh data on how Lamar Advertising is converting its billboard footprint and cost base into profit in 2026.
- We will look at how Lamar Advertising's investment narrative is affected by its tighter 2026 earnings guidance after the latest quarterly update.
Lamar Advertising Investment Narrative Recap
To own Lamar Advertising, you need to believe the out of home ad network can keep filling its boards while holding on to high profitability. The tighter 2026 EPS and net income guidance range signals management has reasonably clear visibility on the near term run rate. That can support the analyst consensus Narrative on Simply Wall St, which leans on steady earnings and cash generation.
The key short term catalyst remains how effectively Lamar Advertising turns its growing digital and programmatic footprint into EBITDA and AFFO, without expense growth eating into margins. The biggest risk is cost creep from revenue sharing leases, commissions and higher debt costs. This latest guidance tweak does not materially change that risk reward balance.
The updated 2026 outlook, with diluted EPS guided to US$6.01 to US$6.04 and net income to US$611.03m to US$614.03m, is the most relevant development for that thesis. It ties directly to the margin story that analysts track, especially after a record 49.2% EBITDA margin in Q2 2026 and management’s long term margin targets.
For you as a shareholder, the question is how that guidance interacts with the catalysts around digital, programmatic and acquisitions. If Lamar Advertising keeps growing digital boards and programmatic revenue while staying within this earnings range, it shows the playbook remains intact. If costs linked to leases, commissions or funding rise faster, the guidance band could become harder to defend.
Lamar Advertising's narrative projects US$2.6b revenue and US$764.4m earnings by 2029. This assumes 4.4% yearly revenue growth and an earnings increase of about US$208.7m from current earnings of US$555.7m.
Uncover why Lamar Advertising's fair value suggests Lamar Advertising is aligned with its current price.
Exploring Other Perspectives
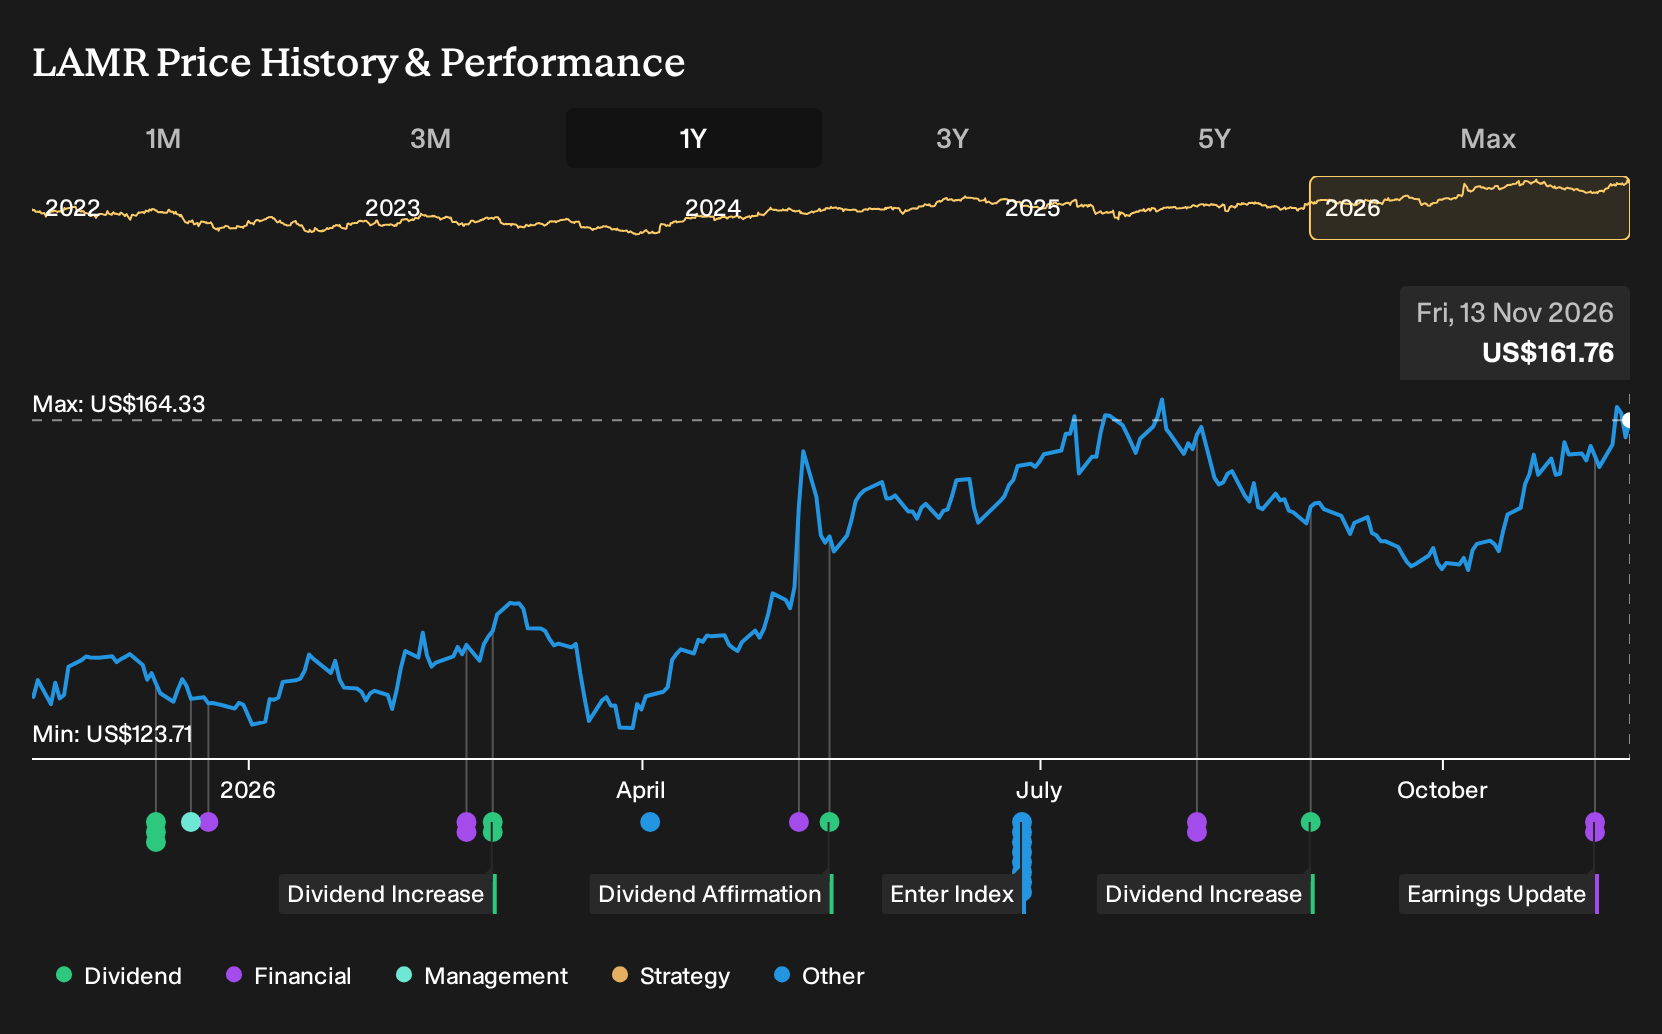
Two fair value estimates from the Simply Wall St Community span roughly US$162 to US$248 per share, so you are seeing retail investors bracket Lamar Advertising with both conservative and optimistic views. Those opinions sit beside catalysts around digital billboards and programmatic revenue that could reshape how future earnings power is judged. Consider exploring several of these viewpoints before leaning on any single one.
Explore another Lamar Advertising fair value estimate, including one that suggests as much as 54% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgement.
- A great starting point for your Lamar Advertising research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Lamar Advertising. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lamar Advertising's overall financial health at a glance.
Looking for more ideas beyond Lamar Advertising?
If Lamar Advertising sits on your watchlist, it can help to compare its story with other businesses that share traits you care about, such as valuation, balance sheet strength or risk profile. The Simply Wall St Screener is a quick way to surface a wider set of candidates that match those preferences.
- For investors focused on quality at a reasonable price, scan a curated set of 34 high quality undervalued stocks that combine fundamentals with valuations that may appeal to you.
- If resilience matters more than excitement, filter for 29 resilient stocks with low risk scores and see which businesses line up with your tolerance for volatility and financial risk.
- When balance sheet strength is a priority, sort through a list of solid balance sheet and fundamentals (24 results) and compare how their financial footing stacks up against Lamar Advertising.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com