
How Investors May Respond To Aviva (LSE:AV.) Premium Growth From Direct Line
- Aviva reported a 19% rise in general insurance premiums to £11.8b for the first nine months of 2026, with UK and Ireland volumes supported by the Direct Line acquisition, new partnerships and strong wealth net inflows.
- The update paired higher premiums with a Solvency II cover ratio of 179% and reiterated earnings targets, highlighting how acquisition synergies and capital strength are shaping Aviva's business mix toward capital light operations.
- We will explore how Aviva's investment narrative is affected by strong general insurance premium growth supported by the Direct Line acquisition.
Scan how Aviva’s premium momentum compares with other insurers by reviewing a curated set of 5 resilient stocks with low risk scores that pair balance sheet resilience with disciplined underwriting.
Aviva Investment Narrative Recap
To own Aviva you need to be comfortable with a story built around steady insurance operations, a growing wealth arm and a tilt toward capital light activities. The latest update, with 19% general insurance premium growth to £11.8b and 31% higher wealth net inflows, supports that business mix rather than changing it. The short term catalyst remains execution on Direct Line integration and cost savings.
The biggest near term risk still sits in integration and pricing pressure. UK and Canadian personal lines remain exposed to softer rates and claims inflation, which could keep underwriting margins under pressure. The reiterated earnings targets and 179% Solvency II cover ratio suggest the trading update does not materially change that risk reward balance.
The analyst consensus Narrative on Simply Wall St leans heavily on Aviva’s push into capital light earnings, digital efficiency and workplace wealth flows. Against that backdrop, the reaffirmed expectation for operating earnings per share growth broadly in line with the 11% target and the 2026 guidance confirmation become the key operational signal from this trading update.
For you this means the catalyst path the Narrative describes, from workplace pension inflows to higher fee income and a richer mix of lower capital businesses, still hinges on Aviva hitting its medium term profit and cash targets while absorbing Direct Line cleanly. Any stumble on integration benefits, or sustained pressure on UK and Canadian personal lines pricing, would test how realistic those projected earnings improvements really are.
Aviva's narrative projects £29.8b revenue and £2.1b earnings by 2029. That profile is built on analyst assumptions for revenue to decline by 1.0% per year and for earnings to rise by about £1.5b from £559.0m today.
Uncover why Aviva's fair value indicates that it is in line with its current price.
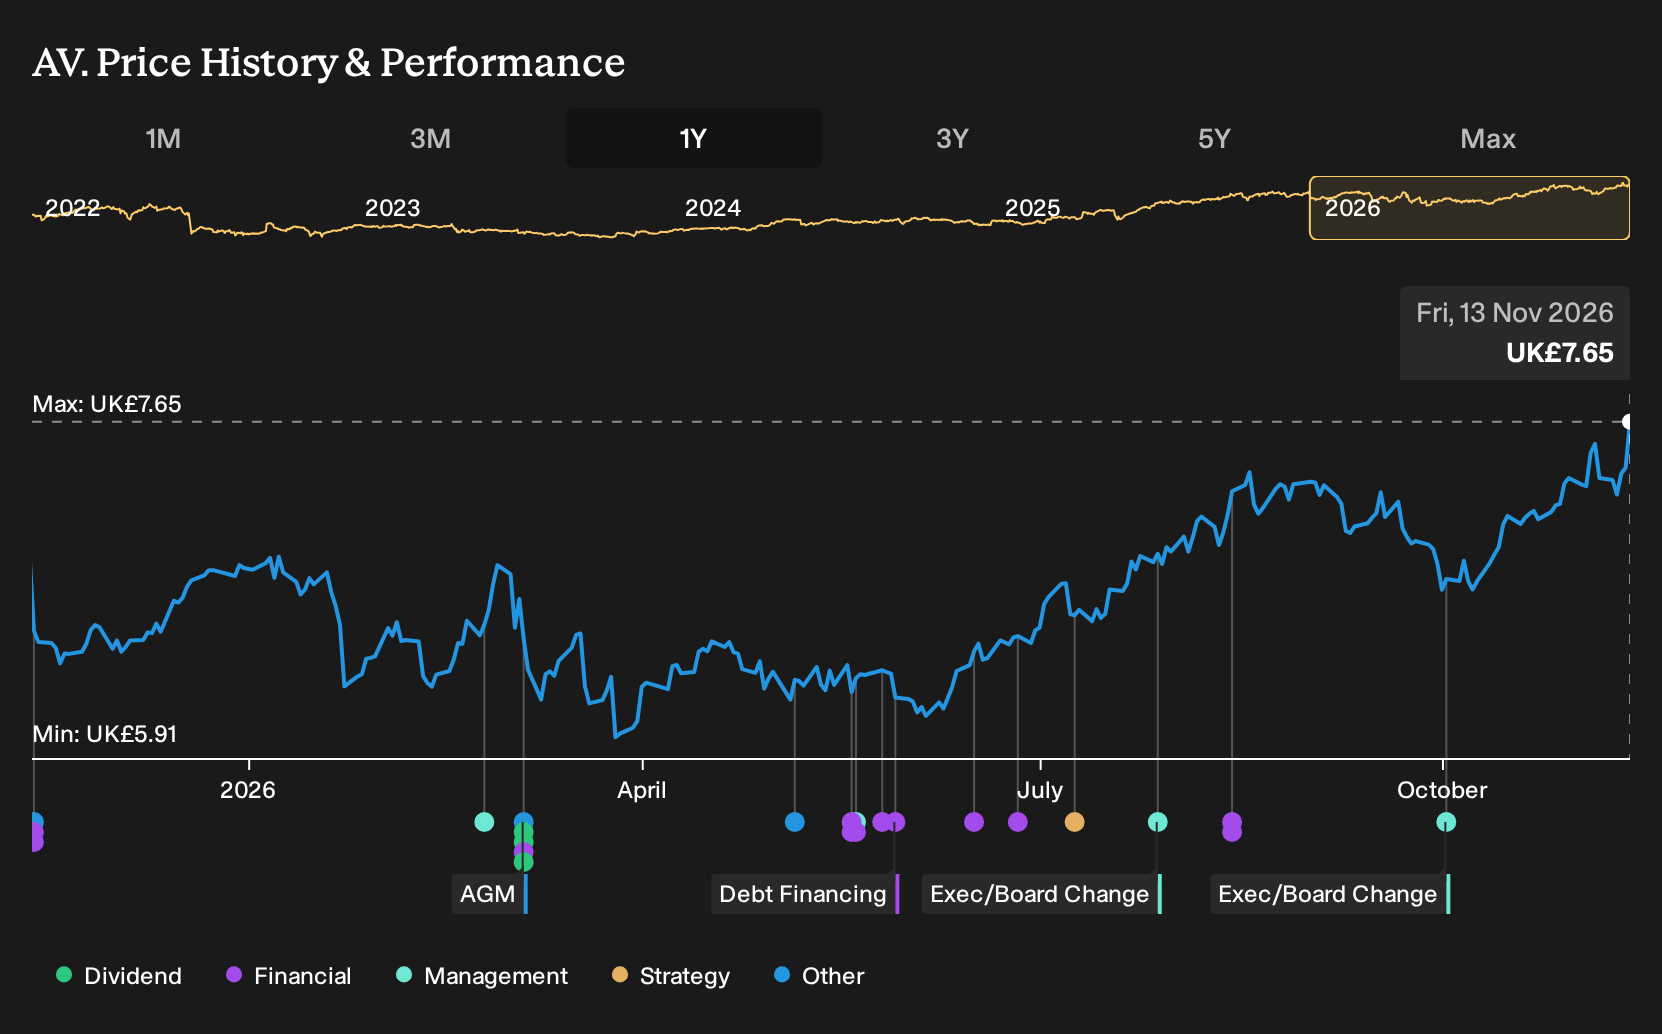
Exploring Other Perspectives
Six fair value estimates from the Simply Wall St Community cluster between £7.48 and £12.54 per share, so some retail investors see Aviva as tightly priced while others pencil in much richer potential. You can weigh those conflicting views against risks around Direct Line integration and UK pricing, and judge which narrative feels more convincing.
Explore 5 other Aviva fair value estimates, including one that suggests potential upside of as much as 64% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own analysis.
- A great starting point for your Aviva research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aviva. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aviva's overall financial health at a glance.
Looking for more investment ideas beyond Aviva?
If Aviva's story has sharpened your thinking about risk, income and growth, the next step is to widen your watchlist with other companies that fit clear financial themes.
- For potential mispriced opportunities with solid fundamentals, scan a hand picked set of 13 high quality undervalued stocks that combine quality metrics with attractive valuations.
- If income is your priority, focus on companies that aim to support sizeable payouts by reviewing 4 dividend fortresses built around higher yield profiles.
- For peace of mind around resilience, concentrate on financially robust businesses through a list of solid balance sheet and fundamentals (9 results) that keeps debt and liquidity front of mind.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com