
Dropbox (DBX) Stock Could Be 47% Undervalued Following $1.1B Notes Deal
Dropbox has delivered a 34.0% gain over the past five years, and the stock now trades against a backdrop of fresh capital markets activity and expanding AI ambitions. With that kind of long run on the share chart and a growing focus on cash generation, the live question is whether today's price is adequately supported by the cash flows the business can produce.
- Over 5 years the stock is up 34.0%, which puts real weight on whether that longer term climb is aligned with the cash the company can ultimately return to shareholders.
- The upsized US$1.1b convertible notes deal and planned debt repayment, buybacks and hedge transactions may reshape Dropbox's future financing costs, dilution profile and the timing of cash available for investors.
- If you'd rather focus on earnings, this one's for you. See what Dropbox's 16.6x P/E says about the price.
The issue now is whether the current Dropbox share price can be justified by the cash flows implied by its intrinsic value under a Discounted Cash Flow (DCF) view.
If you are weighing Dropbox against other opportunities where the focus is squarely on valuation, it can help to compare it directly with 34 high quality undervalued stocks.
Is Dropbox a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) approach here looks at the cash Dropbox can return to shareholders over time and then discounts it back to today. Dropbox generated about $914.4 million of free cash flow over the last twelve months, and the model assumes that annual free cash flow stays in the $900 million to a little over $1b range through the next decade rather than swinging sharply higher or lower.
On that cash profile, the DCF output suggests an intrinsic value that sits substantially above the current share price of $33.53. The recent upsized $1.1b convertible notes deal, with plans to pay down term debt and fund buybacks, fits with a story in which the market is weighing dilution and capital structure risk even as the cash flow projections support a higher worth for the equity. That gap is where the detailed valuation summary becomes useful for investors weighing Dropbox against alternatives. Find out what Dropbox could be worth using our Discounted Cash Flow (DCF) estimate.
The Dropbox Narrative: What Would Justify Today's Price?
Dropbox Narratives on Simply Wall St pick up where the DCF puzzle leaves off and explain which future paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price on the Community page. Each one treats fair value as a thesis about Dropbox's business that can be tracked over time, rather than a one off snapshot, so you can see how the story holds up as new information arrives.
Dropbox now splits opinion between those who see AI driven upside and those who think that promise is already baked into the share price.
Bull case: 30% undervalued
The bullish analyst Narrative on Simply Wall St argues that Dropbox's AI rollout can reshape how its user base is monetised.
"Embedding Dash intelligence directly into the main Dropbox experience and expanding access to Teams customers, where more than 30% of weekly engaged users and over 50% of monthly engaged users are already using Dash features, creates scope for higher attach rates to paid AI workflows that can support recurring revenue growth..."
Discover why this Narrative puts Dropbox at 30% undervalued.
Bear case: 29% overvalued
The bearish analyst Narrative on Simply Wall St focuses on whether AI usage, security tools and user growth justify the current valuation.
"The numbers imply the share price already reflects a successful AI pivot and continued strong free cash flow generation, even as some recent research argues that growth in the core file, sync and share business and AI driven upside remain unproven at current valuation levels..."
Explore why this Narrative puts Dropbox at 29% overvalued.
One more Dropbox angle worth checking before you move on
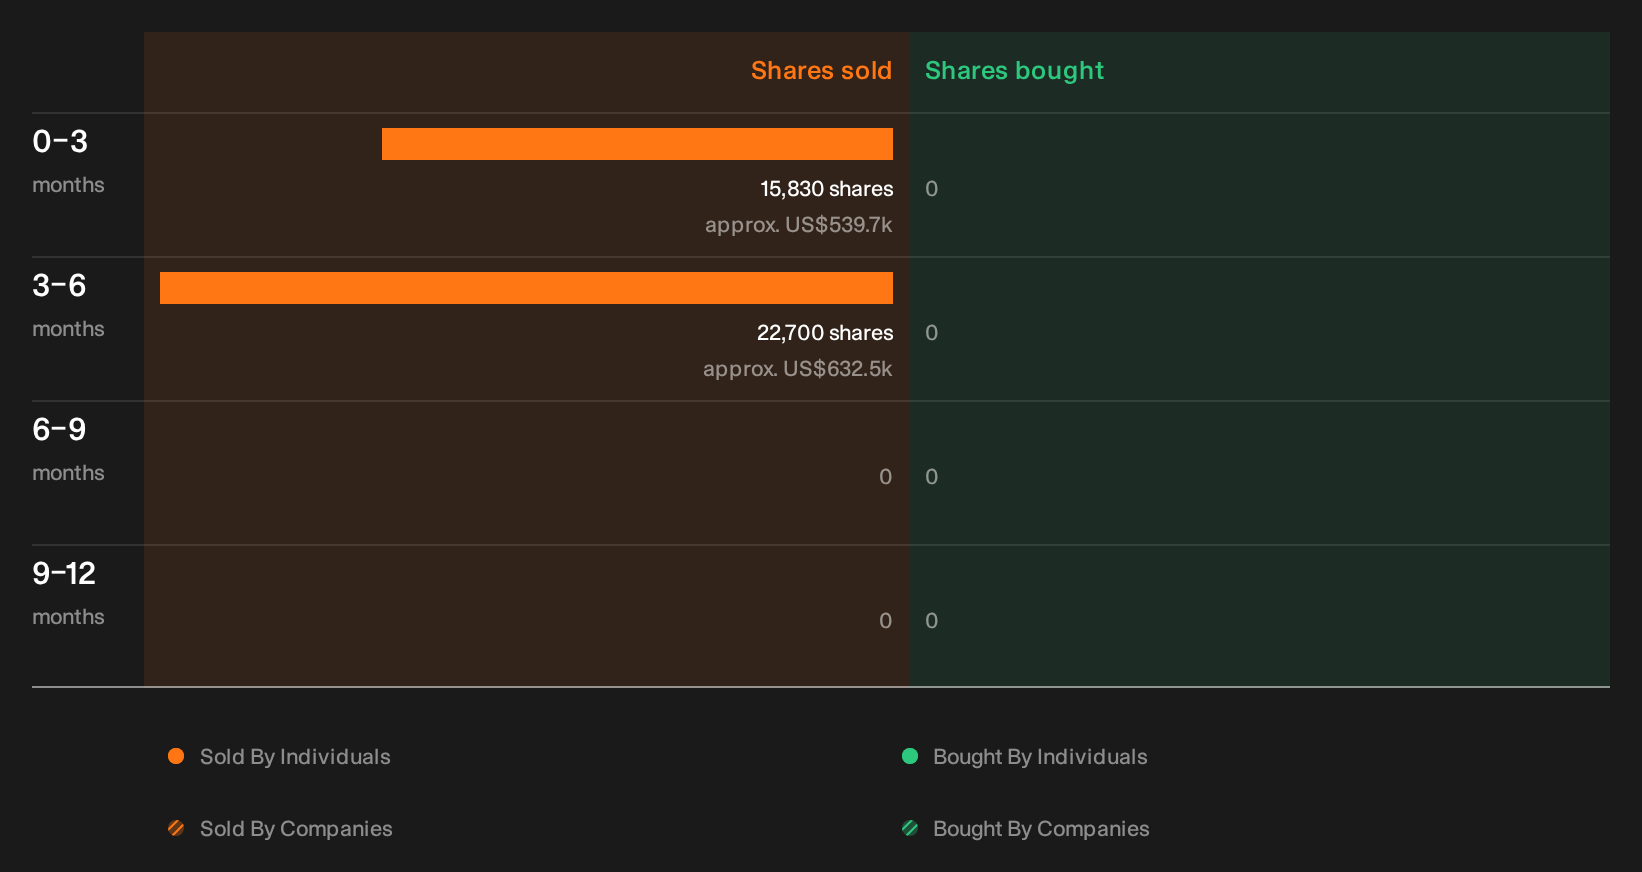
Valuation, growth narratives and capital structure only tell part of the Dropbox story. Recent management share activity has raised fresh questions that you can only answer by seeing who sold what and when. See the recent insider selling flagged for Dropbox.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com