
3 British Founder Led Stocks With ROE Up To 48%
Credit is tightening worldwide as refinancing costs climb and lenders favour stronger borrowers. That backdrop puts a spotlight on founder led British businesses where leaders have their own wealth tied to long term outcomes and often treat capital more carefully. If you want to focus on aligned incentives while credit conditions get tougher, this article walks through three founding led stocks from our screener worth a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is personally invested in long term outcomes. However, if you want the strongest names, these 10 top founder-led companies are the top of the list.
Computacenter (LSE:CCC)
Overview: Computacenter is a founder influenced IT services group that supplies and manages large scale technology infrastructure for corporate and public clients.
Operations: Computacenter generates about £12.1b from computer services, with major contributions from the United Kingdom, Germany and the United States.
Market Cap: £5.1b
Computacenter links the founder led theme to a very large, operationally complex IT services platform where insiders have stayed financially invested for decades. That continuity has supported a return on equity of around 21.1% and strong recent earnings growth. For investors who care about aligned incentives, the real test is what happens if a single key assumption breaks in its tight profit margins.
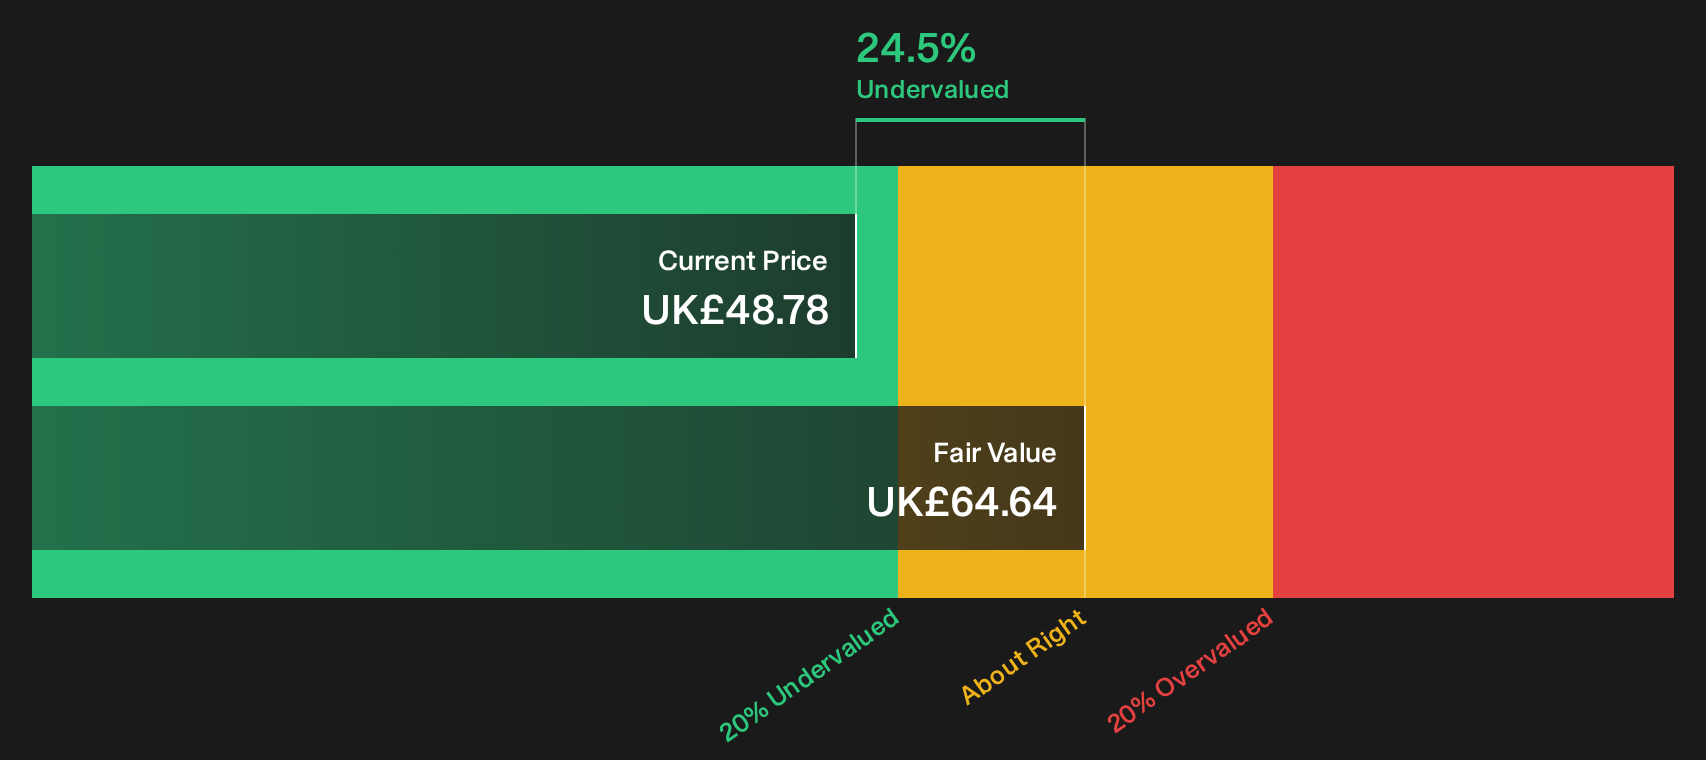
If that question is front of mind, jump into the DCF valuation analysis for Computacenter to see whether those margins leave much room for error or upside.
Applied Nutrition (LSE:APN)
Overview: Applied Nutrition develops and sells founder-led branded sports nutrition, hydration and wellness products to consumers in the UK and overseas.
Operations: Applied Nutrition generates about £134 million from sports nutrition products, with roughly £58 million from the UK, £58 million internationally and £18 million across Europe.
Market Cap: £789 million
Applied Nutrition fits this founder-led screen because executive leadership is closely tied to the Applied Nutrition and ABE product labels. Analyst commentary on Simply Wall St focuses on how that alignment relates to cash generation, capacity and growth potential.
"High reported free cash flow conversion of 72% in FY25, combined with an adjusted EBITDA margin of 29% and a net cash position, provides Applied Nutrition with room to pursue bolt-on capacity or capability investments that could add incremental revenue without materially increasing financial risk."
The key question is how that expanding production footprint would be used if an assumption about ongoing demand across newer regions were to weaken.
If that risk is on your radar, the full narrative for Applied Nutrition explains how Applied Nutrition could either keep accelerating or stall if those demand assumptions start to crack.

Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings manages infrastructure, private equity and venture capital funds, backing founder led SMEs with capital and governance support.
Operations: Foresight Group Holdings generates about £164.9 million in revenue, with around £114.8 million from Real Assets and £50.1 million from Private Equity.
Market Cap: £510 million
Foresight Group Holdings matters for this founder led screen because its private markets platform is built around supplying capital and board level oversight to owner managed SMEs. In addition, the bullish analyst Narrative on Simply Wall St sets out how fundraising in those products could reshape the earnings mix over time.
"Expansion of UK tax-efficient retail products, with management now targeting more than £600m of annual fundraising across these vehicles to the end of the decade after already reaching £630m of gross inflows in the latest year, offers scope for fee revenue and earnings to compound from a larger, more predictable retail asset base."
The real hinge is what happens to that story if one quiet pressure on fundraising momentum and fee margins starts to work against it.
If that pressure point interests you, read the full narrative for Foresight Group Holdings to see how fundraising momentum, fee mix and overlooked risks could be pulling Foresight Group Holdings in different directions.

Seeking Alternatives Before The Crowd?
Fresh opportunities rarely stay quiet for long. Strong momentum, potential breakouts and quietly flying under the radar for now. Scan these curated ideas before the crowd and consider your options.
- Spot established cash generators that still look overlooked and move through the 13 high quality undervalued stocks while pricing dislocations and sentiment gaps are still working in your favour.
- Target income streams that aim to keep paying even when sentiment drops and run through the 4 dividend fortresses before yields and valuations reset closer to consensus.
- Ride structural tailwinds in power demand while they still feel early and review the 44 power grid technology and infrastructure stocks before these infrastructure stories are more widely followed by mainstream momentum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com