
Rolls Royce Holdings And 2 Other British Nuclear Stocks To Own
Europe’s push to electrify everything has collided with the hard limits of wind and solar, putting reliable low carbon power back in the spotlight. For UK investors, that creates a clear opening in nuclear focused energy stocks that may benefit as grids seek round the clock supply. This article examines three notable nuclear energy stocks from our British-focused screener.
The three stocks highlighted here offer a compelling starting point if you want exposure to uranium producers, fuel suppliers, and nuclear power operators that feed reliable and sustainable power. However, if you want the strongest names, these 17 nuclear renaissance stocks are at the top of the list.
Rolls-Royce Holdings (LSE:RR.)
Rolls-Royce Holdings is a large industrial group that builds and services aero engines, defence systems and mtu branded power equipment, with a direct nuclear link through its Defence arm, which designs submarine reactor plants. Civil Aerospace contributes about £11.8b of revenue, Defence £5.0b, Power Systems £5.5b, and the company’s market value is roughly £111.3b.
The analyst consensus Narrative on Simply Wall St frames Rolls-Royce as a way to tap nuclear aligned engineering through small modular reactors alongside its wider power franchises, with the long term opportunity captured neatly in this view.
"Rolls-Royce SMR has secured multi-country selections and is already in execution for units in the UK, Sweden and the Czech Republic while aiming to commission up to 2 small modular reactors per year in the mid 2030s and up to 8 per year at maturity, creating a potential new source of high margin revenue and profit growth."
What happens to future returns will hinge on how one unseen pressure shapes the balance between higher margins and the cost of delivering them.
That pressure point is exactly what the Simply Wall St full narrative for Rolls-Royce Holdings unpacks, spelling out how Rolls-Royce could balance capital intensity, risk and accelerating nuclear opportunity.

National Atomic Company Kazatomprom JSC (LSE:KAP)
National Atomic Company Kazatomprom JSC is a Kazakhstan based uranium producer that also processes rare metals and provides various industrial and research services, with around KZT 1,697.0b of revenue from uranium, KZT 294.1b from other activities, and a market value near US$16.1b.
Kazatomprom matters for this nuclear energy list because it sits at the uranium fuel stage that reactors rely on. The analyst consensus Narrative on Simply Wall St frames that role in the context of long term nuclear build out and utility contracting that could shape pricing power.
"Global commitments to expand nuclear power capacity, including funding for new reactors and pledges to increase nuclear generation, continue to support expectations of sustained uranium demand growth, which can help National Atomic Company Kazatomprom JSC maintain pricing power and support revenue over time."
What happens to that pricing strength will depend heavily on how one stubborn cost pressure plays out against the firm’s long term contracts.
That contract tension is exactly where the Simply Wall St full narrative for National Atomic Company Kazatomprom JSC steps in. It outlines how Kazatomprom could balance cost inflation, uranium demand and long term pricing power.

Centrica (LSE:CNA)
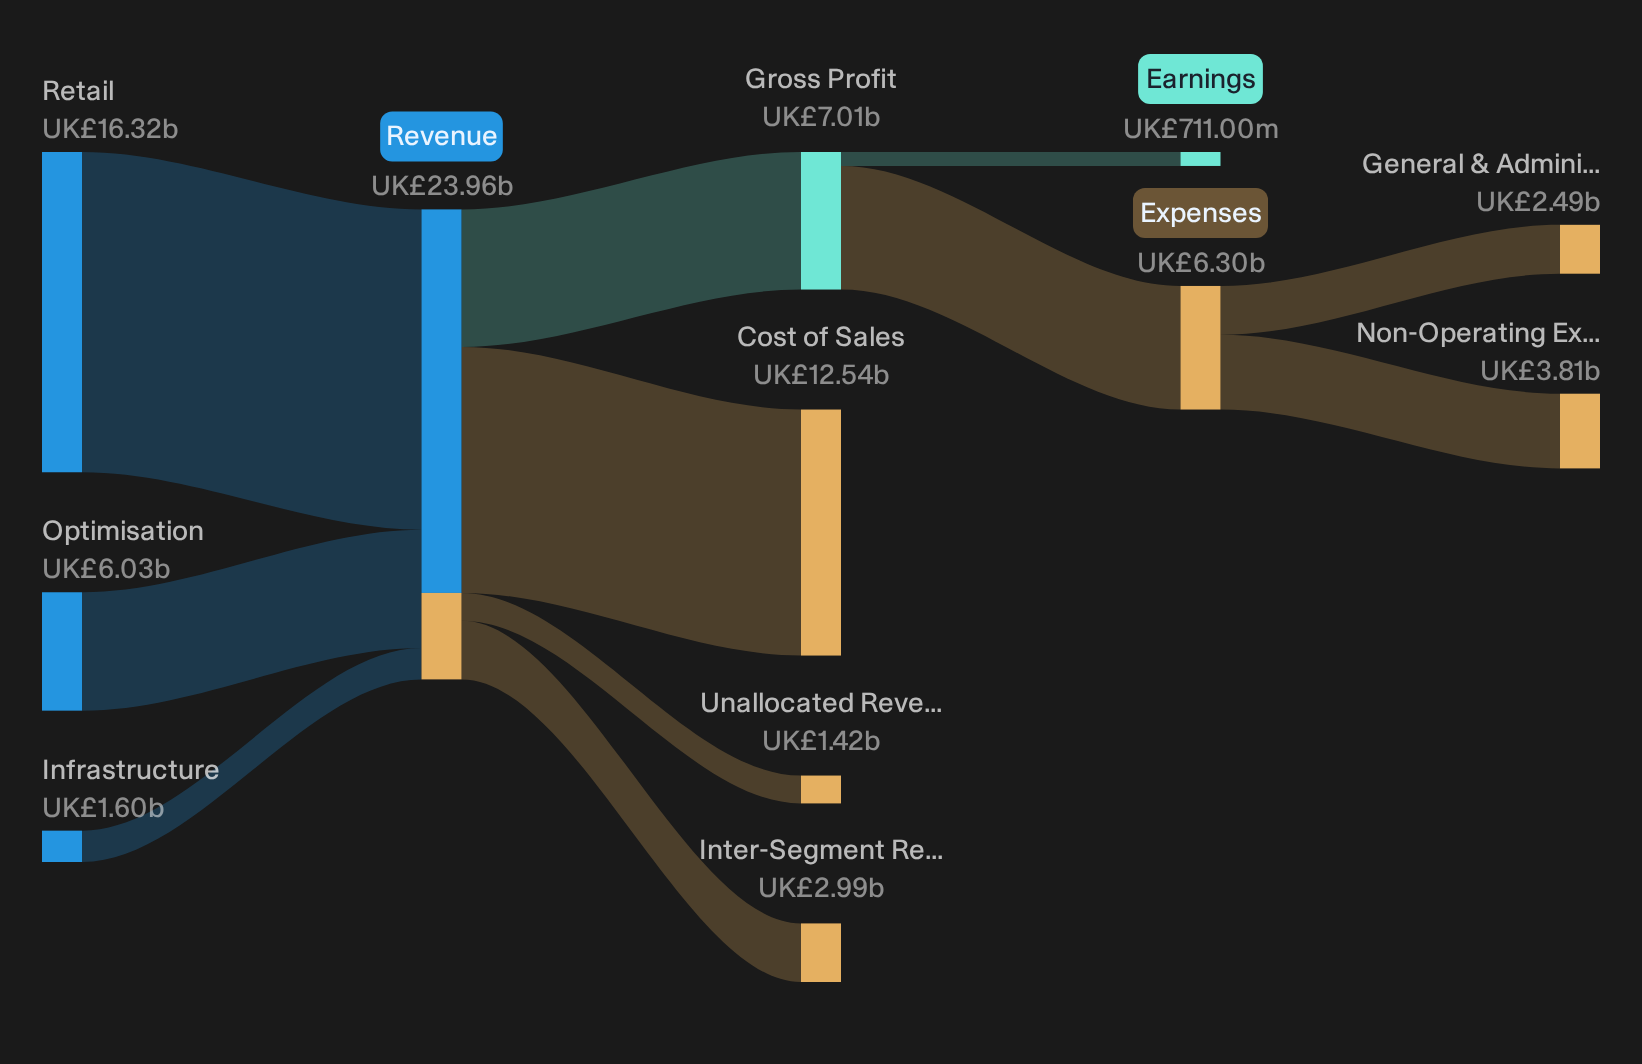
Centrica plugs into the nuclear energy theme through its power generation from nuclear assets, while most of its £16.3b top line still comes from Retail, supported by £6.0b from Optimisation and £1.6b from Infrastructure. The group has a market value of about £7.3b.
Centrica gives you nuclear-linked power generation inside a broader energy utility, and the analyst consensus Narrative on Simply Wall St frames the appeal around how a more contracted earnings base could change the quality of those cash flows.
"Expanding investment in regulated and contracted infrastructure such as Sizewell C, Grain LNG and the Meter Asset Provider, which together contributed about £80m of EBITDA in H1 2026 and are expected to reach roughly £175m in 2026, points to a growing base of long-duration earnings that can raise the share of predictable EBITDA and support more stable net margins."
The real swing factor is whether one stubborn credit issue lets that steadier infrastructure income translate into the margins investors are hoping for.
If that credit overhang is the real hinge, the full narrative for Centrica shows how Centrica’s contracted assets could turn today’s risk into quietly accelerating earnings quality.
Seeking Alternatives Before The Crowd?
Fresh opportunities rarely stay quiet for long. Strong themes gain momentum, prices start flying, and latecomers get caught chasing. Scan these under the radar ideas now and aim to position yourself earlier.
- Identify resilient cash generators that may hold up when others wobble by running the list of solid balance sheet and fundamentals (9 results) while the best options are still quietly priced.
- Explore income focused momentum by zeroing in on companies in the 4 dividend fortresses before yield hunters affect those payouts and entry yields start dropping.
- Look into the next automation trend by scanning the curated 88 robotics and automation stocks while adoption stories are still developing and attention remains limited.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com