
Scandic Hotels Group (OM:SHOT) On Strong Q3 Results Still Looks Fully Valued
Scandic Hotels Group (OM:SHOT) just released third quarter numbers that show higher sales and net income compared with a year earlier, a set of results that can sharpen how you think about the stock.
The earnings release and the new long lease for a 320 room Stockholm Globe area hotel appear to sit alongside a clear swing in sentiment, with Scandic Hotels Group’s share price return of 25.21% over 90 days and a 3 year total shareholder return near 19x both pointing to strong momentum rather than a short term bounce.
Scan Scandic Hotels Group’s latest move, then size up similarly resilient operators in our hand picked list of list of solid balance sheet and fundamentals (198 results)
Scandic Hotels Group has already delivered a sharp rebound in both the share price and recent earnings, so are you now looking at most of the upside behind you or still ahead on valuation grounds?
Most Popular Narrative: 10% Overvalued
On the analyst consensus Narrative on Simply Wall St, Scandic Hotels Group screens as roughly 10% above its narrative fair value of SEK96.75, compared with the latest close at SEK106.30. This puts more weight on execution and demand staying supportive.
The main thing that has to go right is that Scandic successfully executes its asset light, multi brand expansion and commercial platform investments while keeping central costs broadly stable and group leverage low.
See why 10 investors see Scandic Hotels Group as 10% overvalued.
Result: Fair Value of SEK96.75 (OVERVALUED)
Still, any prolonged weakness in Finland or a broader pullback in Nordic travel demand could quickly test how much optimism is embedded in the narrative for Scandic Hotels Group.
Find out about the key risks to this Scandic Hotels Group narrative.
Another View: Scandic Hotels Group Through A Cash Flow Lens
There is a different signal if you look at Scandic Hotels Group using the SWS DCF model. On that framework, the shares at SEK106.30 are trading about 32% below an estimated future cash flow value of roughly SEK155.60, which points to a very different risk reward profile than the analyst fair value.
Before leaning too heavily on that gap, it is worth asking how comfortable you are with the long run cash flow assumptions that sit inside any DCF and whether they still hold if trading conditions get tougher. Look into how the SWS DCF model arrives at its fair value.
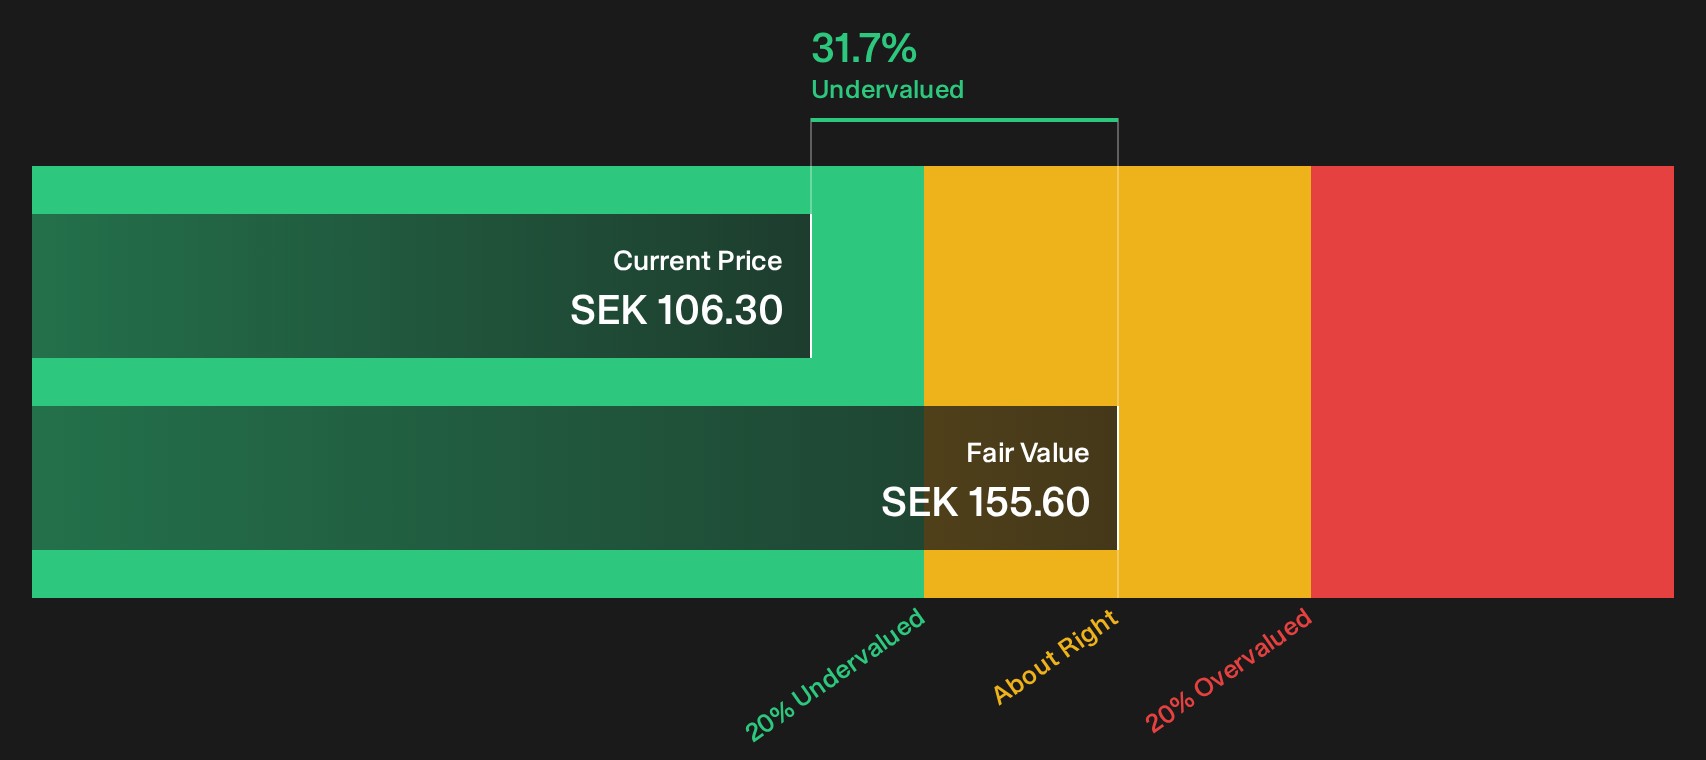
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Scandic Hotels Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Scandic Hotels Group is clearly split, so treat this moment as a prompt to move fast. Check the underlying data and decide where you stand based on the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Scandic Hotels Group?
If you only stop at Scandic Hotels Group, you risk missing other opportunities that could fit your style just as well or even better.
- Target resilient balance sheets and steady fundamentals by scanning our curated list of solid balance sheet and fundamentals (198 results) before conditions shift again.
- Hunt for mispriced quality by reviewing the 196 high quality undervalued stocks that pair sound finances with room for a stronger market view.
- Prioritise stability and income potential by checking out the 221 dividend fortresses built around higher yielding payers with robust profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com