
What Costain Group Holders Got Right
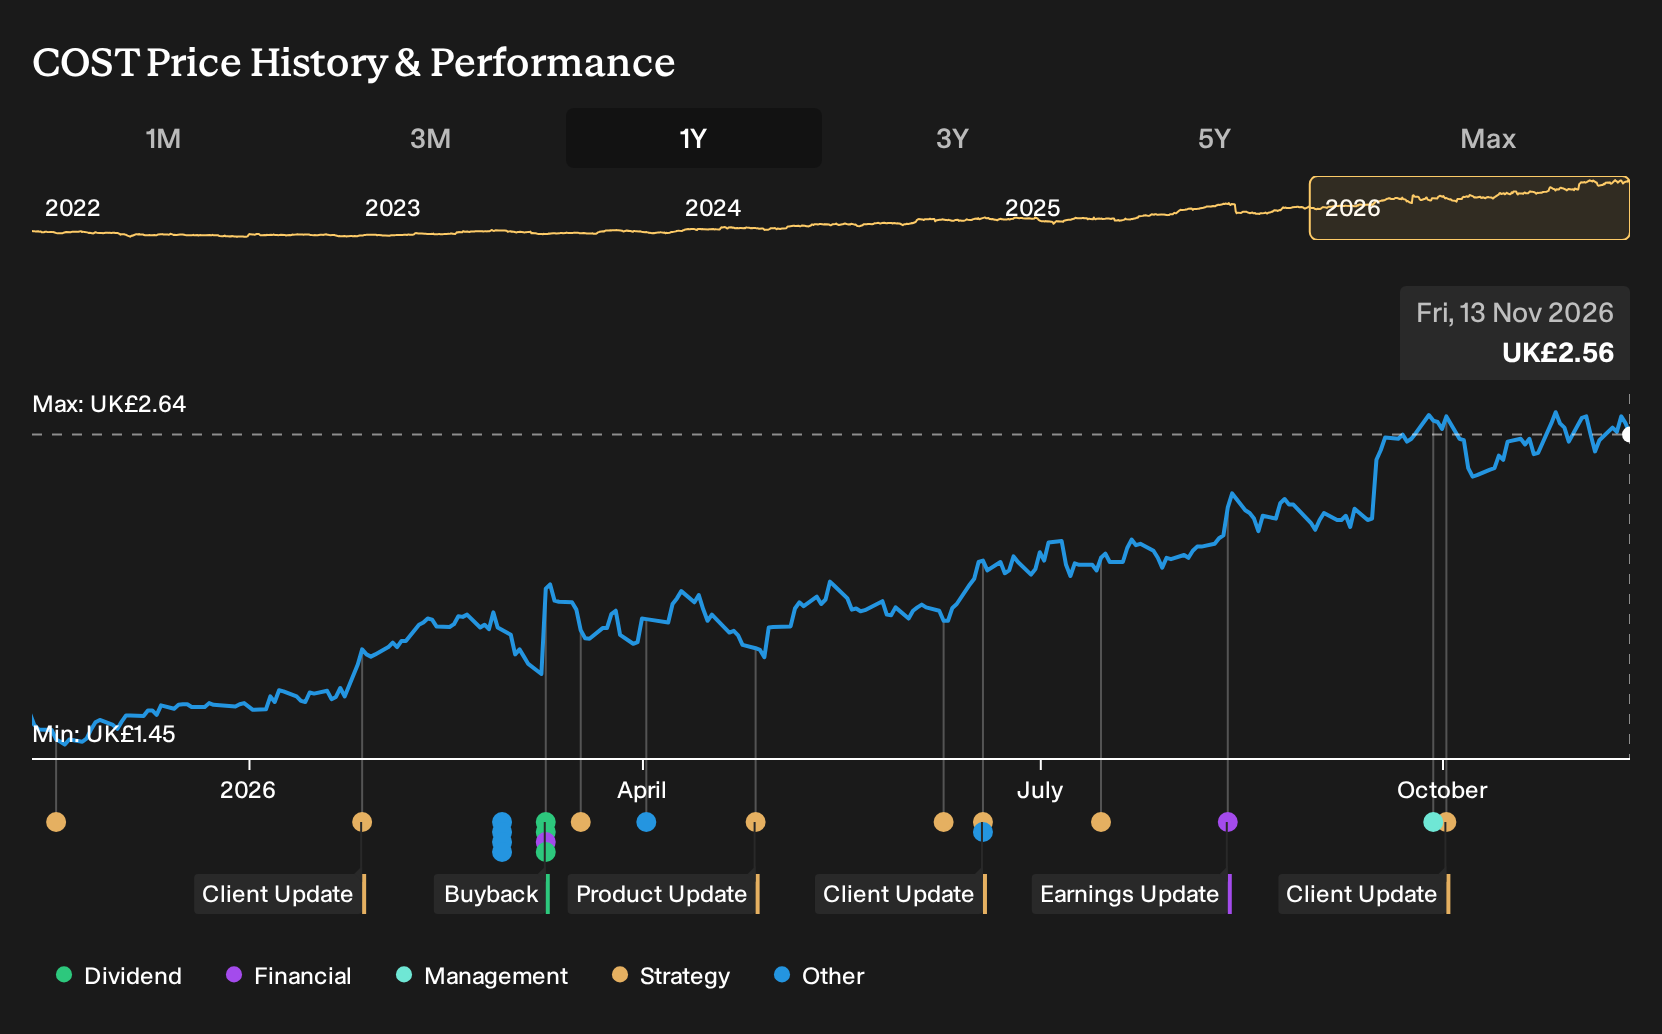
If you only skimmed headlines on Costain Group, the real action was hidden in dry contract updates and incremental earnings figures. Holding Costain Group over the past year would have returned 74.4%, including dividends. If you had been weighing a purchase in November 2025, you would have seen analysts split between upbeat government backed infrastructure demand and concerns about rising UK regulatory costs. What exactly did buyers think would have to go right before the later revenue and profit numbers arrived?
If the move has made Costain Group harder to judge, start where the gap is still open and scan 13 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On Costain Group
The shares cost £1.52 at the start of the period, and Costain Group sat between two sharply different stories about what came next.
On the upbeat side, one narrative saw government backed low carbon projects and AI tools supporting an implied Fair Value of £1.82. This level was tied to assumptions such as 8.1% annual revenue growth over three years.
The bearish view pointed to rising UK regulatory and labour costs, with an implied Fair Value of £1.15 based on slower 3.3% revenue growth and a future P/E of 8.1x.
What The Results Changed For Costain Group
The key fresh fact for Costain Group was the H1 2026 report. Revenue reached £543.1m against £525.4m a year earlier and net profit moved from £14.2m to £14.9m, with the reported net margin level at 2.7% in both periods. That pattern backed the cautious case that expected progress but not a clear step change in profitability.
The lesson is simple. When a story leans heavily on future margin upgrades, keep checking the reported net margin and profit per period against those earlier assumptions before updating your own view.
What Costain Group’s Price Already Assumes
Costain Group now trades at £2.56, and the bearish analyst Narrative on Simply Wall St sees its Fair Value sitting below that level despite record forward work.
The Narrative focuses less on order book size and more on whether Costain can consistently earn around 4% operating margins. A buyer today is effectively judging how execution and cost control shape that outcome.
"The main thing that has to go right is that Costain Group turns its record £7b forward work and growing positions in water, energy, nuclear and aviation into delivery at or above the guided 4% operating margin while keeping contract risk tightly controlled."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking One Step Beyond Costain
If Costain Group keeps winning complex infrastructure work, something else must quietly keep power flowing behind it.
You are not just relying on concrete, tunnels and control rooms. High voltage still has to be managed, directed and cooled before anything can run safely.
Another specialist concentrates on that grid to equipment link, turning raw electricity into something data centers and heavy sites can actually use.
Its gear handles transformer constraints, heat inside cabinets and violent fault currents that might otherwise stop entire projects.
If demand for power hungry assets keeps building, this behind the scenes operator could see its influence steadily widen.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 46% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com