
Should Dividend Reset Require Action From International Paper (IP) Investors?
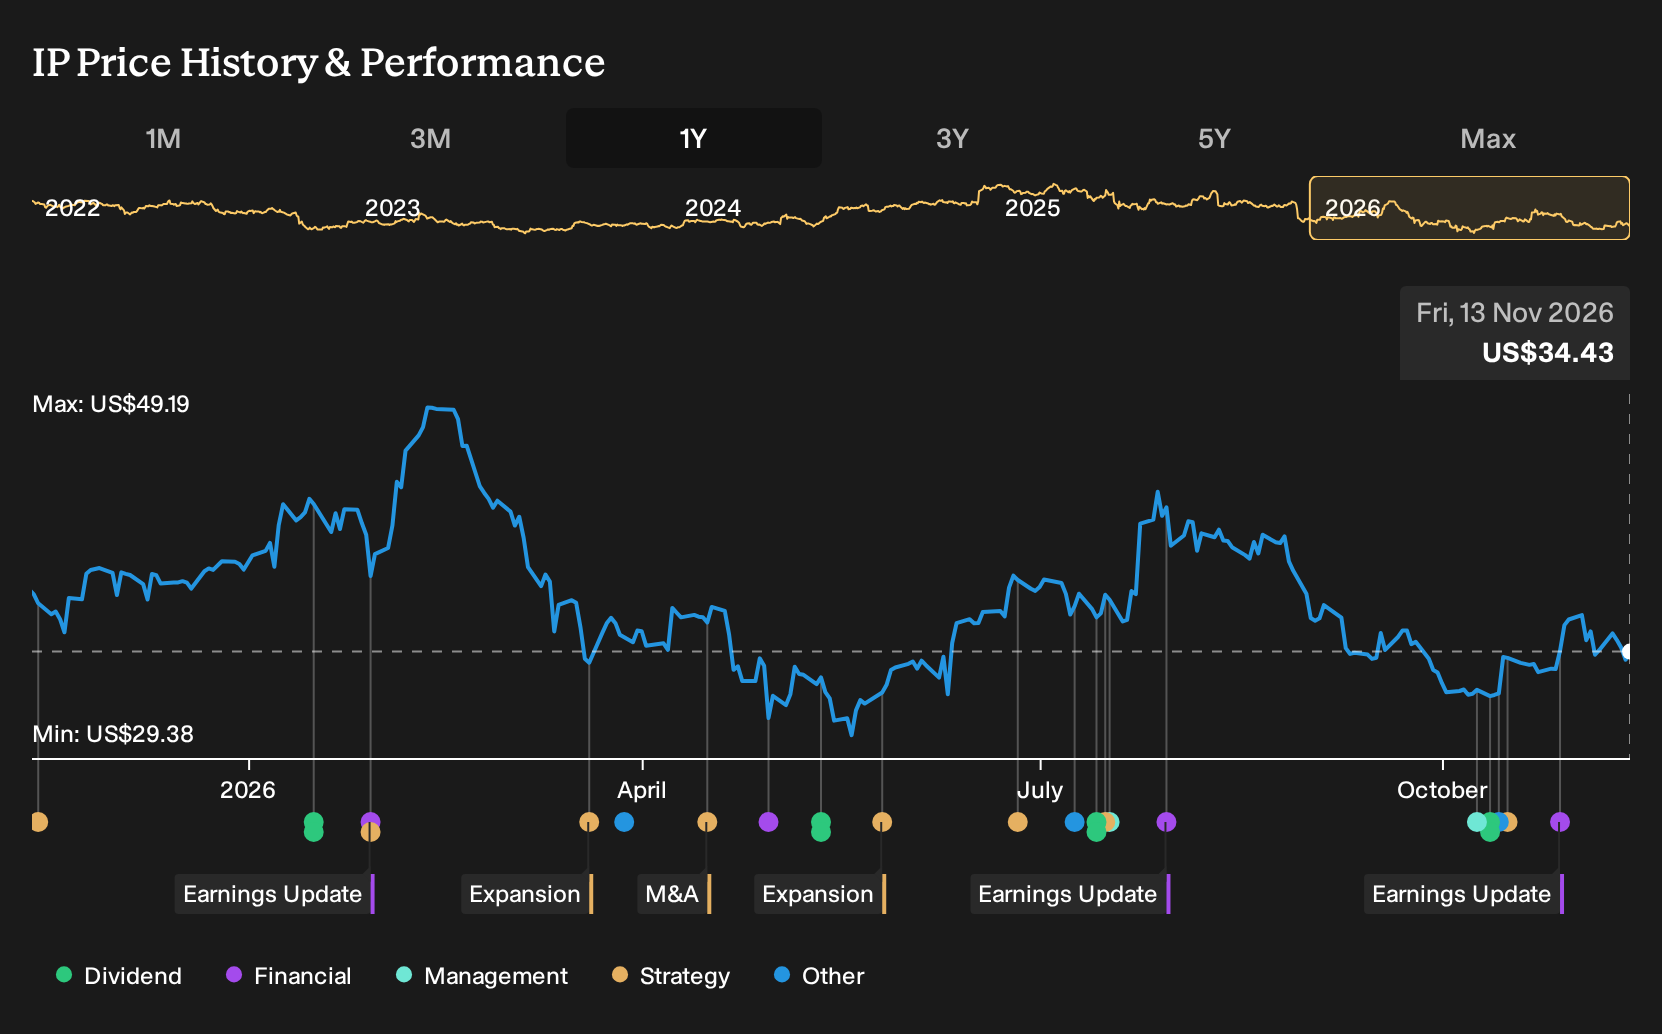
- International Paper's CEO recently outlined plans to reset the dividend to 40% to 50% of free cash flow after separating the EMEA business, a shift from the past year when payouts were far above free cash flow.
- This pivot toward a cash flow linked dividend targets a more sustainable return profile, at a time when North American packaging is recovering and management is signaling a tough 2027 ahead.
- The next area of focus will be how International Paper's evolving dividend policy could influence the existing investment narrative built around cost savings.
Compare International Paper's reset toward a cash flow linked payout with other income ideas by scanning our hand picked 6 dividend fortresses for potentially sturdy dividend profiles.
International Paper Investment Narrative Recap
To own International Paper, you need to believe the packaging cycle and the shift toward fiber based products give the business enough volume and pricing support for its cost and restructuring plans to matter. The analyst consensus Narrative on Simply Wall St leans on cost removal, footprint changes and pricing to lift profitability over time.
In the near term, the key catalyst is execution on North American packaging recovery and the targeted structural cost removal. At the same time, macro pressure and energy costs remain real swing factors. The reset toward a free cash flow linked dividend looks material for income investors but does not change those core operating risks.
The most relevant update here is management’s discussion of resetting the dividend to 40% to 50% of free cash flow once the EMEA packaging separation is complete. That directly addresses one of the clear risk flags, where recent dividends were not well covered by either earnings or cash generation.
For you, the link between payout and free cash flow brings attention back to the real catalyst. International Paper needs its cost programs, price actions and EMEA restructuring to translate into steadier cash inflow. If macro pressure, input inflation or execution gaps persist, dividend capacity and balance sheet flexibility both stay under pressure.
International Paper's current analyst narrative points to revenues of US$27.0b and earnings of US$1.8b by 2029, based on a 3.7% yearly revenue growth assumption and an earnings change of US$5.2b from a loss of US$3.4b today.
Uncover why International Paper's fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on International Paper leans heavily on weaker containerboard demand into 2027. In that more cautious setup, bearish analysts were only baking in about 2.7% annual revenue growth and saw earnings moving from a US$2.7b loss to US$2.4b by 2029. That is far more restrained than the consensus. Both narratives were framed before this dividend reset discussion, so you may see forecasts and opinions shift. It is worth lining up these contrasting assumptions and deciding which story feels closer to how you see the business playing out.
Explore 3 other International Paper fair value estimates, including one that suggests it could be worth just $42.30!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your International Paper research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for International Paper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate International Paper's overall financial health at a glance.
Looking for more investment ideas beyond International Paper?
If the shifting dividend story at International Paper has sharpened your focus on income, risk and balance sheet strength, it can help to widen the lens and compare what you see here with other listed businesses.
- For investors who want income backed by robust financials, scan a curated 6 dividend fortresses that aims to balance yield with resilience.
- If value and quality matter most to you, review a focused 34 high quality undervalued stocks that combines stronger cash generation with healthier fundamentals.
- When capital protection sits higher on your priority list, filter for stability using a 29 resilient stocks with low risk scores that screens well on resilience metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com