
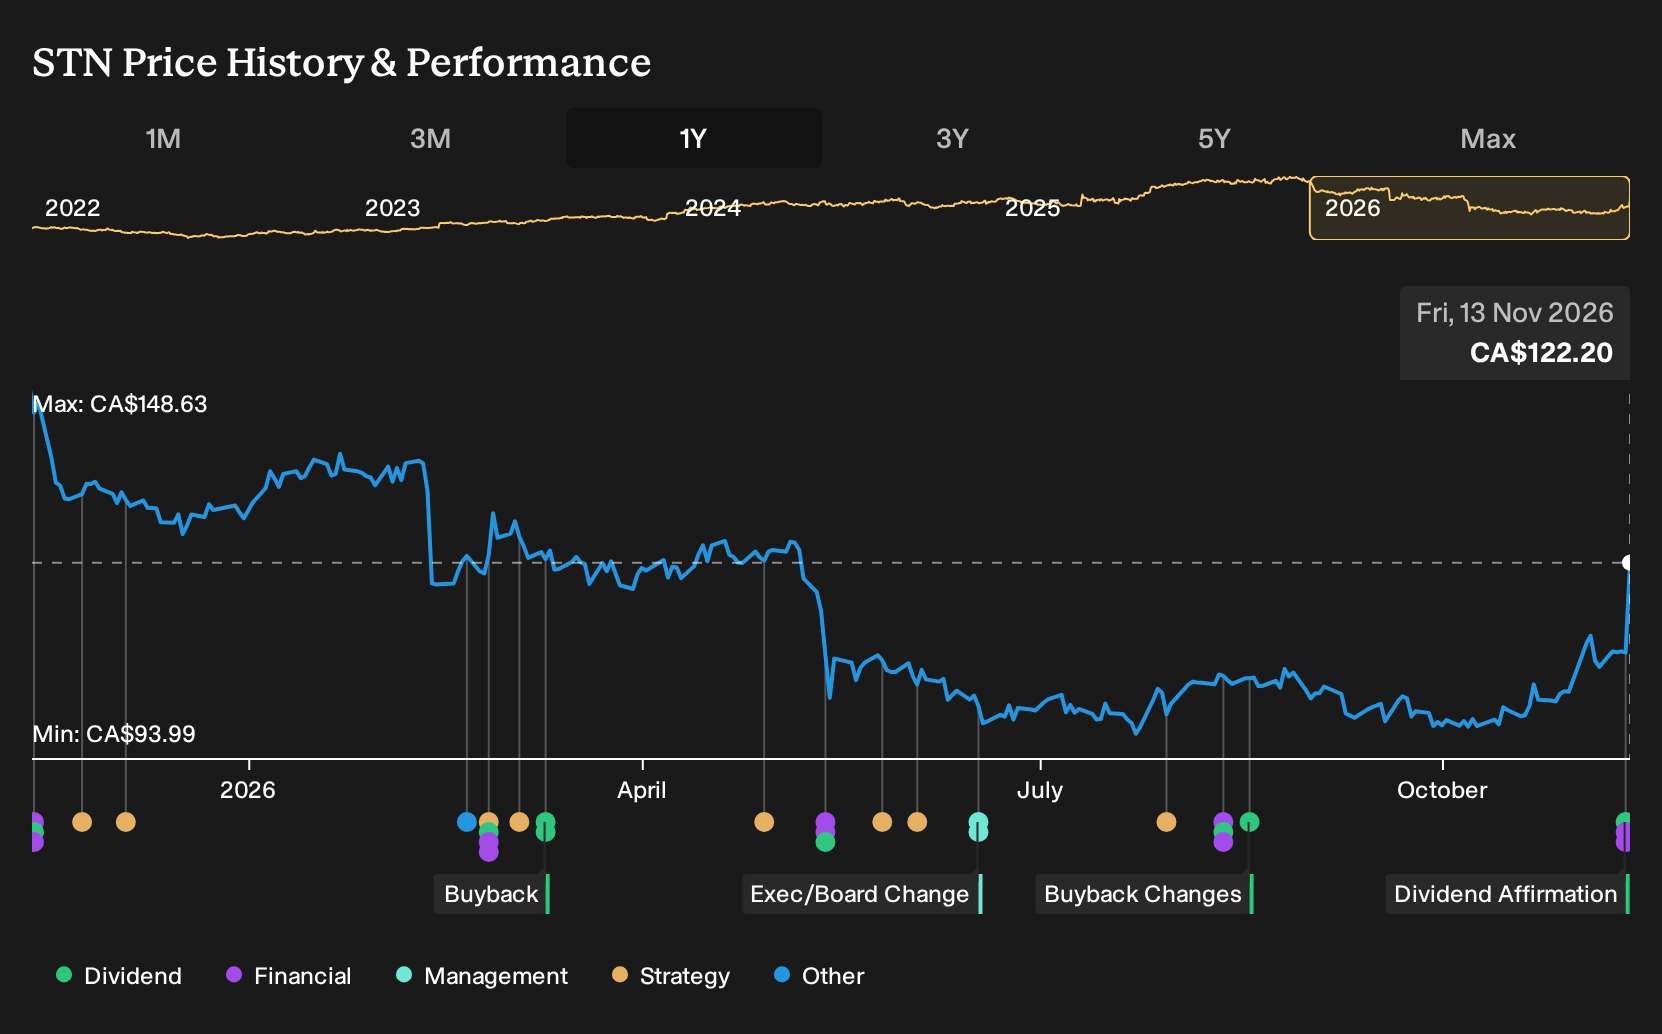
Stantec (TSX:STN) Is Up 13.8% What's Changed After Raised Guidance
- Stantec reported strong Q3 2026 results with higher sales, revenue and net income, raised full year net revenue and profitability guidance, and affirmed a quarterly dividend of C$0.245 per share payable in January 2027.
- Management reiterated disciplined, accretive acquisitions as the top capital priority, linking M&A, record backlog and free cash flow to both growth investment and ongoing shareholder returns.
- This article examines how Stantec’s investment narrative is influenced by the raised 2026 guidance and management’s focus on disciplined acquisitions.
Scan other infrastructure and engineering stocks that pair strong balance sheets with disciplined deal activity through our curated list of solid balance sheet and fundamentals (6 results) while you assess Stantec’s acquisition focused playbook.
Stantec Investment Narrative Recap
To be comfortable owning Stantec, you need to believe the firm can keep turning its record backlog and steady infrastructure demand into healthy earnings and cash flow while integrating recent deals like Page and Niche. The raised 2026 net revenue and profitability guidance, alongside strong Q3 numbers, points to execution on that thesis. The near term catalyst is continued margin delivery as acquired businesses are folded in and delayed U.S. work stays on track.
The biggest risk still sits in integration complexity and working capital. Management is leaning into disciplined acquisitions as the top capital use, which concentrates execution risk around deal timing, integration cost and collections. Recent guidance and commentary suggest the latest results do not materially change that risk profile or the core operating story.
The most relevant recent announcement here is management’s reaffirmation that disciplined, accretive acquisitions remain the primary capital priority, backed by a strong balance sheet and free cash flow. That stance links directly to the analyst consensus Narrative on Simply Wall St, which describes M&A plus a record backlog as key elements in the company’s earnings and margin potential.
For catalysts, the key focus is on how each new transaction affects operating trends that already matter. That includes Q3’s mix of organic growth and acquisition contribution, the raised EBITDA margin guidance, and the need to keep U.S. project ramps progressing. Missteps on integration or collections would quickly show up in margins and cash generation, which are central to both the acquisition program and ongoing dividends.
Stantec's current narrative anchors on analysts expecting revenues of CA$8.0b and earnings of CA$832.0m by 2029, based on forecast revenue growth of 5.6% a year and an earnings increase of about CA$327.0m from CA$505.0m today.
Uncover why Stantec's fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between C$132.80 and about C$155.67, with some members seeing Stantec as materially undervalued relative to current pricing. Others flag acquisition integration, working capital and U.S. project timing as swing factors, so explore these differing views before deciding how Stantec fits your portfolio.
Explore 3 other Stantec fair value estimates, including one that suggests potential upside of as much as 27% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Stantec research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Stantec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stantec's overall financial health at a glance.
Looking for more ideas beyond Stantec?
Once you have weighed up Stantec, it can help to compare it with other companies that share some of the qualities you care about most, whether that is valuation support, balance sheet strength or a pipeline of less followed opportunities.
- If you want potential value with quality fundamentals, review our curated list of 6 high quality undervalued stocks that match disciplined financial profiles.
- For investors who prioritize resilience and capital protection, scan a focused set of 9 resilient stocks with low risk scores that score well on our risk metrics.
- If you prefer lesser known opportunities with solid financial underpinnings, check out a handpicked group of 10 high quality undiscovered gems that sit off the usual radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com