
How Investors Are Reacting To Everest Group Stock Class Action Lawsuits
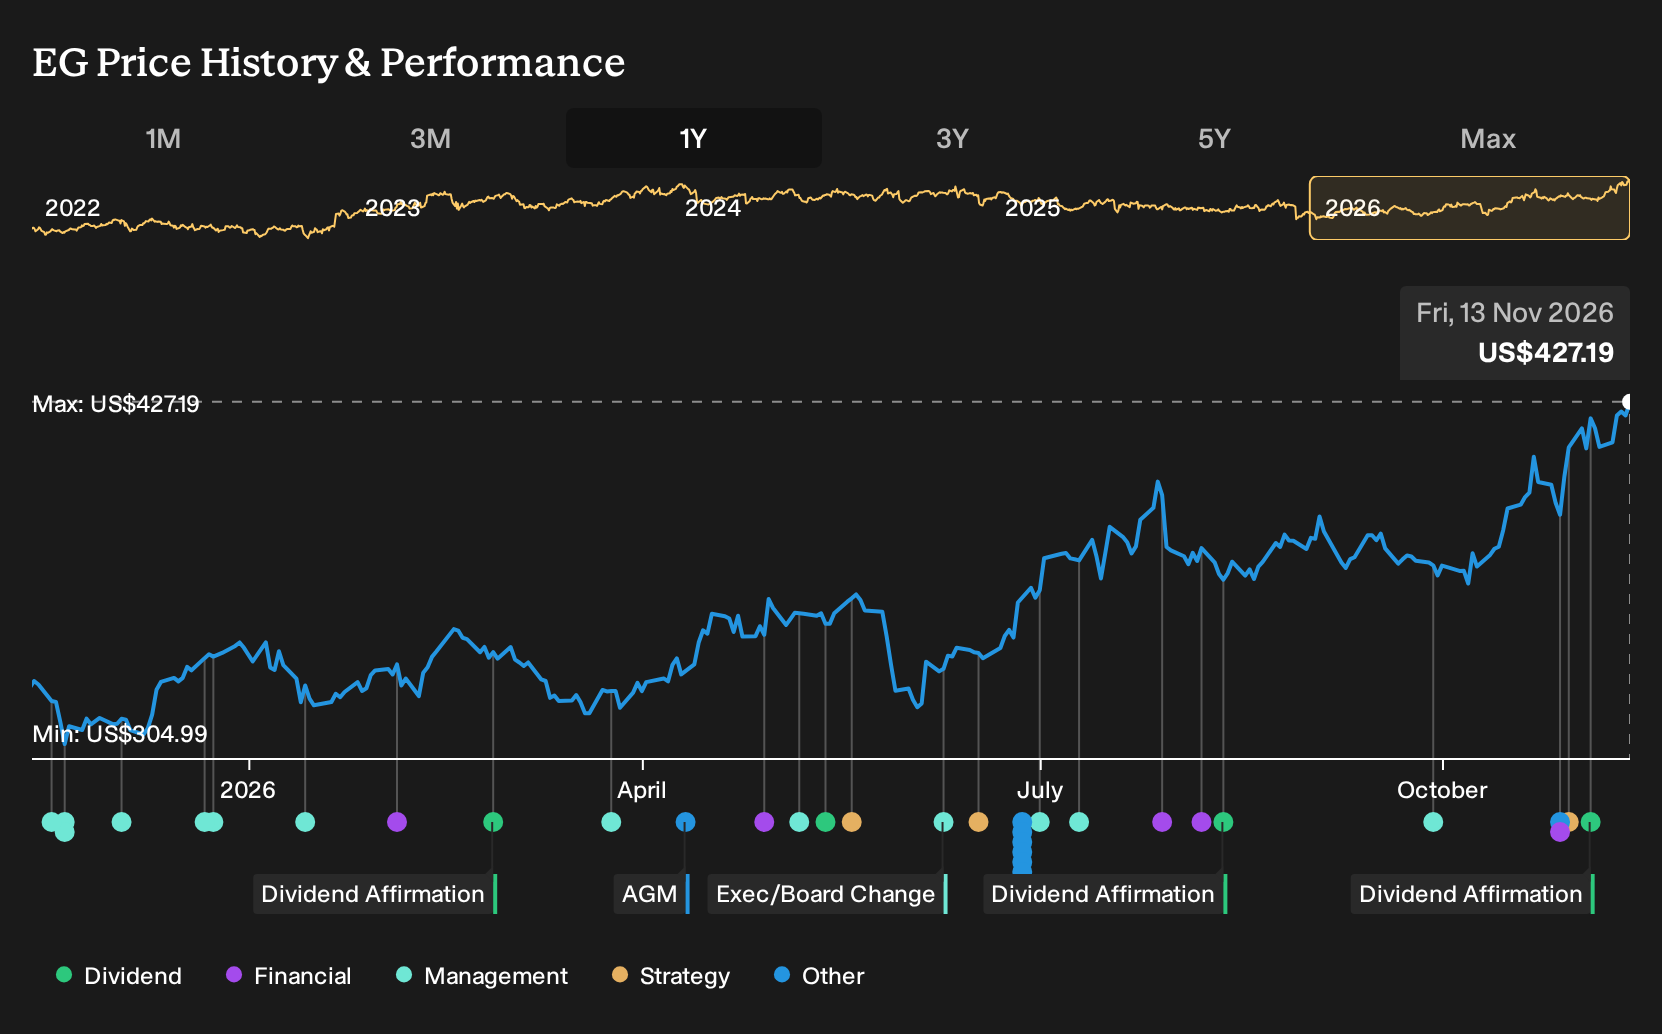
- Everest Group, Ltd. previously declared a dividend of $2.00 per common share, payable on or before December 18, 2026 to shareholders of record on December 4, 2026, while now facing securities class actions tied to U.S. casualty reserve disclosures.
- Class action filings and the focus on $478 million in prior year reserve development have placed Everest Group's risk management, reserving discipline, and communication practices under a harsh spotlight.
- The next area of attention will be how Everest Group's investment narrative interacts with the reserve strengthening pressures highlighted by recent lawsuits.
Scan beyond Everest Group and stress test your portfolio against insurance reserve and balance sheet risks with our hand picked list of solid balance sheet and fundamentals (24 results)
What Is Everest Group's Investment Narrative?
To own Everest Group, you need to buy into a fairly simple idea. This is a large reinsurance and insurance platform that lives or dies on underwriting discipline, reserve accuracy, and investment returns on a sizeable balance sheet. The recent $2.00 per share dividend affirmation signals the board is still comfortable returning cash, even as securities class actions focus attention on the $478 million of prior year reserve development and U.S. casualty exposure. That sits alongside AM Best’s A+ Financial Strength Rating with a negative outlook, which keeps pressure on Everest Group to prove its reserving and risk controls are tight in the near term.
In the short term, the real swing factors are pricing power in property and casualty lines, the pace of reserve strengthening, and how fast the newer management team tightens underwriting in U.S. casualty. Everest Group has recently recorded strong earnings and net profit margins of 11.5% on US$16.2b of revenue, with the stock trading on a P/E of 8.5x and offering a 1.87% dividend yield. The lawsuits and the rating outlook introduce headline and execution risk, yet the recent share price gains and continued dividend policy suggest investors are still weighing those issues against perceived value in the business model.
Yet there is one structural pressure on this story that only really shows up once you look closely at ...
There's only one way to know the right time to buy, sell or hold Everest Group. Head to Simply Wall St's company report for the latest analysis of Everest Group's Fair Value.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$433 to just under US$1,350, which shows how far opinions on Everest Group can stretch. These retail perspectives were formed before the reserve related lawsuits and the recent dividend affirmation, so use them as a starting point and compare several alternative viewpoints before deciding how Everest Group fits your own thesis.
Explore 3 other Everest Group fair value estimates, including one that suggests up to 216% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Everest Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Everest Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Everest Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Everest Group?
Once you have a view on Everest Group, it can help to widen the lens and compare it against other companies with different risk and return profiles using the Simply Wall St Screener.
- For investors who want potential value paired with quality fundamentals, review our hand picked 34 high quality undervalued stocks that meet those filters.
- If income reliability matters to you, scan a curated set of yield focused opportunities through the 6 dividend fortresses built to highlight stronger payers.
- When capital preservation is a priority, narrow your watchlist to financially resilient companies using the 29 resilient stocks with low risk scores tailored for stability first.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com