
How Strong Revenue Guidance Will Impact Cloudflare (NET) Stock
- Cloudflare reported third quarter 2026 sales of US$782.51 million and a net loss of US$34.07 million, alongside new full year 2026 revenue guidance of about US$2.96 billion.
- The business paired rapid top line expansion with widening losses and installed a seasoned President of Revenue, Christian Smith, to oversee global go to market execution.
- Next, the focus turns to how Cloudflare's strong revenue guidance, set against sector caution, may reshape the longer term investment narrative.
Scan beyond Cloudflare and identify other fast scaling software players with resilient fundamentals using our curated list of 19 high quality undiscovered gems.
Cloudflare Investment Narrative Recap
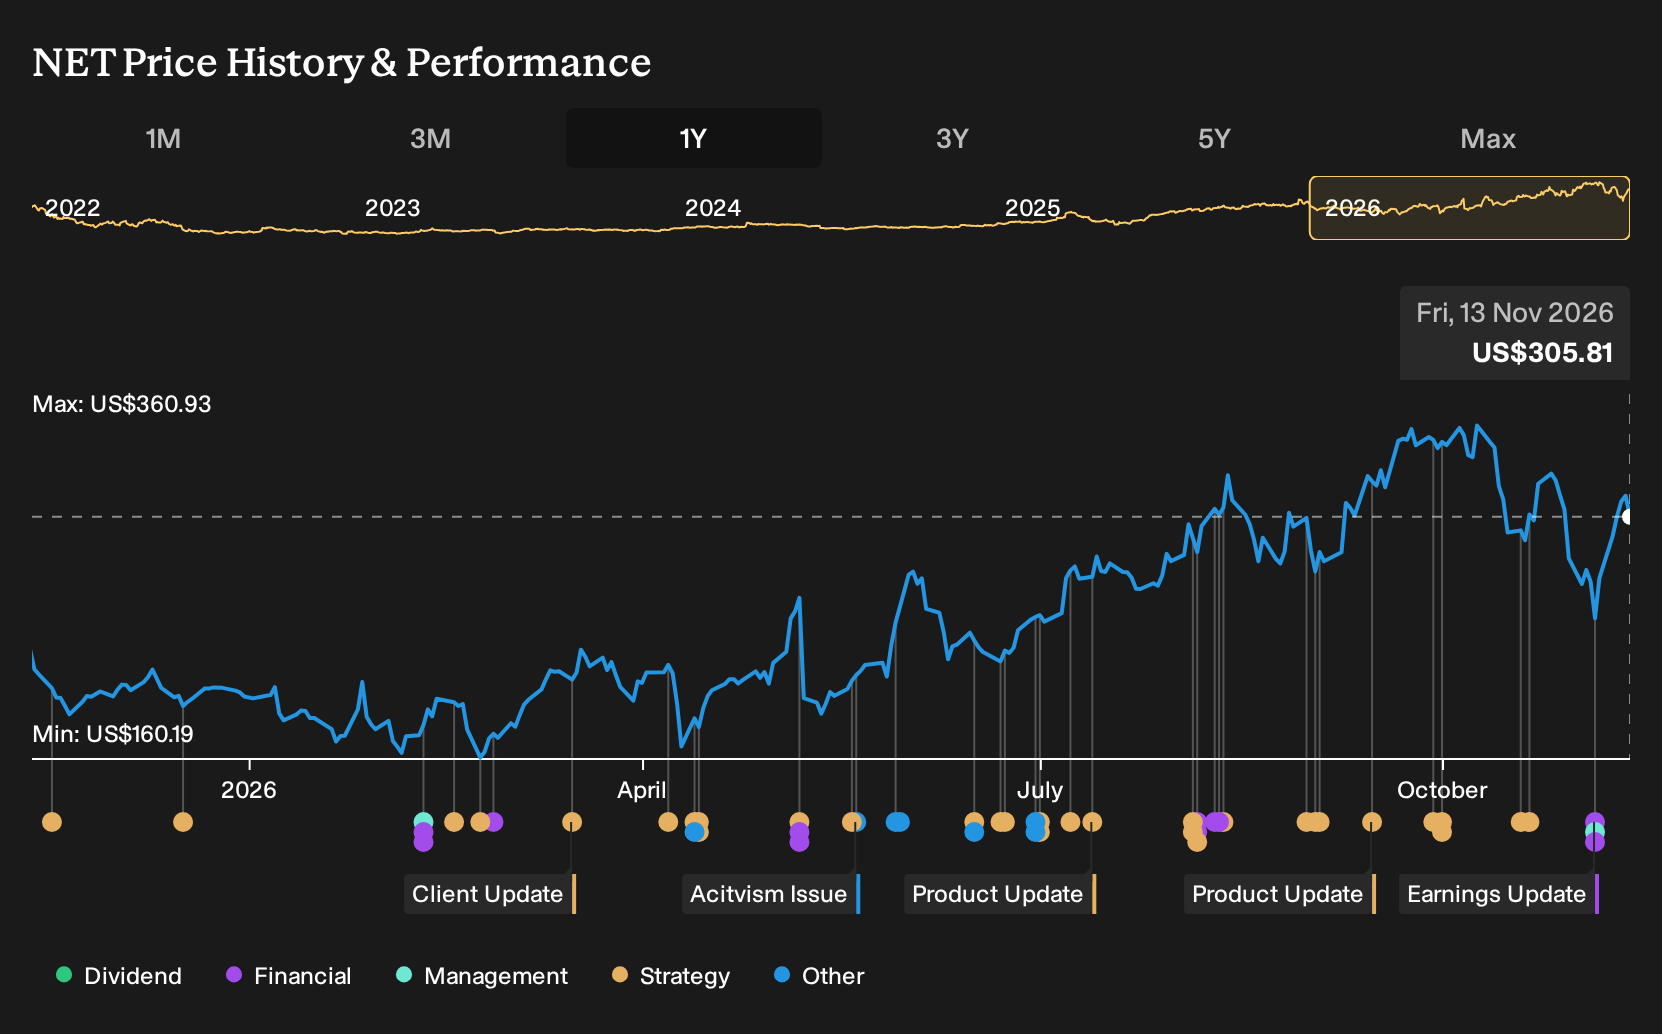
To own Cloudflare, you need to believe in its role as a core security and internet infrastructure provider as Q-Day and broader cyber risks get more attention, as argued by DaneDruss, a Simply Wall St Community investor who wrote the Narrative. The latest quarter keeps that story focused on scale. Revenue reached US$782.51 million in Q3 2026 with full year guidance of about US$2.96b, but the company still reported a loss.
The key near term catalyst remains execution on high growth while losses narrow. Q3 results did not meaningfully change that. Net loss for the quarter was US$34.07 million and US$226.97 million for the first nine months of 2026, so sustained cash burn remains the biggest operational risk, especially with Cloudflare already trading on a rich P/S multiple.
The most relevant update is the appointment of Christian Smith as President of Revenue. Smith has led large go to market engines at Splunk, Cisco, Nintex and Oracle, including an on premises to SaaS transition that reached more than US$4b in annual recurring revenue. That background lines up directly with Cloudflare’s push toward higher enterprise adoption and usage based cloud services.
For you as a shareholder or potential shareholder, this role is closely tied to both catalysts and risk. Cloudflare now has ambitious internal talk of scaling toward US$5b in annual recurring revenue, while still loss making with a premium valuation and some recent insider selling flagged. Execution quality in Smith’s organization, from sales productivity to renewals and channel leverage, will heavily influence whether strong revenue guidance translates into a more resilient and eventually profitable model.
DaneDruss’ narrative reaches its fair value of US$167.45 per share by pairing 30.0% annual revenue growth with a 25.0% future profit margin, then applying a forward earnings multiple and discounting those projected profits back to today using a required return assumption.
Uncover why Cloudflare's fair value indicates a 45% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One bullish twist on Cloudflare focuses on agentic AI traffic and the monetization stack around Workers. The highest analysts were already penciling in about 38.4% annual revenue growth and US$6.7b in sales by 2029, along with US$685.6 million in earnings. Those forecasts pre date this quarter, so you may see their story evolve from here.
Explore 8 other Cloudflare fair value estimates, including one that suggests as much as 41% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cloudflare research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cloudflare. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cloudflare's overall financial health at a glance.
Looking For More Cloudflare Investment Ideas Beyond One Stock?
If this Cloudflare update has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you quickly surface other companies that fit very different risk and return profiles.
- Prefer quality at a reasonable entry point and a focus on fundamentals? Filter for that mix using our 34 high quality undervalued stocks to see which businesses currently line up.
- Want balance sheet strength to sit at the core of your process? Build a shortlist from the list of solid balance sheet and fundamentals (24 results) and keep an eye on financially resilient operators.
- Looking to dial down volatility without stepping away from equities altogether? Start with the 29 resilient stocks with low risk scores and compare what you find with your existing holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com