
Should Raised 2026 Outlook Require Action From H World Group (HTHT) Investors?
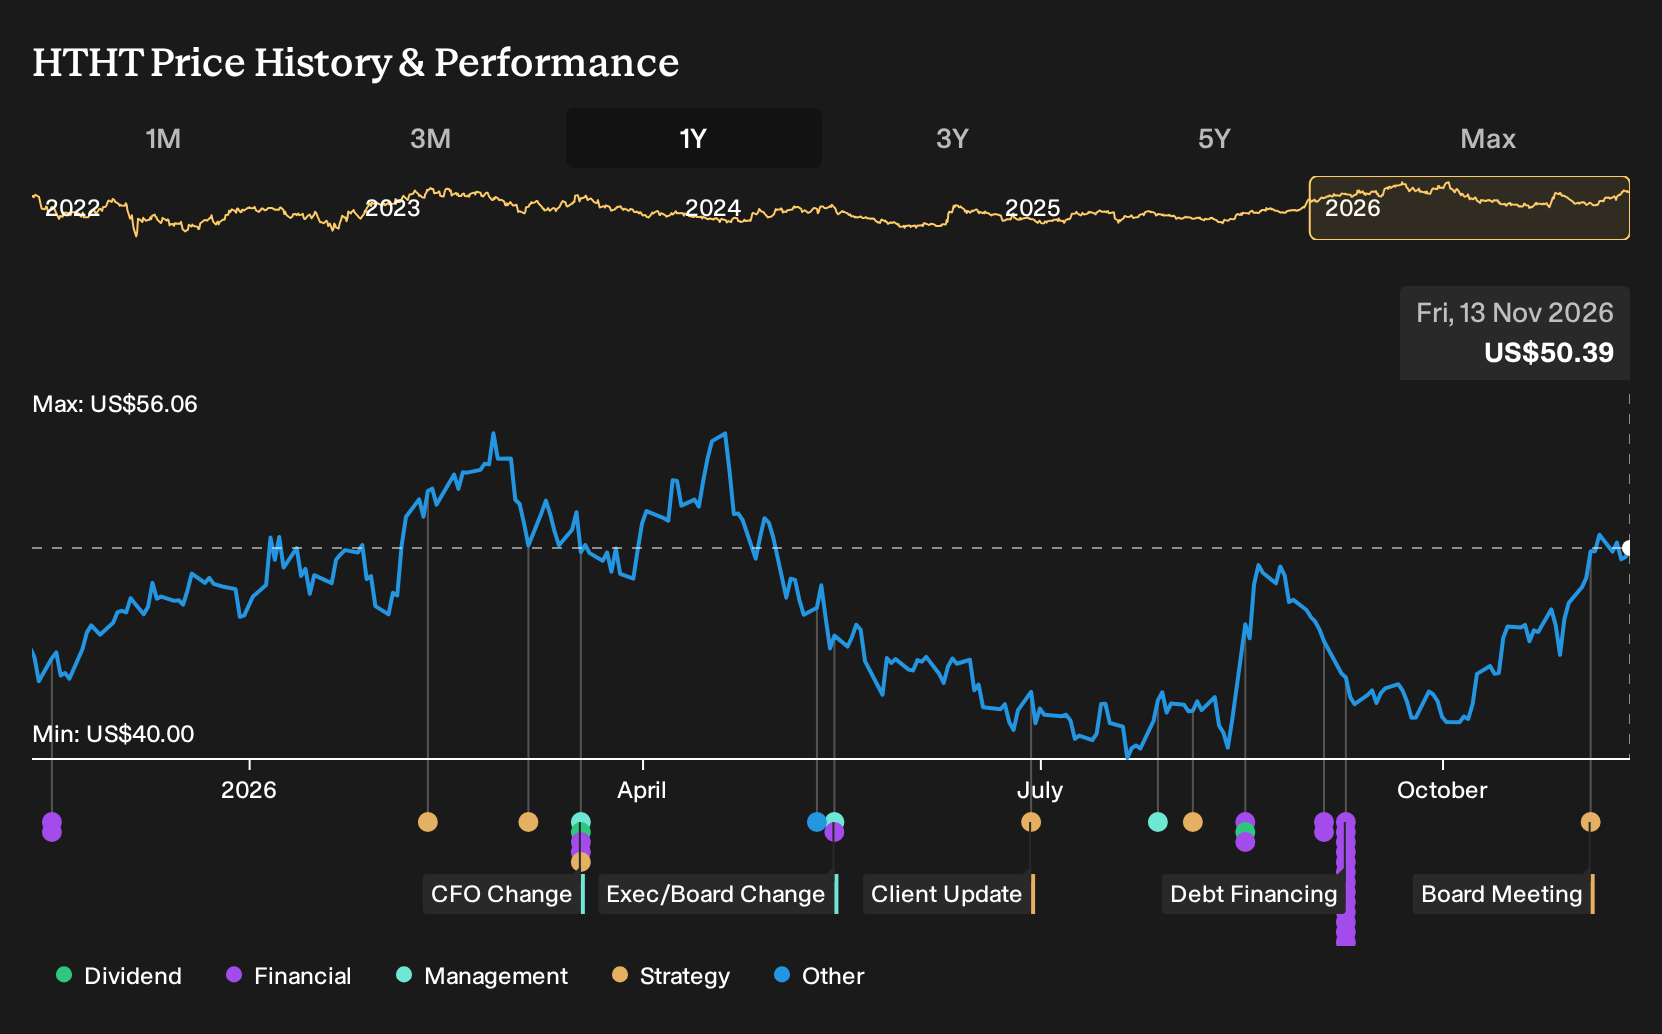
- H World Group raised its 2026 revenue growth outlook to 4% to 8%, reported second quarter revenue of RMB 7,121 million, and plans to open 2,200 to 2,300 gross hotels while returning about US$2.8b through dividends and a three year shareholder return plan.
- The combination of higher growth guidance and a large, multi year capital return package reflects management confidence in H World Group's asset light hotel expansion and cash generation capacity.
- We will now explore how H World Group's upgraded 2026 revenue outlook could influence the investment narrative built around asset light expansion.
Scan other hotel and consumer names built on similar asset light models by reviewing our curated list of 19 high quality undiscovered gems before you decide where H World Group fits in your portfolio.
H World Group Investment Narrative Recap
To own H World Group, you need to believe its asset light manachise and franchise model can keep scaling even as new hotel supply and softer consumer spending pressure RevPAR. The upgraded 2026 revenue outlook to 4% to 8% leans into that view, although management still talks about flat to slightly higher RevPAR, which keeps demand risk front and center.
The key near term swing factor is whether the planned 2,200 to 2,300 gross hotel openings can ramp without dragging on operating margins if same hotel RevPAR stays weak. The biggest risk is that continued expansion into lower tier cities locks in underutilized rooms, repeating the early 2026 pattern of softer RevPAR and net income pressure.
The clearest recent datapoint tied to this story is the three year shareholder return plan of about US$2.5b plus the roughly US$275m dividend, which together put total planned cash returns near US$2.8b. For a business leaning on an asset light model, that kind of capital return relies on continued fee based cash generation and disciplined use of leverage.
For you as an investor, that announcement connects directly to the catalysts in the analyst consensus Narrative on Simply Wall St, which highlights higher margin franchise and manachise growth and improving earnings quality. The tension is that dividends and buybacks compete with funding aggressive network expansion, so execution on hotel openings, RevPAR stabilization, and balance sheet risk will likely shape how sustainable this payout path looks over the next few years.
H World Group's narrative projects CN¥31.5b revenue and CN¥7.5b earnings by 2029. This assumes 5.8% yearly revenue growth and an earnings increase of about CN¥2.5b from CN¥5.0b today.
Uncover how H World Group's fair value indicates a 23% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
One optimistic twist in the alternate H World Group narrative is how some analysts frame the new three year capital return in relation to margin potential. Before this news, the most bullish group already pencilled in CN¥34.0b revenue and CN¥8.6b earnings by 2029. That is a step up from the consensus CN¥31.5b and CN¥7.5b view. Those higher expectations were set without this latest revenue guidance and shareholder return plan in mind. Use that gap as a prompt to compare different scenarios rather than rely on a single story.
Explore 2 other H World Group fair value estimates, including one that suggests there could be as much as 23% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your H World Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for H World Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate H World Group's overall financial health at a glance.
Looking for more investment ideas beyond H World Group?
If you want to stress test your thesis on H World Group, line it up against other businesses with different balance sheet strength, payout profiles, and valuation setups. The Simply Wall St Screener can help you quickly filter the wider market so you spend more time comparing fundamentals and less time trawling through tickers.
- Prefer dependable balance sheets over story stocks? Filter for companies with robust finances and steady fundamentals using our list of solid balance sheet and fundamentals (24 results).
- If downside risk control matters most to you, narrow your watchlist to relatively resilient profiles with the 29 resilient stocks with low risk scores.
- For income focused ideas, zero in on companies offering higher yields and resilient payouts through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com