
PACS Group (PACS) Lifted Guidance, Is The Upside Already Priced In?
PACS Group (PACS) drew fresh attention after reporting third quarter and nine month 2026 results, followed by higher full year revenue guidance. This gave investors new numbers to weigh around this senior care operator.
PACS Group’s recent guidance hike lands after a powerful run, with the share price delivering a 22.3% year to date share price return and a very large 1 year total shareholder return of 356.71%. However, the 7 day share price return declined 2.58%, which hints that momentum is still positive over the longer stretch, but short term enthusiasm has eased.
Scan other senior-care and healthcare operators showing similar momentum with the list of solid balance sheet and fundamentals (24 results) as potential comparisons to PACS Group after this guidance upgrade.
The question now is straightforward. After a very large 1 year return and higher guidance, does PACS Group still offer a favourable balance between upside potential and the risk you are taking at this valuation?
Most Popular Narrative: 23% Undervalued
PACS Group’s latest close of $48.32 compares to a fair value of $62.50 in the analyst consensus Narrative on Simply Wall St. This applies a 7.4% discount rate to updated earnings and revenue forecasts and ties that to the Street’s revised expectations.
Rising demand for post-acute and long-term care from an aging U.S. population, combined with PACS Group's expanding footprint of over 35,000 beds, creates room for continued top line growth as occupancy and patient volumes increase, supporting higher revenue and earnings.
See why 14 investors see PACS Group as 23% undervalued.
Result: Fair Value of $62.50 (UNDERVALUED)
Still, the bullish PACS Group story depends on smooth integration of more than 100 recently acquired facilities, as well as Medicaid and quality incentive frameworks staying supportive in key states.
Find out about the key risks to this PACS Group narrative.
Another View on PACS Group’s Valuation
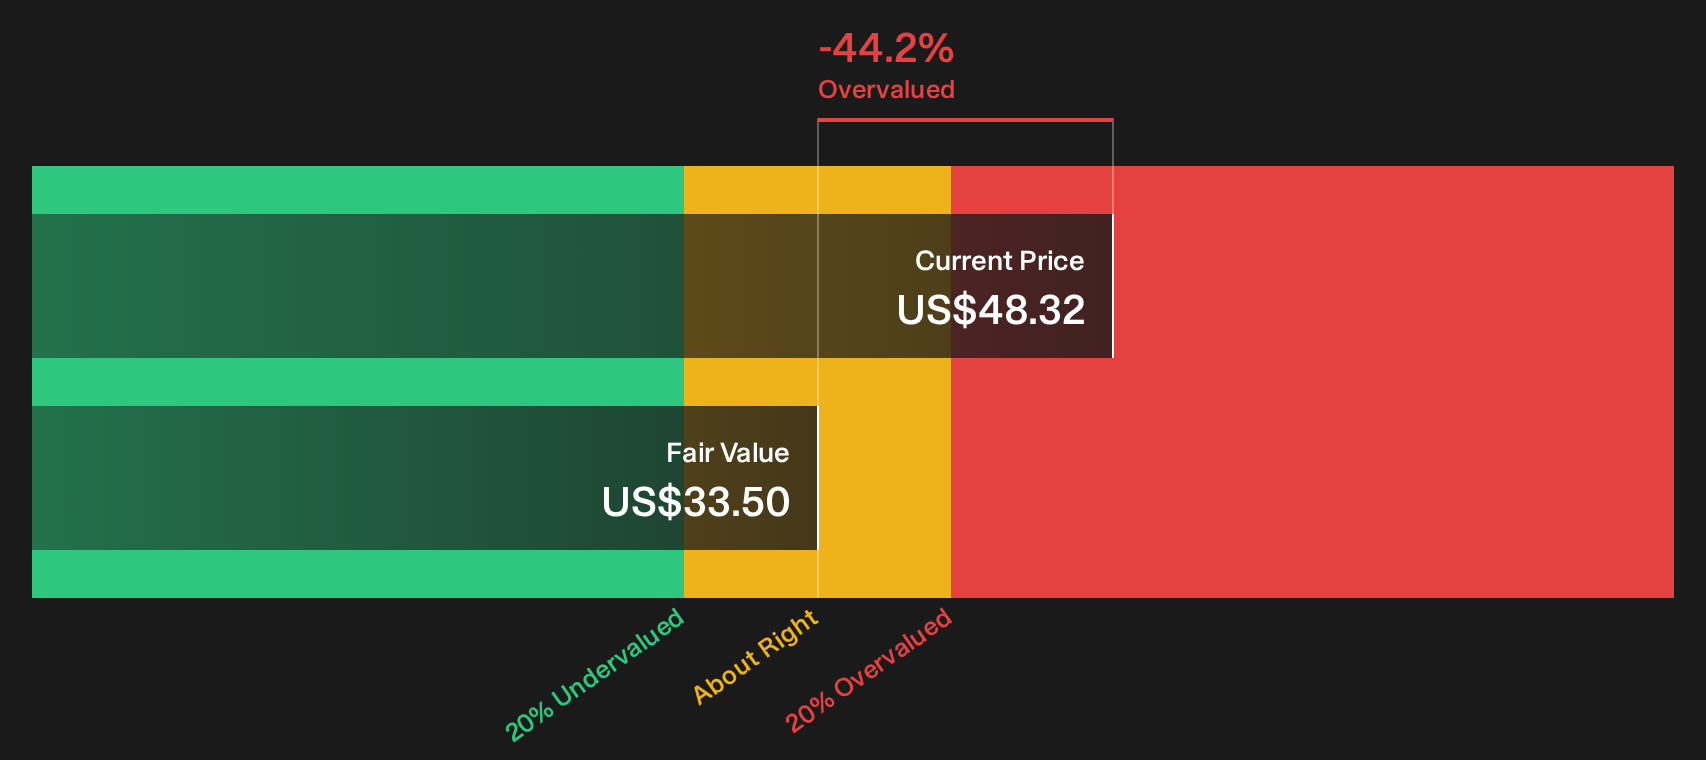
The narrative fair value pegs PACS Group at $62.50 with room for upside, yet the SWS DCF model points the other way. On that cash flow view, PACS trades above an estimated value of $33.50, which implies the stock screens as overvalued rather than cheap. Which lens do you trust more for a long term decision?
For investors who want to see how this cash flow based view is built step by step, it is worth going through our DCF model in detail. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on PACS Group is divided. This is exactly why now is a useful moment to review the numbers yourself, weigh the trade offs, and see how the balance of risks and rewards fits your own approach by checking the 3 key rewards and 1 important warning sign.
Looking for more PACS Group sized investment ideas?
If PACS Group has your attention after this update, do not stop here. Use the same structured thinking to size up other opportunities that might suit your goals.
- Target consistency and sleep better at night by screening for resilient companies through the 29 resilient stocks with low risk scores.
- Hunt for value where quality and pricing still line up by scanning the 34 high quality undervalued stocks.
- Spot opportunities before the crowd catches on by reviewing the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com