
3 Infrastructure Stocks Riding Korean Onshoring Into US Factories And Power Projects
South Korea is pushing toward $1 trillion in annual exports while its trade surplus with the US crosses $100 billion. That combination pulls fresh attention to where factories, power supply, and semiconductor fabs get built next. Rising tariffs and local-content rules do not just hit Korean exporters. They can also redirect capital toward US and EU onshoring. This article walks through three stocks exposed to that trade shock story and explains why their next moves could matter for your portfolio.
The three stocks in focus are only a starting sample of the US and EU Onshoring Beneficiaries from Korean FDI idea, and the full screen surfaced 41 more companies with equally compelling narratives that are not covered here. To identify and analyze potential high-conviction exposure across power, industrials, and chip infrastructure, head straight to the US and EU Onshoring Beneficiaries from Korean FDI screener.
Powell Industries (POWL)
Powell Industries designs custom power distribution and control systems that slot directly into onshored plants and data-heavy facilities, and the bearish analyst Narrative on Simply Wall St frames how that exposure could play out when orders meet real-world project cycles.
"The long term build out of power infrastructure for data centers, AI capacity and Electric Utilities is already feeding through, with Electric Utility revenue up 50% year over year and data center work now making up roughly half of the 15% C&I backlog."
What happens if a single unseen pressure on future project economics quietly shifts how much of that backlog turns into high quality earnings.
If that pressure on future project quality matters to you, read the full narrative for Powell Industries to see how Korean onshoring, data centers, and power grids could be converging.

Tutor Perini (TPC)
Tutor Perini is the kind of heavy contractor that tends to show up when Korean capital funds big U.S. factories, military facilities, and public works, and the bearish analyst Narrative on Simply Wall St sets a useful baseline for how that exposure could translate into results.
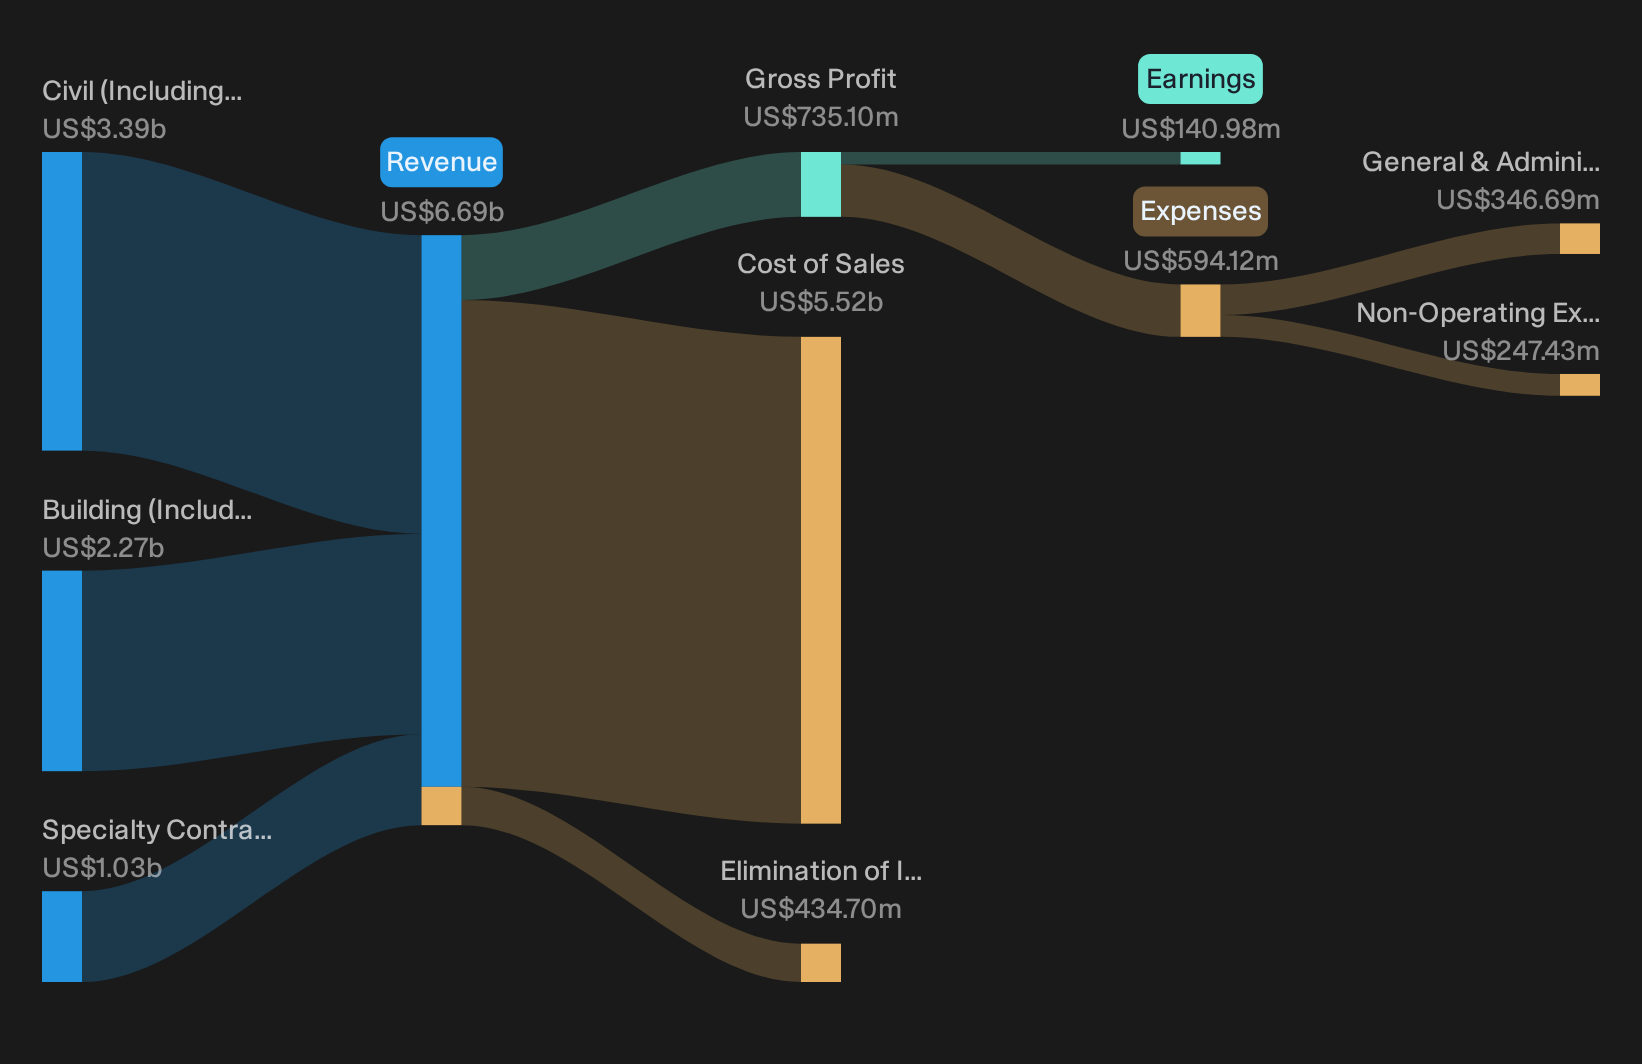
Tutor Perini builds large civil projects, vertical buildings, and specialty systems that line up with onshoring related manufacturing and infrastructure work, generating about US$3.4b from Civil, US$2.3b from Building, and just over US$1.0b from Specialty Contractors. The stock carries a roughly US$5.2b market cap.
"Although Tutor Perini highlights nine large projects totaling about US$16b with better contractual terms and higher expected margins, the July 2026 US$42.4m judgment tied to the W and Element hotels shows that legacy disputes can still absorb cash from this mega project shift and could weigh on net margins and earnings quality as these projects ramp."
The real swing factor is how one unresolved piece of the past ultimately shapes the profitability of all that future factory and infrastructure work.
That swing factor is exactly what the Simply Wall St full narrative for Tutor Perini unpacks, separating temporary legal drag from any accelerating upside Korean backed mega projects might bring.
MasTec (MTZ)
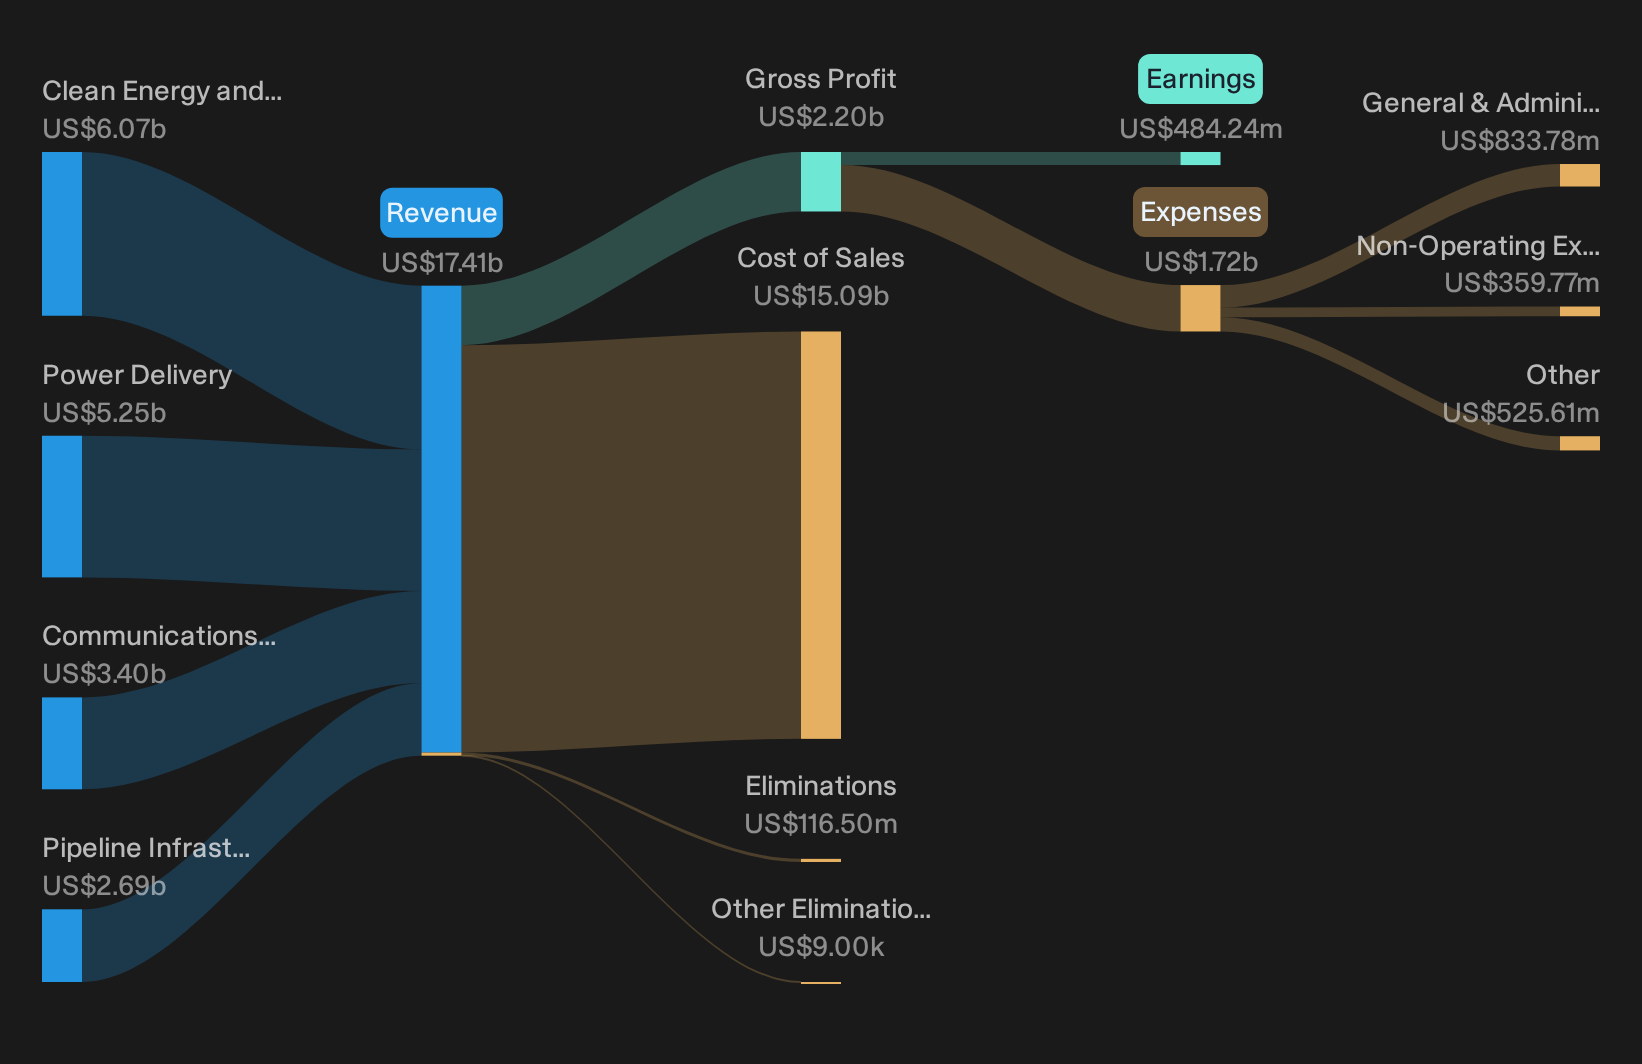
MasTec plugs directly into the US and EU Onshoring Beneficiaries from Korean FDI theme because it handles engineering and construction work for energy, utilities, communications, and industrial infrastructure that Korean backed projects need. The business generated about US$6.1b from Clean Energy and Infrastructure, US$5.2b from Power Delivery, US$3.4b from Communications, and US$2.7b from Pipeline Infrastructure, and the stock carries a roughly US$14.5b market value.
MasTec gives you exposure to where Korean backed capex may actually hit the ground in the US, and the analyst consensus Narrative on Simply Wall St frames that onshoring angle through the contract pipeline already in hand.
"Rapid acceleration in utility grid modernization, data center build outs and renewable energy investment continues to support MasTec’s record backlog of about US$21.4b and raised 2026 guidance."
What happens if one unseen pressure on future project margins changes how much of that record backlog turns into high quality earnings?
That pressure point is exactly where the Simply Wall St full narrative for MasTec steps in, highlighting how MasTec’s backlog, margins, and Korean backed projects could be decoupling from headline expectations.
Seeking Fresh Alternatives Before They Fly
Fresh breakout ideas can attract attention quickly. Once momentum builds, attractive entry points may become scarce. Look under the radar now and consider moving before the crowd.
- Target resilient cash generators by scanning a curated list of solid balance sheet and fundamentals (24 results) that focuses on businesses designed to hold up when weaker peers start to struggle.
- Hunt for accelerating trends with the hand picked 53 AI infrastructure stocks that tracks the picks and shovels behind data centers, semiconductors, and high intensity computing build outs.
- Zero in on potential compounding candidates through a filtered 19 high quality undiscovered gems focused on quality fundamentals before wider attention influences valuations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com