
Brinker International (EAT) Could Be 24% Undervalued After Earnings Beat Estimates
Brinker International (EAT) is back in focus after revenue and earnings surpassed consensus estimates, alongside upward revisions to near term profit forecasts and a share price that still trades at a discount to peers.
The share price tells a mixed story. Brinker International’s 1-day share price return of 0.36% comes after the stock fell 17.95% over 90 days. It still posts a 30.89% year to date share price gain and a 1-year total shareholder return of 75.22%, with very large 3 and 5 year total shareholder returns that suggest long term momentum, while shorter term moves hint at some cooling enthusiasm after a strong run.
Scan other restaurant and consumer names trading on similar storylines by checking our hand picked 34 high quality undervalued stocks alongside Brinker International’s recent estimate beats and peer discount.
After a 1-year total return of 75.22% and very large multi year gains, along with a recent 17.95% pullback and a stated discount to peers, does Brinker International still offer an appealing trade off between risk and reward?
Most Popular Narrative: 24% Undervalued
Brinker International’s fair value in the analyst consensus Narrative on Simply Wall St sits at $262.59, compared with a last close of $198.33. This frames a sizable gap that the narrative ties to Chili’s operating model and growth plans.
Planned Chili's unit growth of 20 to 30 new locations per year by fiscal 2029, together with a program to reimage roughly 10% of the system annually where early remodels are tied to 3% to 5% sales lifts and targeted $5 million to $6 million AUVs in new builds, can add a new layer of volume driven revenue growth and contribute to operating leverage.
See why 33 investors see Brinker International as 24% undervalued.
Result: Fair Value of $262.59 (UNDERVALUED)
Still, the Brinker International narrative leans heavily on Chili’s to go growth and value pricing working as planned, while Maggiano’s weaker traffic trends remain a drag risk.
Find out about the key risks to this Brinker International narrative.
Another View: Brinker International Through A Cash Flow Lens
Analysts on Simply Wall St see Brinker International as undervalued using their narrative fair value of $262.59, but the SWS DCF model tells a cooler story. On that cash flow view, EAT at $198.33 trades above an estimated value of $182.18, which points to a premium rather than a discount. That gap invites a simple question for investors: which set of assumptions feels more realistic for the next few years?
Look into how the SWS DCF model arrives at its fair value.
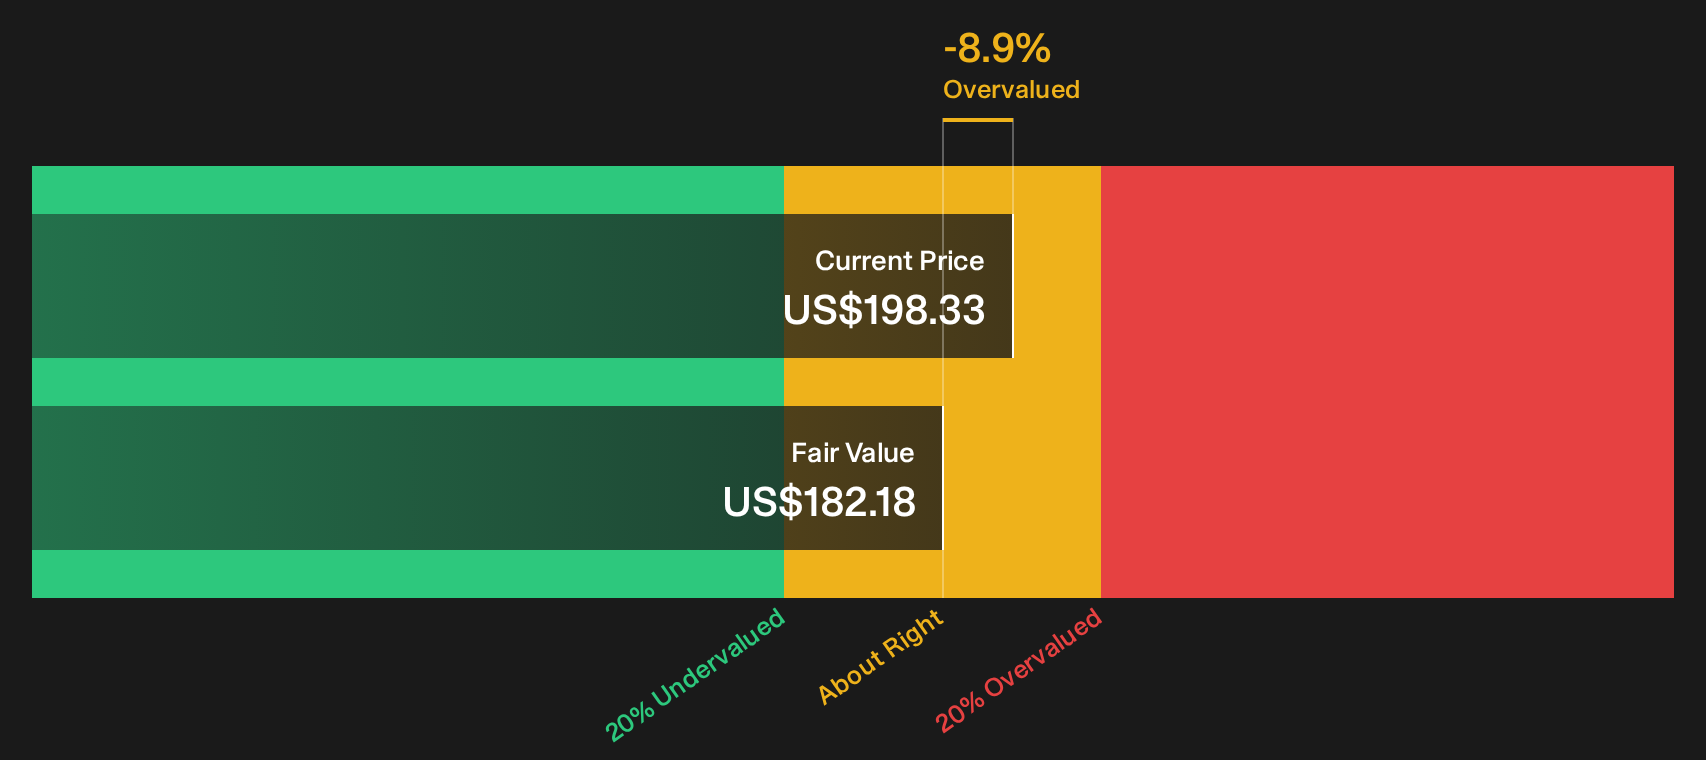
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brinker International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Brinker International is split, which is exactly when doing your own homework matters most and when speed actually helps. Take a fresh look at the numbers, weigh the risk signals against the upside drivers, and ground your decision in the 5 key rewards and 2 important warning signs.
Looking for more Brinker International style investment ideas?
If Brinker International has sharpened your focus, do not stop here. Broaden your watchlist with a few targeted screens that surface very different types of opportunities.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (24 results) that filters for companies combining financial strength with underlying business quality.
- Hunt for potential bargains using a 34 high quality undervalued stocks that highlights stocks where quality and current pricing look misaligned.
- Stack your income options through a 6 dividend fortresses that focuses on companies offering higher yields with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com