
What Precigen (PGEN)'s Profit Turn Means For Shareholders
- Precigen reported third quarter 2026 revenue of US$74.15 million and net income of US$35.77 million, compared with much lower revenue and a sizeable loss in the same period a year earlier.
- The nine month figures to September 30, 2026 showed a shift from a loss to a profit, indicating a significant change in Precigen's operating performance and cost structure.
- We will now look at how Precigen's move from quarterly loss to profit could influence the investment narrative around PAPZIMEOS.
See how Precigen's earnings swing compares to peers by reviewing a curated set of 19 high quality undiscovered gems that the market may not be fully focused on yet.
Precigen Investment Narrative Recap
To own Precigen, you need to believe PAPZIMEOS can sustain meaningful, real world use in recurrent respiratory papillomatosis and that the current commercial buildout eventually earns its keep. The swing to a US$35.77 million quarterly profit helps that story but does not remove execution risk around payer processes, physician adoption, and manufacturing scale up.
The analyst consensus Narrative on Simply Wall St leans on a transition to stronger earnings and cash flow, and the latest results support that direction without settling the debate. The biggest near term catalyst still sits with continued PAPZIMEOS uptake and reimbursement consistency. The main risk remains slower than expected patient pull through, which could leave fixed costs heavy.
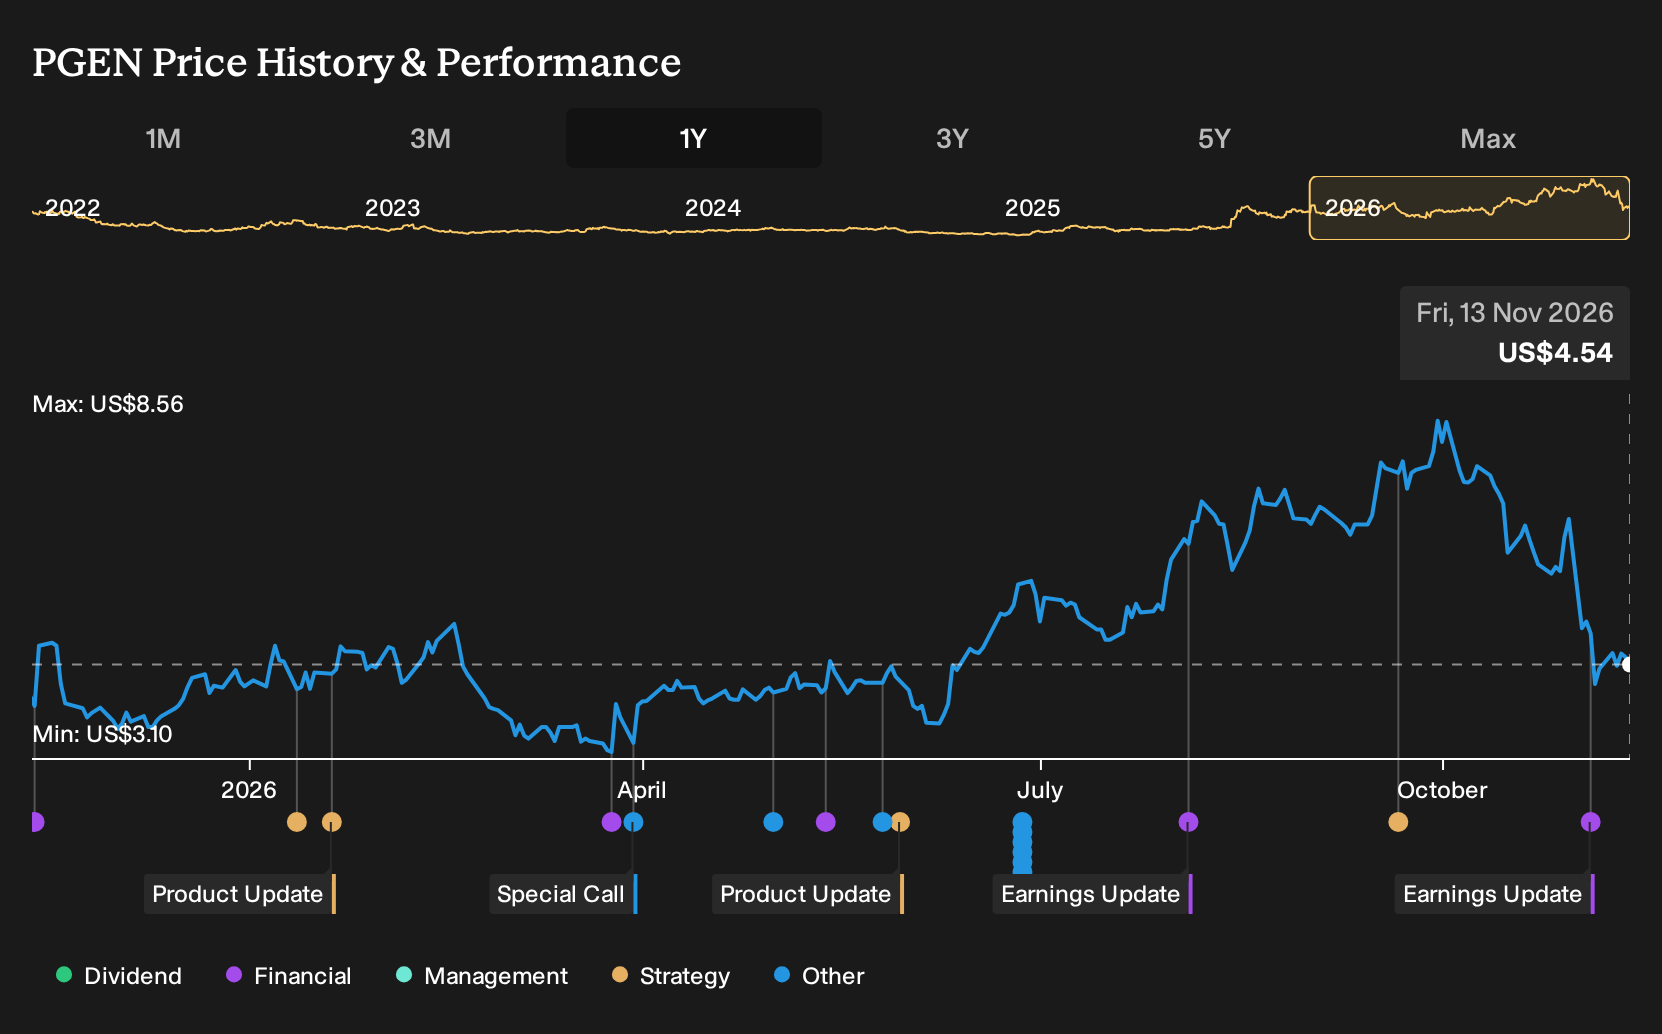
The most relevant development here is Precigen’s move from a sizeable loss a year ago to US$47.91 million in net income over the first nine months of 2026. This shift lines up with the earlier idea that PAPZIMEOS could move the group toward breakeven using its own cash generation rather than repeated capital raises.
In terms of catalysts, that profit profile gives management more room to execute on pediatric RRP and EMA expansion plans highlighted in the analyst consensus Narrative on Simply Wall St. Investors still need to watch how much of this income is cash based versus non cash, how debt coverage evolves, and whether payer discounts squeeze margins as volumes build.
Precigen's current analyst narrative points to forecast revenue of US$654.3 million and earnings of US$393.8 million by 2029. That scenario implies revenue growing at 96.9% per year and an earnings swing of about US$730.5 million from a loss of US$336.7 million today to the 2029 consensus figure.
Uncover why Precigen's fair value indicates a 201% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Precigen puts reimbursement risk at the center. The most cautious analysts were pencilling in revenue of about US$480.3 million and earnings of roughly US$454.5 million by 2029 before this latest profit swing. That camp expects tighter payer terms, so you see how opinions can differ sharply.
Explore 2 other Precigen fair value estimates, including one that suggests it could be worth just $13.65!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Precigen research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Precigen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Precigen's overall financial health at a glance.
Looking For More Investment Ideas Beyond Precigen?
If this Precigen update has sharpened your view on risk, reward, and timing, it can help to line it up against a broader watchlist. Use the Simply Wall St Screener to compare this story with other opportunities that match your preferred style of investing.
- If you are hunting for companies the market may be overlooking, start with a 19 high quality undiscovered gems that already clear basic quality and fundamentals checks.
- For readers who care most about resilient balance sheets and fewer financial surprises, filter for a list of solid balance sheet and fundamentals (24 results) to see which businesses might better match a capital preservation mindset.
- When income is a priority, focus your research on a 6 dividend fortresses that combine higher yields with the potential for more durable payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com