
How Investors May Respond To Micron (MU) AI Memory Supply Commitments
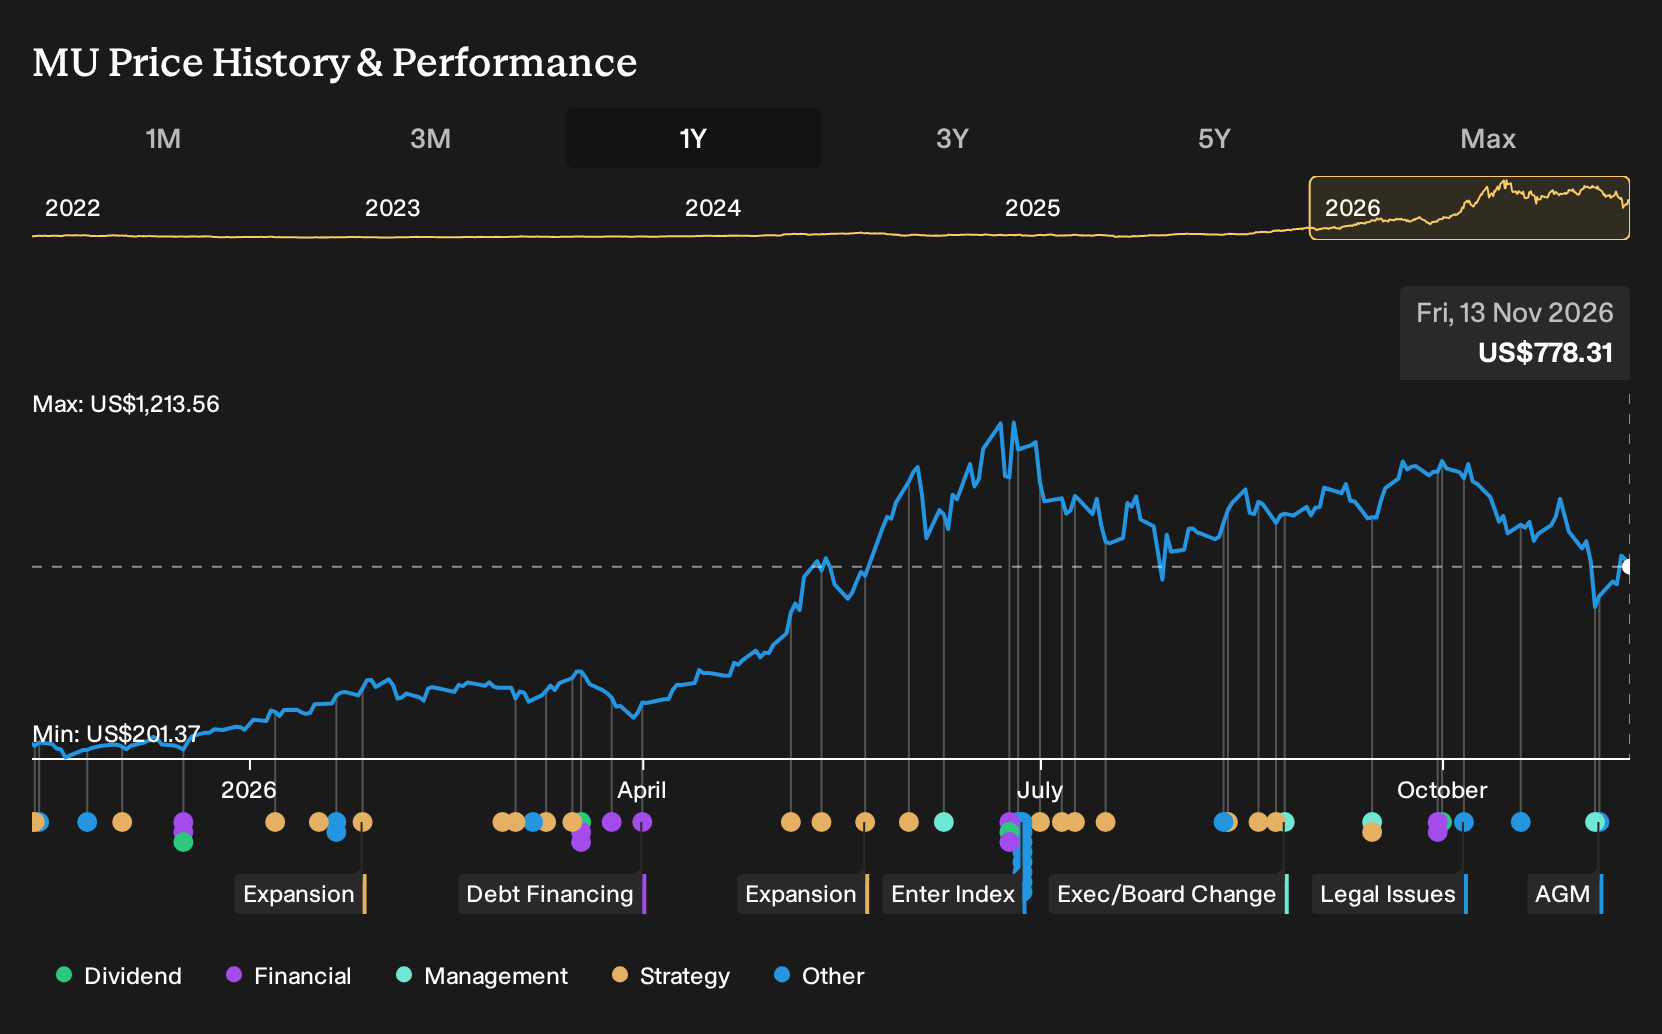
- Micron Technology announced that director Linnie M. Haynesworth will retire from the board after the January 14, 2027 annual shareholders meeting. This change will reduce the board to eight members and adjust committee composition across audit, compensation, security, and governance functions.
- Haynesworth’s exit comes as Micron’s memory output is heavily committed under long-term AI-related contracts, highlighting how board oversight is evolving while the business focuses on capital intensive, supply constrained data center demand.
- We will now look at how Micron’s investment narrative is shaped by this board transition alongside tight AI driven high bandwidth memory commitments.
Scan how board decisions and AI memory constraints are playing out across the sector by reviewing the hand picked 53 AI infrastructure stocks.
Micron Technology Investment Narrative Recap
To own Micron Technology, you need to believe AI data center spending keeps memory economically important enough for tight supply and long-term contracts to matter. According to HedgeY, an investor in the Simply Wall St Community, the key worry is peak earnings risk, because unusually high gross margins can reset quickly if pricing softens.
Haynesworth’s planned retirement looks more like normal board evolution than a change to Micron’s day to day execution. The biggest near term swing factor still sits with AI related memory demand and any shift in customer ordering, while large capex plans and China competition remain central risks rather than new ones.
The Anthropic private placement and HBM supply deal is the clearest operational tie in to this board update. Investors get a picture of Micron committing capital and product into a multi year AI rollout, with governance refresh continuing in the background as Haynesworth steps off committees that touch security, audit, and compensation.
HedgeY argues the long term contracts like Anthropic’s help reduce classic memory volatility, although a large portion of DRAM and NAND is still exposed to spot pricing. That mix keeps the Anthropic agreement relevant as a catalyst for cash flow visibility, while leaving peak earnings, heavy capex, and customer concentration as ongoing execution tests.
HedgeY’s fair value narrative for Micron Technology at $1,250 rests on a model that assumes revenue grows 19.5% a year and eventually supports a future profit margin of 55.9%. Together, these assumptions are used to justify paying a higher multiple on current supercycle earnings power.
Uncover how Micron Technology's fair value indicates a 61% potential upside to its current price, before enthusiasm around AI memory demand narrows that gap.
Exploring Other Perspectives
Some of the lowest Micron Technology analysts focus on a different risk than the board transition or peak earnings. They worry that huge fab projects could drag returns if demand cools, even though their pre news models still used roughly US$236.3b of revenue and US$207.2b of earnings by 2029. That is a far more skeptical narrative than the baseline, and it may shift again once this board change is fully reflected in fresh forecasts.
Explore 30 other Micron Technology fair value estimates, including one that suggests as much as 29% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Micron Technology research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Micron Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Micron Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Micron Technology?
Once you understand where Micron Technology fits in your portfolio, it helps to line it up against other opportunities that match your risk appetite, income needs, and balance sheet preferences. The Simply Wall St screener lets you filter for exactly that, without having to build spreadsheets from scratch.
- If you want potential growth with smaller market values and are comfortable with higher risk, scan a focused group of 13 elite penny stocks with strong financials that meet specific financial quality filters.
- For readers who care most about paying a reasonable price for solid fundamentals, narrow the field to a 34 high quality undervalued stocks that combines earnings strength with balance sheet support.
- If your priority is resilience and capital protection, concentrate on a 29 resilient stocks with low risk scores that screens for companies with sturdier financial profiles and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com