
Did Raised Revenue Guidance Just Shift WillScot Holdings' (WSC) Investment Narrative?
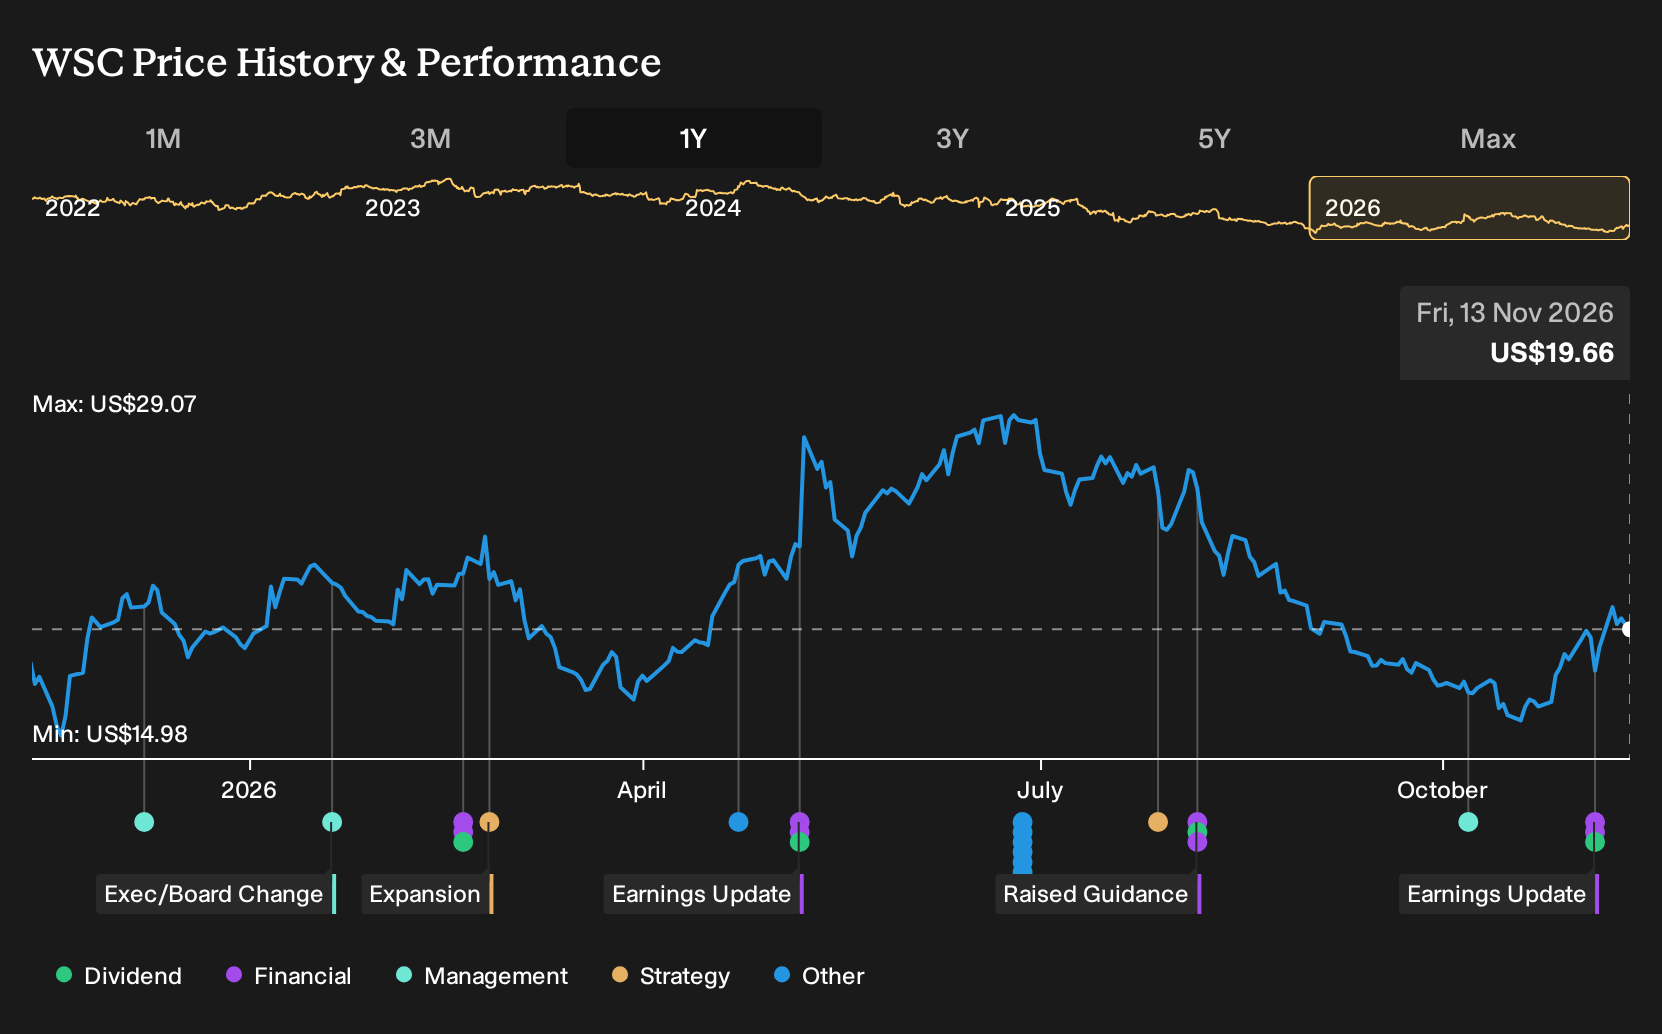
- WillScot Holdings reported third quarter 2026 sales of US$451.7 million and revenue of US$601.34 million, with net income of US$51.58 million and diluted EPS from continuing operations of US$0.28. The company also affirmed a quarterly dividend of US$0.07 per share payable in December 2026.
- The nine-month figures showed revenue of US$1.76b and net income of US$126.67 million, while management raised full year 2026 revenue guidance to US$2.34b. This heightens attention on how effectively WillScot Holdings converts its modular backlog and network optimization efforts into higher margin leasing activity.
- The next step is to consider how WillScot Holdings' higher quarterly earnings and raised 2026 revenue outlook may influence its investment narrative.
Scan how WillScot Holdings’ latest earnings and dividend update compares to other balance-sheet-focused opportunities by reviewing our curated list of solid balance sheet and fundamentals (24 results).
WillScot Holdings Investment Narrative Recap
Owning WillScot Holdings means believing the modular leasing engine and value added services can offset pressure in portable storage and past earnings volatility flagged in the analyst consensus Narrative on Simply Wall St. The latest quarter shows higher quarterly revenue and earnings, which supports that modular focus but does not erase earlier concerns about profitability and financial strength.
The key short term swing factor is whether activation and transfer costs ease and network optimization starts to lift margins. The biggest risk remains that portable storage softness and elevated costs keep EBITDA margins compressed, which would make it harder for WillScot Holdings to translate its project pipeline into cleaner earnings.
The raised 2026 revenue guidance to US$2.34b is the clearest operational signal in this update. Management is effectively saying the current order book and utilization support a higher top line view, even as nine month net income is lower than the prior year, despite slightly higher sales and revenue.
For you as an investor, the question is whether that higher revenue outlook can flow through to better profitability while interest coverage and dividend sustainability risks are still present. If execution on network optimization, modular refurbishments and enterprise accounts lags, the updated guidance could increase scrutiny on how efficiently WillScot Holdings converts growth spending into durable cash generation.
WillScot Holdings' narrative projects US$2.5b revenue and US$406.1 million earnings by 2029. This lines up with analysts assuming 2.4% yearly revenue growth and an earnings swing of about US$466.7 million, from current earnings of a US$60.6 million loss to the US$406.1 million forecast profit.
Uncover how WillScot Holdings' fair value indicates a 27% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
One alternate view on WillScot Holdings leans hard into the network optimization catalyst. The most optimistic analysts were already modeling revenue at about US$2.6b and earnings of roughly US$388.8 million by 2029. Those forecasts came before this latest guidance and dividend update, so you may see their story evolve in very different ways from consensus.
Explore another WillScot Holdings fair value estimate, including one that indicates up to 30% potential increase from the current price.
Decide For Yourself
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your WillScot Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for WillScot Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WillScot Holdings' overall financial health at a glance.
Looking For More WillScot Holdings Investment Ideas?
If WillScot Holdings has sharpened your focus on balance sheets, cash generation and dividends, you can widen your watchlist by scanning other stocks through the Simply Wall St Screener. Pick a starting point that matches how you like to invest and let the data surface candidates that fit your style.
- For potential value opportunities backed by stronger fundamentals, review a carefully filtered set of 34 high quality undervalued stocks that might merit a closer look.
- If resilience and capital preservation matter most to you, sort through a curated group of 29 resilient stocks with low risk scores that screen well on financial risk metrics.
- When you want ideas that are still off most investors' radar, scan a focused pool of 19 high quality undiscovered gems with solid underlying data.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com