
Is Earnings And Guidance Reaffirmed Altering The Investment Case For ADMA Biologics (ADMA)?
- ADMA Biologics reported third quarter 2026 sales of US$141.1 million and net income of US$49.88 million, while reaffirming at least US$530 million in full year 2026 revenue guidance.
- The combination of higher earnings per share and management’s confidence in the 2026 outlook provides investors with new information on ADMA Biologics’ operating leverage and demand resilience across its plasma derived portfolio.
- We will now look at how ADMA Biologics’ reiterated 2026 revenue guidance could influence the broader investment narrative around the business.
ADMA Biologics Investment Narrative Recap
To own ADMA Biologics, you need to believe that its plasma derived portfolio can keep generating healthy earnings from largely fixed manufacturing assets, even as the standard immunoglobulin market gets more crowded. The reiterated 2026 revenue guide of at least US$530 million suggests that management sees enough demand visibility to support that view.
The near term catalyst still depends on execution in driving higher margin ASCENIV volumes and maintaining gross margins that the analyst consensus Narrative on Simply Wall St links to the FDA approved yield enhancement process. The biggest risk remains product concentration and competitive pressure on therapies like BIVIGAM, which could strain pricing and compress profitability if conditions worsen.
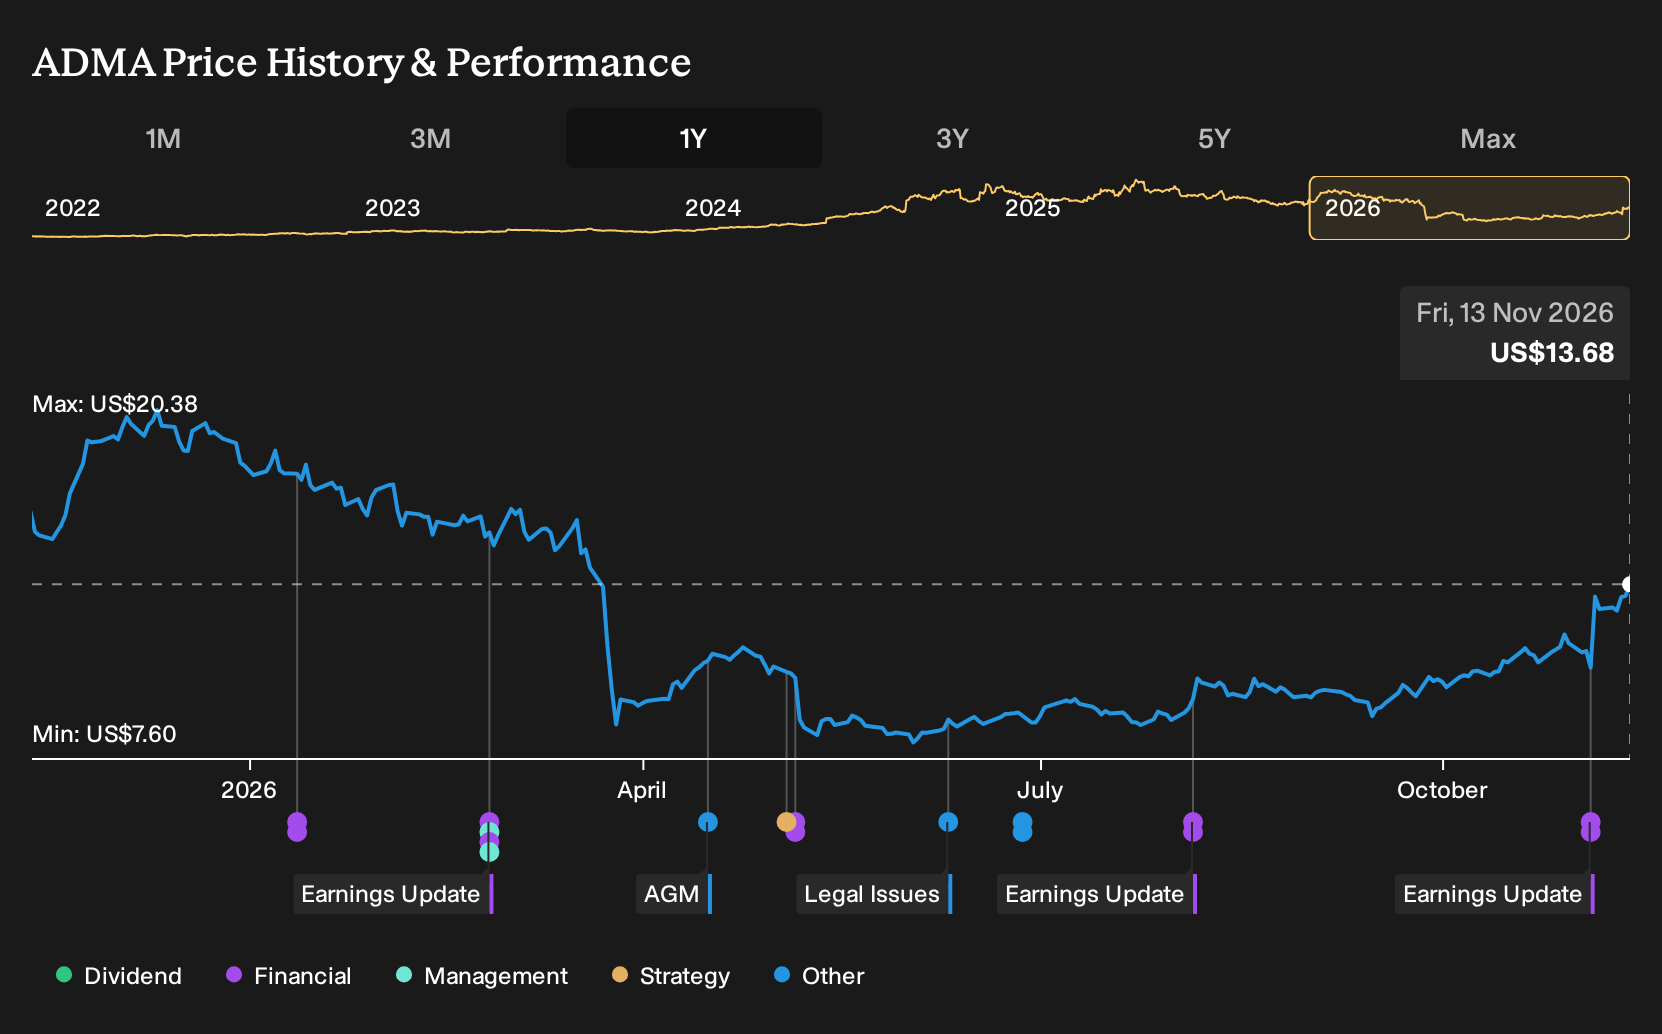
The most relevant update for that thesis is the third quarter 2026 report, which showed US$141.1 million in sales and US$49.88 million in net income, with basic and diluted EPS from continuing operations at US$0.22. Those figures, alongside nine month revenue of US$379.99 million and net income of US$133.03 million, provide a current snapshot of how the model is performing.
In light of the earlier cuts to guidance referenced in the analyst consensus Narrative on Simply Wall St, this latest quarter frames the near term debate around consistency. Investors now weigh ongoing ASCENIV adoption, gross margin support from the yield enhancement process and progress on SG 001 against concentrated products, lawsuits tied to ASCENIV distribution and any renewed pressure on immunoglobulin pricing or ordering patterns.
ADMA Biologics' narrative projects US$769.2 million in revenue and US$293.5 million in earnings by 2029, based on analysts' models. This implies 14.0% yearly revenue growth and an earnings increase of about US$111.1 million from the current US$182.4 million level.
Uncover why ADMA Biologics' fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on ADMA Biologics leans heavily on the share repurchase program as the real catalyst. The most optimistic analysts were penciling in US$893.6 million of 2029 revenue and US$345.1 million of earnings before this latest quarter and guidance update. Your own read may shift if buybacks and earnings now look different in combination.
Explore 6 other ADMA Biologics fair value estimates, including one that suggests potential upside of as much as 193% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ADMA Biologics research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ADMA Biologics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ADMA Biologics' overall financial health at a glance.
Looking for more investment ideas beyond ADMA Biologics?
Once you have a view on ADMA Biologics, it can help to widen the lens and see how other businesses line up on quality, balance sheet strength, income potential and perceived mispricing. The Simply Wall St Screener lets you filter for these traits quickly so you can spend more time weighing the story behind each ticker.
- If you want potential upside with a margin of safety, start by scanning a focused set of 34 high quality undervalued stocks that combine compressed valuations with solid underlying fundamentals.
- For investors who care most about resilience, narrow the field to a 29 resilient stocks with low risk scores that screens for stronger balance sheets and more durable business profiles.
- If income is the priority, concentrate your search on a curated 6 dividend fortresses that pairs higher yields with an eye on sustainability rather than chasing payouts blindly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com