
What Planet Labs PBC Holders Bought Into
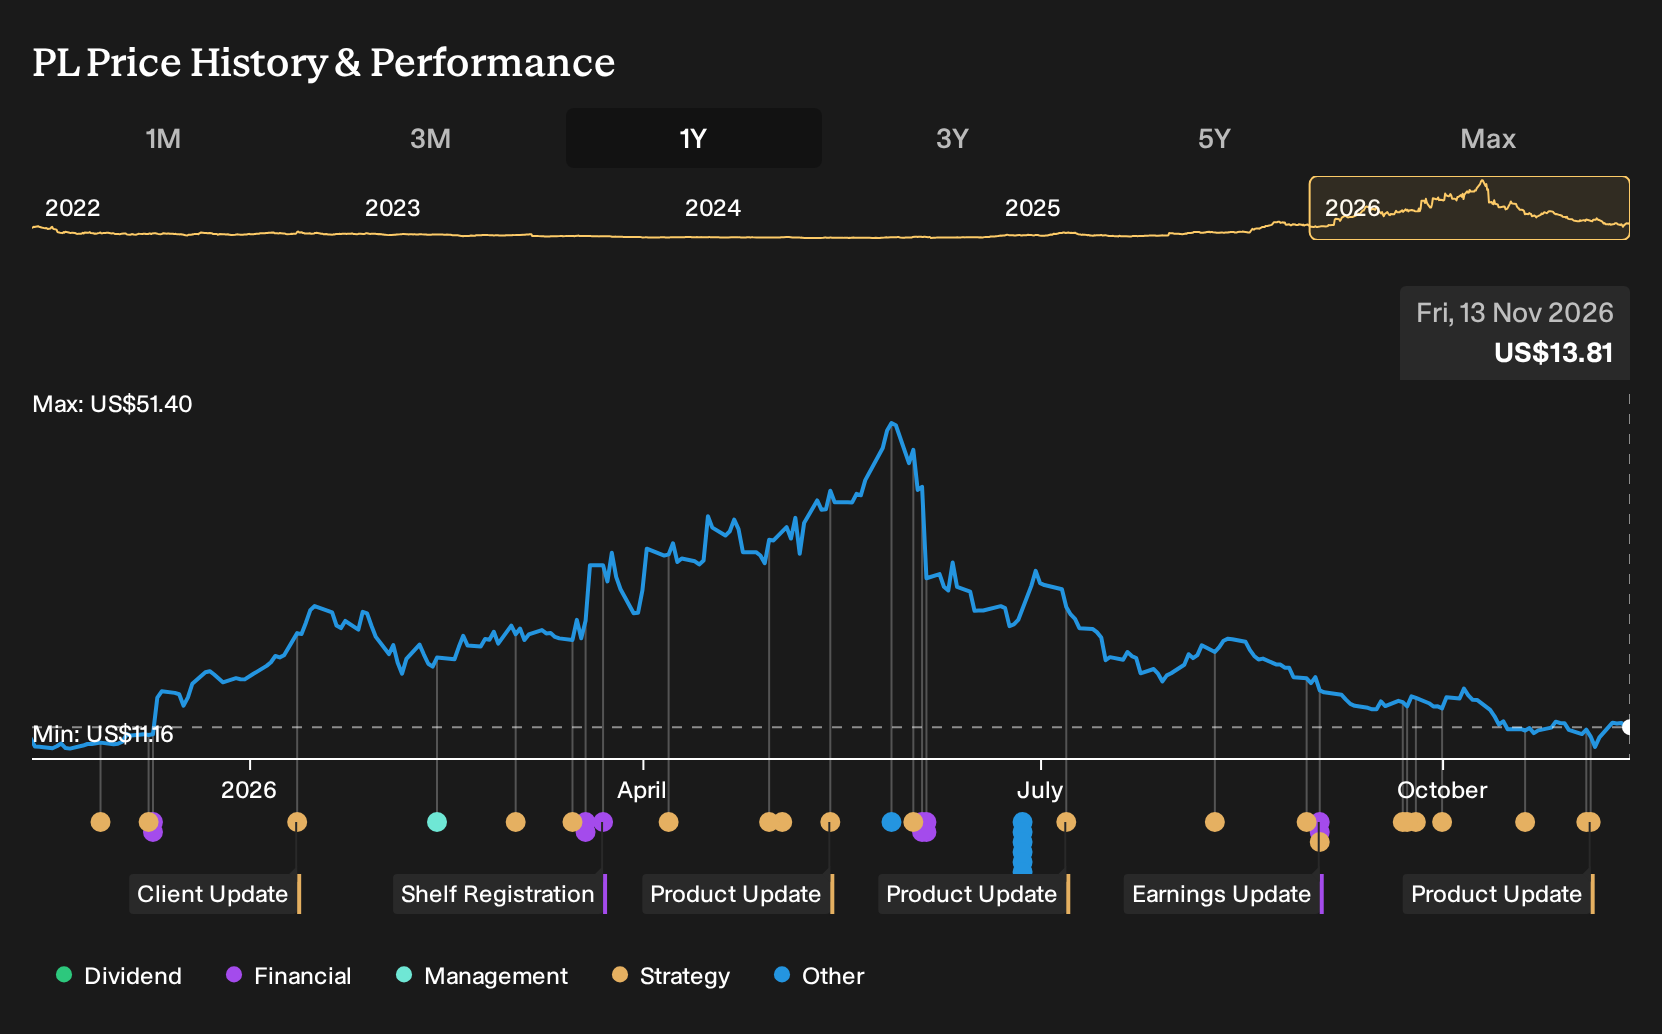
If Planet Labs PBC was on your watchlist rather than in your portfolio, the return may sting. Holding Planet Labs PBC over the past year would have returned 21.1%, including dividends. The move came as the business reported record revenue, a fast growing backlog and more sovereign satellite services contracts, while still wrestling with ongoing losses and capital needs. If you were staring at those government heavy contracts back in November 2025, what would have signalled that geospatial analytics and upgraded satellites might justify the risk?
Planet Labs PBC has already moved. Pinpoint other ways to investigate the theme among 53 AI infrastructure stocks.
What Expectations Were Really Being Priced Into Planet Labs?
The shares cost US$11.41 at the start of the period. Any view on Planet Labs PBC therefore began with whether that level already reflected ambitious growth in geospatial data and satellite services.
The bullish story implied a Fair Value of US$12. This was a rough guide to what that camp thought the stock could be worth if its thesis played out, built on 21.8% assumed annual revenue growth and profit margins eventually reaching 7.1%.
The more cautious narrative pointed to a Fair Value of US$9.23, with 18.7% assumed annual revenue growth and concern that capital intensive satellite launches and customer concentration could still pressure future cash flows.
What The Results Changed For The Planet Labs Thesis
Planet Labs PBC reported Q2 2027 revenue of US$116.1 million, up from US$73.4 million a year earlier, which backed the bullish focus on demand and backlog. The loss narrowed, with net income excluding extra items improving from a loss of US$22.6 million to a loss of US$9.4 million and net margin moving from 30.8% negative to 8.1% negative, so profitability remained unproven. Overall, the evidence cut both ways.
The key assumption here was that rising geospatial demand would eventually translate into positive margins. For any similar stock, track whether revenue growth comes with a clearly improving but still negative net margin or has actually crossed into sustained profit on reported earnings.
What Planet Labs' Price Now Asks You To Believe
Planet Labs PBC now trades at US$13.81. According to DanielOliveira, an investor in the Simply Wall St Community who wrote the current Narrative, that view puts Fair Value below the market price, so the stock already bakes in a lot of execution confidence.
The Narrative highlights backlog, over time revenue and satellite handovers around the next few quarters. The key assumption a buyer at today’s level must weigh is that contract burn, new deals and timing of satellite acceptances together keep reported revenue and losses tracking management’s guidance.
"Over-time revenue grew $9.7 million from Q1 to Q2 and about 40% from a year earlier. About half of the $814.9 million backlog is due in the next twelve months, roughly $102 million a quarter from signed contracts before any usage, renewals or new wins."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
One More Way To Read The Map
Planet Labs turns raw imagery into decisions. Your watchlist does not need to stop there.
The same customers wrestling with satellite data often face dense legal, research and risk questions too. That brings a different kind of complexity problem.
Another business focuses on those information headaches. It builds data tools that help professionals judge risk, interpret research and manage regulations with AI support.
Think of it as tackling the paperwork side of the same urge to measure the world more precisely.
If geospatial demand matters to you, that neighbour in information analytics might be worth a closer look.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 58% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com