
Coherent (COHR) Could Be 44% Undervalued Following Its $20b AI Deal
Coherent (COHR) grabbed investor attention after reporting a strong September quarter, raising its long term gross margin target, and securing a US$20b multi year AI datacenter supply agreement.
The share price reaction has been choppy, with Coherent falling 6.0% on the day to US$218.15 after the news, yet still up 13.1% over the past week and 12.3% year to date. Total shareholder return over one and five years has been very strong, pointing to powerful long term momentum even as short term expectations reset after a big run.
Spot opportunities related to the same AI datacenter theme as Coherent by scanning our hand picked 53 AI infrastructure stocks, which are tied to this surge in optical and compute build outs.
After a record quarter, a higher gross margin target, and that US$20b AI contract, Coherent now trades at a richer multiple and faces significantly higher expectations. Does the potential payoff still justify the price you are paying today?
Most Popular Narrative: 44% Undervalued
On the analyst consensus Narrative on Simply Wall St, Coherent screens as undervalued, with a fair value of about $387.80 against a last close of $218.15. That view leans heavily on how AI datacenter demand and manufacturing investments could reshape the profit profile.
The ongoing expansion of AI datacenter infrastructure and high-performance computing is propelling structural growth in demand for advanced optical transceivers (800G, 1.6T, and beyond), optical circuit switches, and related photonics components, which is fueling robust sequential order growth and sustained revenue momentum in Coherent's datacom and communications business.
See why 141 investors see Coherent as 44% undervalued.
The same Narrative applies an 8.9% discount rate to those long range cash flows, which is a relatively standard hurdle for a large, profitable US tech hardware supplier. It also leans on forecast revenue expansion of 39.4% a year and profit margins moving from 10.8% to 18.5%, which is described as a substantial shift in earnings power if it plays out.
Analysts in that framework are modeling earnings to reach $3.6b by about November 2029, with earnings per share of $17.26 and a future P/E of 33.7x. That multiple is higher than the 28.7x applied to the broader US Electronic industry in the Narrative, which means the fair value case assumes Coherent continues to justify a premium based on its AI exposure and margin mix.
Forecasts in the same data set also call for earnings growth of 32.3% per year and revenue growth of 25.4% per year, both quicker than the wider US market expectations cited there. For an investor, the key question is whether that growth path and margin improvement look realistic when set against risks like heavy capital spending, customer concentration, competition in transceivers, and share dilution of 7.0% a year that the Narrative also flags.
Compared with that fair value of roughly $387.80, the current market value implies a discount of about 44%, even after a total shareholder return of 56.6% over the past year. The share price is therefore embedding lower expectations than the analyst consensus Narrative. This leaves room for different views on whether the AI contracts and manufacturing build out fully offset competition, funding mix, and earnings quality concerns.
Result: Fair Value of $387.80 (UNDERVALUED)
Still, the Coherent narrative could be knocked off course if heavy capital spending drags on returns, or if customer concentration leads to sharp order swings.
Find out about the key risks to this Coherent narrative.
Another View: What Coherent's P/E Says
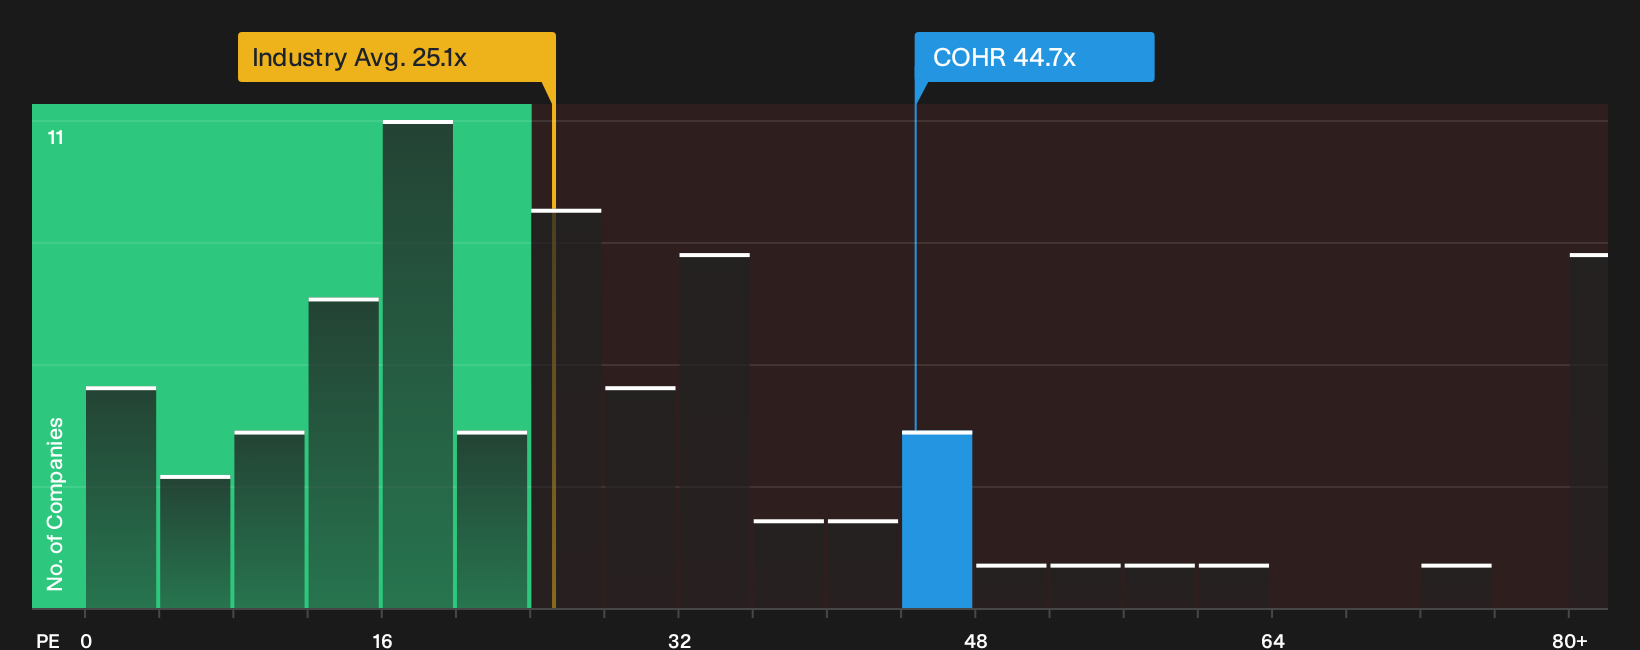
The first narrative leans on long range cash flows, yet the current share price of $218.15 also reflects a rich P/E of 44.7x. That is higher than both the US electronic industry at 25.1x and the peer average at 35.9x, and sits almost exactly in line with a fair ratio of 44.8x.
From this perspective, Coherent appears closer to fairly valued than cheap, which means a lot already rides on those AI contracts, margin targets, and execution. If earnings or sentiment shift, it remains to be seen whether the market moves the P/E toward the industry, the peers, or that fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions are mixed about whether Coherent’s recent surge and rich P/E are justified. Rather than waiting for consensus to form, weigh the enthusiasm against the concerns by checking the 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond Coherent?
Do not stop at Coherent. Broaden your watchlist now with a few focused stock lists that match different risk levels, income needs, and value angles.
- Target long term compounding potential by reviewing quality businesses that appear mispriced in the market through the 34 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by scanning companies with healthier finances using the list of solid balance sheet and fundamentals (24 results).
- Boost your income focus by checking out higher yielding opportunities through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com