
Is Kawasaki Kisen Kaisha (TSE:9107) Fully Valued After New Earnings Targets And Dividend Confirmation?
Kawasaki Kisen Kaisha (TSE:9107) has just laid out fresh earnings targets through fiscal 2027 and into 2031, while reaffirming a JPY 60 second quarter dividend, giving shareholders clearer income and profit expectations.
The fresh guidance and dividend confirmation come after a strong run, with the share price at ¥3,125 and a year-to-date share price return of 43.51%. The 1-year total shareholder return of 54.17% and 5-year total shareholder return of about 7x together indicate that momentum has largely been building rather than fading.
Scan how Kawasaki Kisen Kaisha compares with other transport and infrastructure plays that show strong balance sheets and cash generation using our curated list of solid balance sheet and fundamentals (24 results).
Kawasaki Kisen Kaisha has surged on fresh guidance and a confirmed dividend, which leaves a simple fork in the road: step in after this run, or wait and hope the valuation gives you another shot.
Most Popular Narrative: 3% Overvalued
The analyst consensus Narrative on Simply Wall St pegs Kawasaki Kisen Kaisha's fair value at about ¥3,029, slightly below the last close of ¥3,125. This frames the latest guidance against a valuation that already bakes in its current earnings profile.
Continued exposure to cyclical dry bulk and container shipping, alongside management guidance for materially lower operating income and net income in FY2025 compared with FY2024, points to an extended period of earnings pressure that can justify a restrained valuation multiple.
See why 2 investors see Kawasaki Kisen Kaisha as 3% overvalued.
Result: Fair Value of ¥3,029 (OVERVALUED)
Still, this script can flip if freight markets stay weak for longer than analysts expect or if energy resource contracts stop cushioning the more volatile segments.
Find out about the key risks to this Kawasaki Kisen Kaisha narrative.
Another View: What Kawasaki Kisen Kaisha’s P/E Is Really Saying
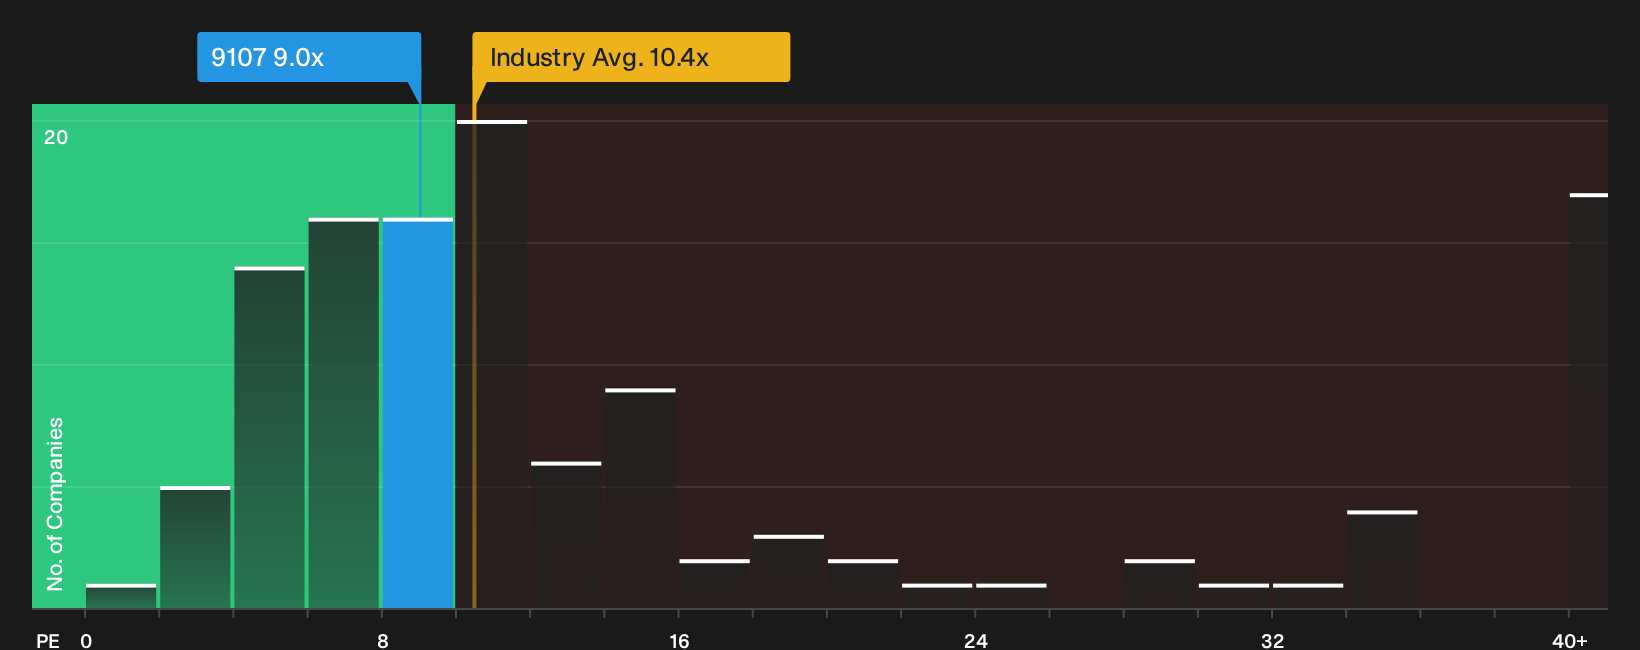
Analysts on Simply Wall St see Kawasaki Kisen Kaisha as about 3% overvalued on a fair value of ¥3,029. Yet the share trades on a P/E of 9x, which looks cheaper than the Asian Shipping industry at 10.7x and below a fair ratio of 12.2x that the market could move toward.
Peer comparisons tell a slightly different story. The stock is a touch expensive versus a peer average P/E of 8.8x, which hints that investors may already be paying a small premium and leaves less room for mistakes if earnings keep shrinking.
Two valuation signals pointing in different directions force a simple question for you as a shareholder: Is the market underestimating Kawasaki Kisen Kaisha’s earning power, or are the weaker profit forecasts exactly why that discount exists?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Kawasaki Kisen Kaisha’s value story are clear enough. The next move is yours, and it should be fast but informed. Weigh both the upside and the red flags by reviewing the 1 key reward and 2 important warning signs.
Looking for more ideas beyond Kawasaki Kisen Kaisha?
If Kawasaki Kisen Kaisha has you thinking harder about valuation and risk, use that momentum and line up a few fresh candidates on your watchlist.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) for potential anchors in a choppy market.
- Hunt for strong businesses that the market may be overlooking with the 72 high quality undiscovered gems before other investors catch on.
- Prioritise sleep-at-night holdings by using the 19 resilient stocks with low risk scores to spot companies that score well on downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com