
What LG Electronics Holders Bought Into
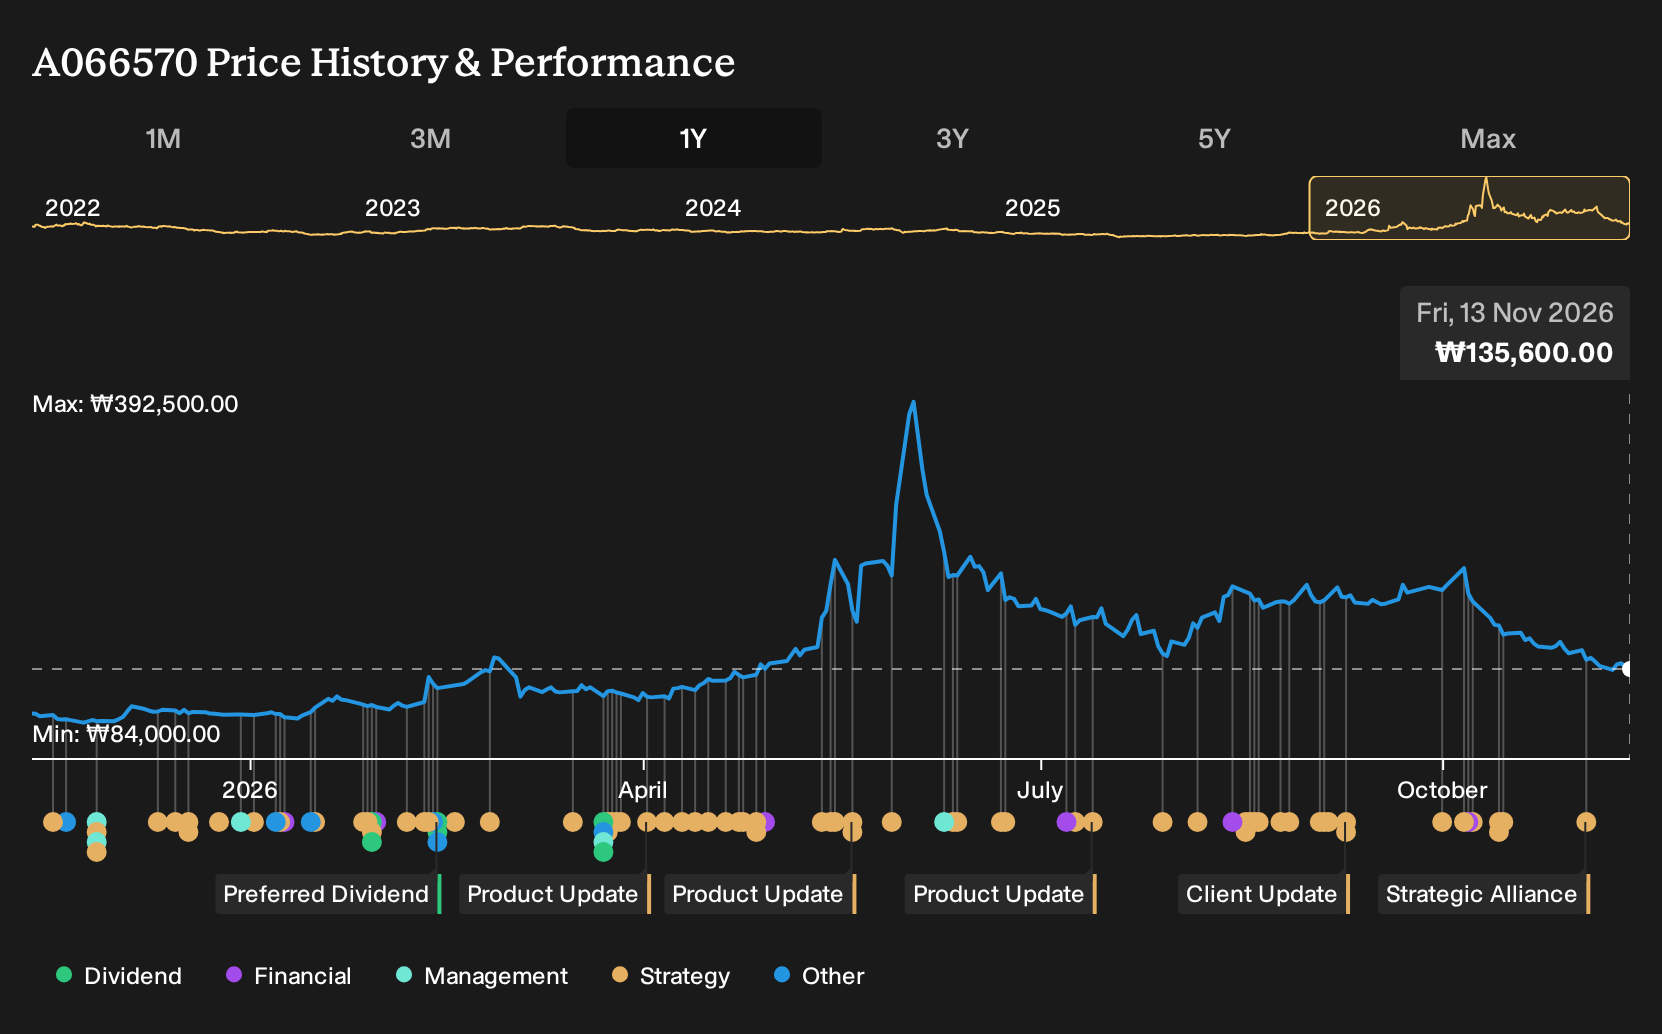
If LG Electronics was on your watchlist rather than in your portfolio, the last 12 months may feel like a tough pass to revisit. For LG Electronics shareholders, the return over the past year was 51.9%, including dividends. That move came as bulls argued that smart home IoT adoption in emerging markets and higher-margin subscription services could reshape the business. The open question now is simple. What evidence of that shift was already on record before the gain showed up in the share price?
LG Electronics is not the only name tied to this theme. Zero in on 53 AI infrastructure stocks and compare how each one is priced.
The Question Investors Faced On LG Electronics
The shares cost ₩92,800 at the start of the period, and anyone circling LG Electronics had to choose which story felt more reliable.
On the optimistic side, one narrative pointed to a Fair Value of ₩110,000, a price that would only make sense if faster smart home IoT adoption and international subscription growth lifted recurring income and margins. That view leaned on LG using tailored products in regions like Asia and Latin America to push higher-margin, connected devices.
The cautious script argued for a Fair Value of ₩77,500, assuming rising US tariffs, supply chain friction, and Chinese rivals would squeeze profitability. This camp focused on the risk that integrated ecosystems from Apple, Google, and Amazon could weaken demand for LG hardware and pressure pricing power.
What The Evidence Did To The LG Electronics Argument
The launch of the 25 inch AI powered WashTower and fresh webOS commerce and audio partnerships supported the view that LG Electronics could rely on connected appliances and services rather than just one off hardware. The Q2 2026 report presented a tougher picture. Revenue reached ₩23,826,468m, but net income stayed around ₩604,363m and net margin slipped from 2.9% to 2.5%, so profitability progress remained unproven. Overall, the evidence pointed in both directions.
The central assumption was that smarter devices and new platforms would translate into higher earnings, not just more headlines. For any other company presenting a similar shift, you would want to track whether the share of profit and margin tied to connected products and subscriptions is actually rising in the financial statements.
What LG Electronics' Current Price Is Asking You To Believe
LG Electronics now trades at ₩135,600. The bullish analyst Narrative on Simply Wall St places its Fair Value above that level, tying the gap to a tighter focus on B2B, subscription and platform activities rather than just traditional appliances and TVs.
The same Narrative leans on AI data center cooling, robotics and Global South expansion as levers that it argues are not fully reflected in today's price.
"Bullish analysts expect LG Electronics to keep shifting its mix toward B2B, subscription and platform businesses, supported by automotive electronics, subscription services and webOS driven profitability. For this view to hold, LG Electronics needs to execute on AI data center cooling, robotics and Global South expansion while containing tariff, logistics and input cost pressures that are already affecting parts of the HVAC and electronics businesses."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 49% below our estimate - uses shopper data and AI tools to move dealers into higher tier software bundles.
- Company 2 - 34% below our estimate - ramps AVL production and service capacity to support large project and data center demand.
- Company 3 - 39% below our estimate - pushes rapid store rollouts and app driven ordering to increase drink volumes per neighborhood.
That is three of the list. See every one of the 195 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com