
How Investors May Respond To Sally Beauty Stock Strong Earnings Guidance
- Sally Beauty Holdings reported fourth quarter sales of US$952.53 million and full year sales of US$3.73 billion, along with higher net income and earnings per share from continuing operations compared with the prior year.
- The company paired these results with new 2027 sales guidance and expanding digital initiatives such as Licensed Colorist On Demand, which are shaping how it serves higher spending customers.
- We will now look at how Sally Beauty Holdings' higher earnings and new 2027 sales guidance could reshape the broader investment narrative.
Compare Sally Beauty Holdings' latest guidance with other retailers that screen as potentially undervalued on earnings quality and balance sheet strength using the curated 34 high quality undervalued stocks list.
Sally Beauty Holdings Investment Narrative Recap
For an investor to stay with Sally Beauty Holdings, the core belief is that steady earnings, digital initiatives and cost savings can offset pressure in slower categories. The latest quarter showed higher net income and EPS alongside modestly higher sales, which supports that story but does not radically change it.
The key short term catalyst is execution on e commerce and Licensed Colorist On Demand, where higher spending customers are already emerging. The biggest risk remains softness in care and ancillary products, plus value focused stylist behavior in Beauty Systems Group, which could keep a lid on mix and margins if it lingers.
The analyst consensus Narrative on Simply Wall St points to cost savings from Fuel for Growth and store refreshes as central to the long term thesis. In that context, the new fiscal 2027 sales guidance of US$3.77b to US$3.81b gives investors a concrete near term bar for how management sees the demand backdrop.
That range, together with first quarter sales guidance of US$945 million to US$955 million, ties directly into the catalysts around digital growth and category expansion. If the business remains within those bands while care categories stay soft, execution on higher margin online and new store formats becomes even more important to watch.
Sally Beauty Holdings' analyst narrative points to revenues of US$3.9b and earnings of US$238.2 million by 2029. This assumes revenue grows at 1.6% per year and earnings rise by about US$38.1 million from US$200.1 million today.
Uncover why Sally Beauty Holdings' fair value indicates an 8% potential upside to its current price that could narrow quickly.
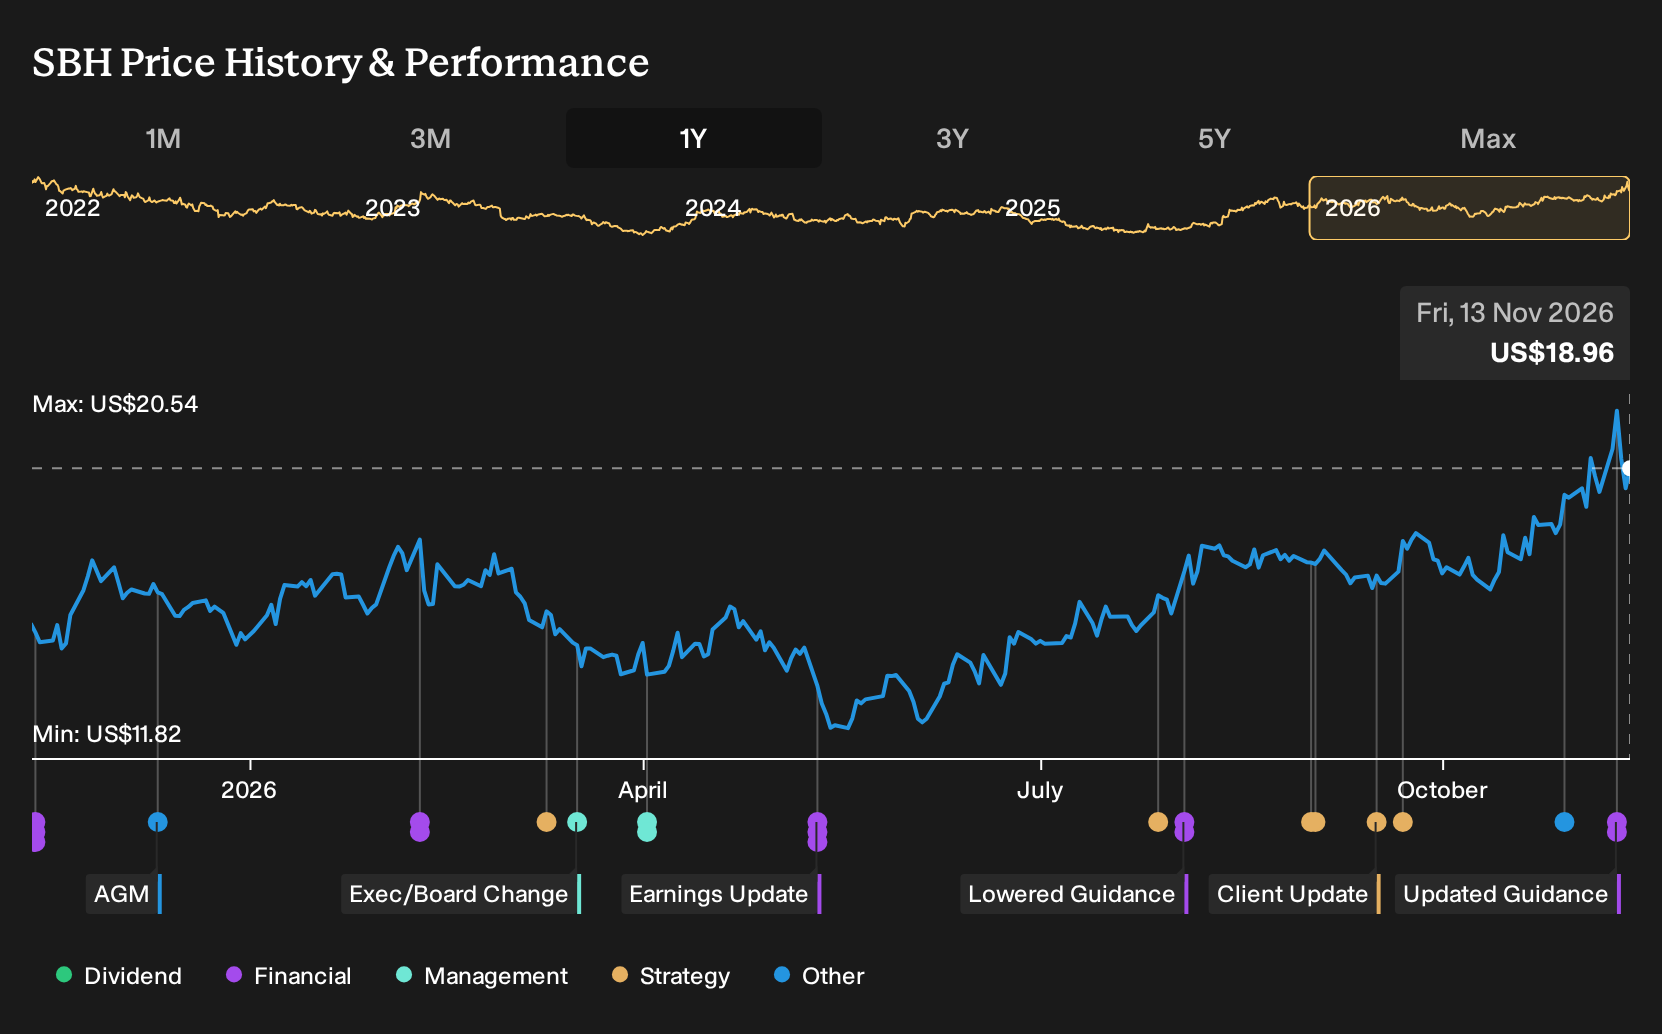
Exploring Other Perspectives
Some of the most optimistic analysts focus less on category softness and more on potential earnings power from cost savings. Before this earnings release, the bullish group was working off 2029 revenue of about US$3.9b and earnings of roughly US$240.7 million. You can compare that view with your own and decide whether this new guidance shifts your expectations.
Explore 2 other Sally Beauty Holdings fair value estimates, including one that suggests up to 173% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sally Beauty Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sally Beauty Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sally Beauty Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Sally Beauty Holdings?
Once you have a view on Sally Beauty Holdings, it helps to widen the lens and see how it compares with other opportunities that line up with your goals on value, balance sheet strength, and risk.
- If you want quality at a discount, start with companies that combine earnings support and valuation appeal using the 34 high quality undervalued stocks.
- For investors who care most about resilience, focus on businesses with robust finances and cleaner balance sheets through the list of solid balance sheet and fundamentals (24 results).
- When capital preservation ranks high for you, concentrate on companies with lower overall risk profiles by scanning the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com