
Inspire Medical Systems (INSP) Cut Its Outlook, Is The Stock Fully Valued?
Why Inspire Medical Systems is back in focus
Inspire Medical Systems (INSP) has moved into the spotlight after reporting third quarter results that showed lower sales and a swing to a loss, while management also tightened its full year 2026 revenue and earnings outlook.
The updated guidance now calls for full year revenue between US$850 million and US$860 million, with diluted EPS projected between a loss of US$0.36 and US$0.10. This is reshaping how investors might frame risk and potential reward around the stock.
Investors have reacted sharply to these updates from Inspire Medical Systems, with the share price now at US$61.10. The 30 day share price return is down 11.18%, the year to date share price return has fallen 33.78%, and the 5 year total shareholder return is down 76.79%. This points to fading longer term momentum, despite a 6.78% 90 day share price gain and a 1 year total shareholder return that is down 29.24%, as the latest earnings miss and narrowed outlook reset expectations.
Scan 34 high quality undervalued stocks that have not sold off as sharply as Inspire Medical Systems, yet still combine resilient cash flows with balance sheets that can better absorb earnings setbacks.
The selloff in Inspire Medical Systems follows a clear earnings reset, yet some of the move also reflects a change in mood toward high growth medtech. How does that mix show up in the current valuation?
Most Popular Narrative: 10.1% Undervalued
Inspire Medical Systems is priced at $61.10, while the analyst consensus Narrative on Simply Wall St anchors fair value at $68.00. This suggests that analysts view the current quotation as below their central scenario and are incorporating specific assumptions on growth, margins and risk to arrive at that estimate.
The analysts have a consensus price target of $68.0 for Inspire Medical Systems based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $97.0, and the most bearish reporting a price target of just $40.0.
See why 10 investors see Inspire Medical Systems as 10% undervalued.
Result: Fair Value of $68.00 (UNDERVALUED)
Still, reimbursement setbacks or prolonged WISeR related disruptions around Inspire V, combined with ongoing legal scrutiny, could quickly weaken confidence in the current Inspire Medical Systems narrative.
Find out about the key risks to this Inspire Medical Systems narrative.
Another view on Inspire Medical Systems’ valuation
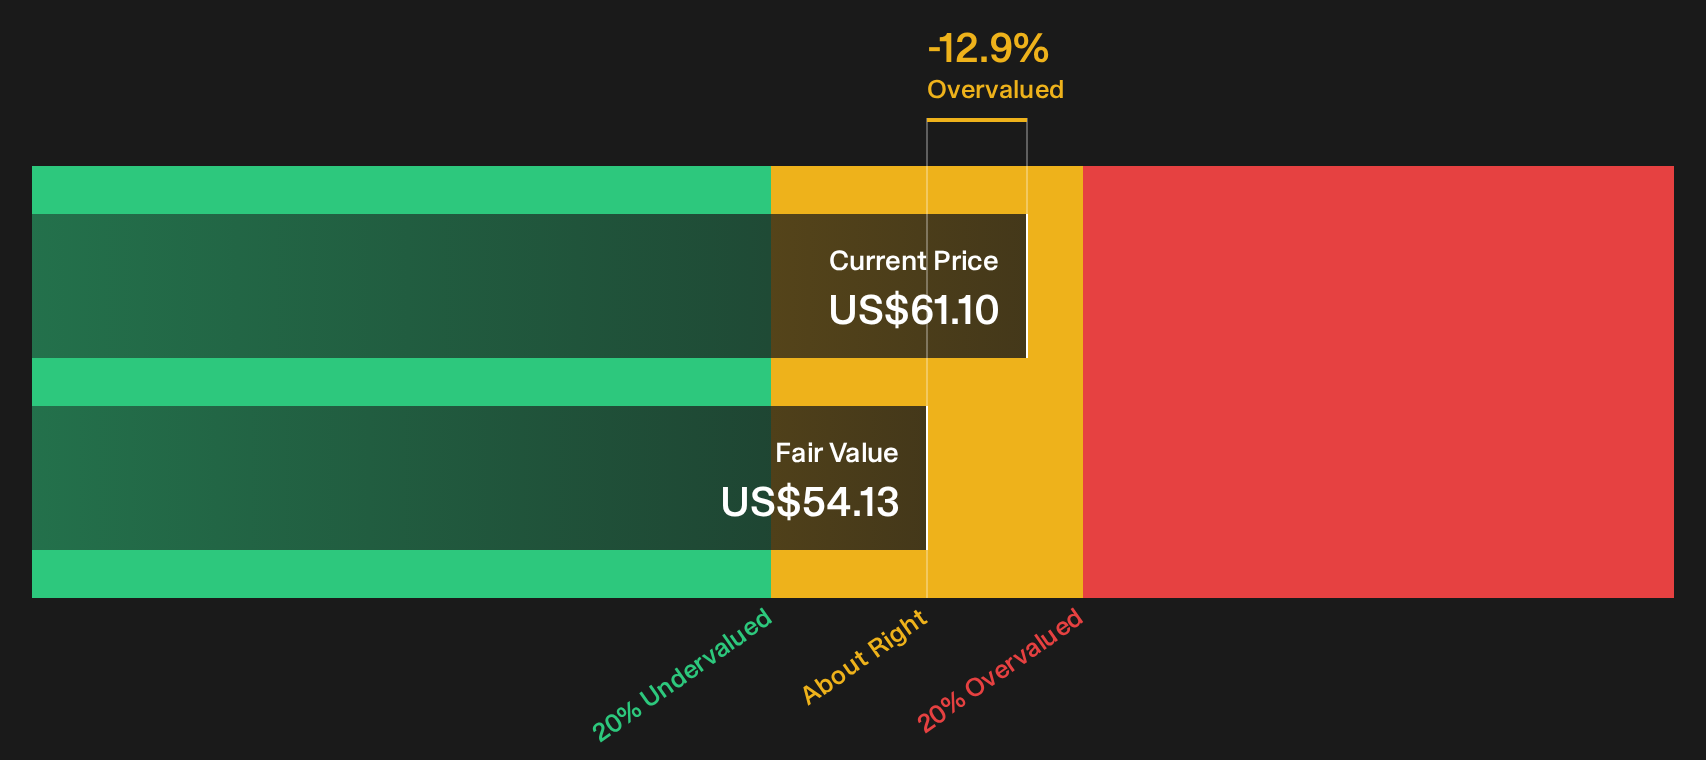
The analyst fair value for Inspire Medical Systems leans on earnings forecasts and P/E assumptions. A different lens comes from Simply Wall St’s DCF model, which estimates future cash flow value at US$54.13, below the current US$61.10 share price, framing the stock as overvalued by that method.
If one framework implies undervaluation while our DCF model points the other way, which set of assumptions feels closer to how you think Inspire Medical Systems will actually perform over time?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Inspire Medical Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on value and risk can either freeze you or push you to look harder at the underlying numbers. If you want to move quickly from headline reactions to a clearer personal thesis on Inspire Medical Systems, start by weighing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Inspire Medical Systems?
If Inspire Medical Systems has sharpened your thinking, do not stop here. Use the Screener to spot stronger balance sheets, steadier returns, and fresh opportunities.
- Target resilience by focusing on businesses that pair durable earnings with conservative financing through a list of solid balance sheet and fundamentals (24 results) that keeps financial strength front and center.
- Zero in on quality at a discount by scanning a 34 high quality undervalued stocks that blends solid fundamentals with prices that may sit below intrinsic worth.
- Prioritize calm over drama by working through a 29 resilient stocks with low risk scores where volatility and financial red flags take a back seat to stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com