
Does Talkspace Deal Change The Bull Case For UHS Stock?
- Universal Health Services reported that improving performance at three historically loss making hospitals, together with the recently completed Talkspace acquisition, is expected to help absorb a projected reduction of roughly US$175 million to US$200 million in nonrecurring Medicaid supplemental payments after 2026.
- Management also indicated that lower capital spending could free up cash for further share repurchases. This places more weight on Talkspace driven outpatient behavioral growth and operational gains at weaker facilities to support overall financial resilience as Medicaid funding normalizes.
- We will look at how Universal Health Services' investment narrative holds up as Talkspace driven outpatient growth is asked to offset Medicaid cuts.
Compare how Universal Health Services is repositioning around outpatient behavioral care with a curated group of peers by scanning 36 healthcare AI stocks benefiting from digital tools and data driven treatment models.
Universal Health Services Investment Narrative Recap
To own Universal Health Services, you need to believe the outpatient behavioral pivot can shoulder more of the load as Medicaid support steps down. The analyst consensus Narrative on Simply Wall St already leaned on Talkspace, AI tools and new capacity to offset reimbursement and liability pressures. The latest guidance around US$175 million to US$200 million in nonrecurring Medicaid payments falling away after 2026 largely reinforces that storyline rather than changing it.
In the near term, the key swing factor is whether Talkspace and the improving three hospitals can pull their weight quickly enough as those payments fade. The biggest risk is that ACA and Medicaid coverage headwinds, plus liability expenses running at about US$175 million to US$200 million per year, outpace efficiency gains and better payor mix, leaving earnings and cash generation under pressure.
The Talkspace acquisition sits at the center of this update because management is effectively asking that outpatient behavioral engine to help cover the Medicaid gap. The deal adds roughly US$250 million of outpatient revenue and access to 6,000 therapists, and is expected to be slightly accretive to adjusted net income in its first year. That gives Universal Health Services more volume and data across lower acuity virtual services that can connect into its higher acuity facilities.
This matters for catalysts and risk in a very operational way. If Talkspace integration goes smoothly, outpatient behavioral care and AI supported workflows in revenue cycle and post discharge outreach can help absorb both the Medicaid and ACA coverage headwinds that are tracking near US$100 million per year each. If execution stalls, those same policy and liability pressures could weigh more heavily on margins just as capital spending is eased to fund buybacks.
Universal Health Services' narrative projects US$21.3b revenue and US$1.4b earnings by 2029. This assumes 5.1% yearly revenue growth and an earnings decline of US$0.1b from US$1.5b today.
Uncover why Universal Health Services' fair value is essentially consistent with its current price.
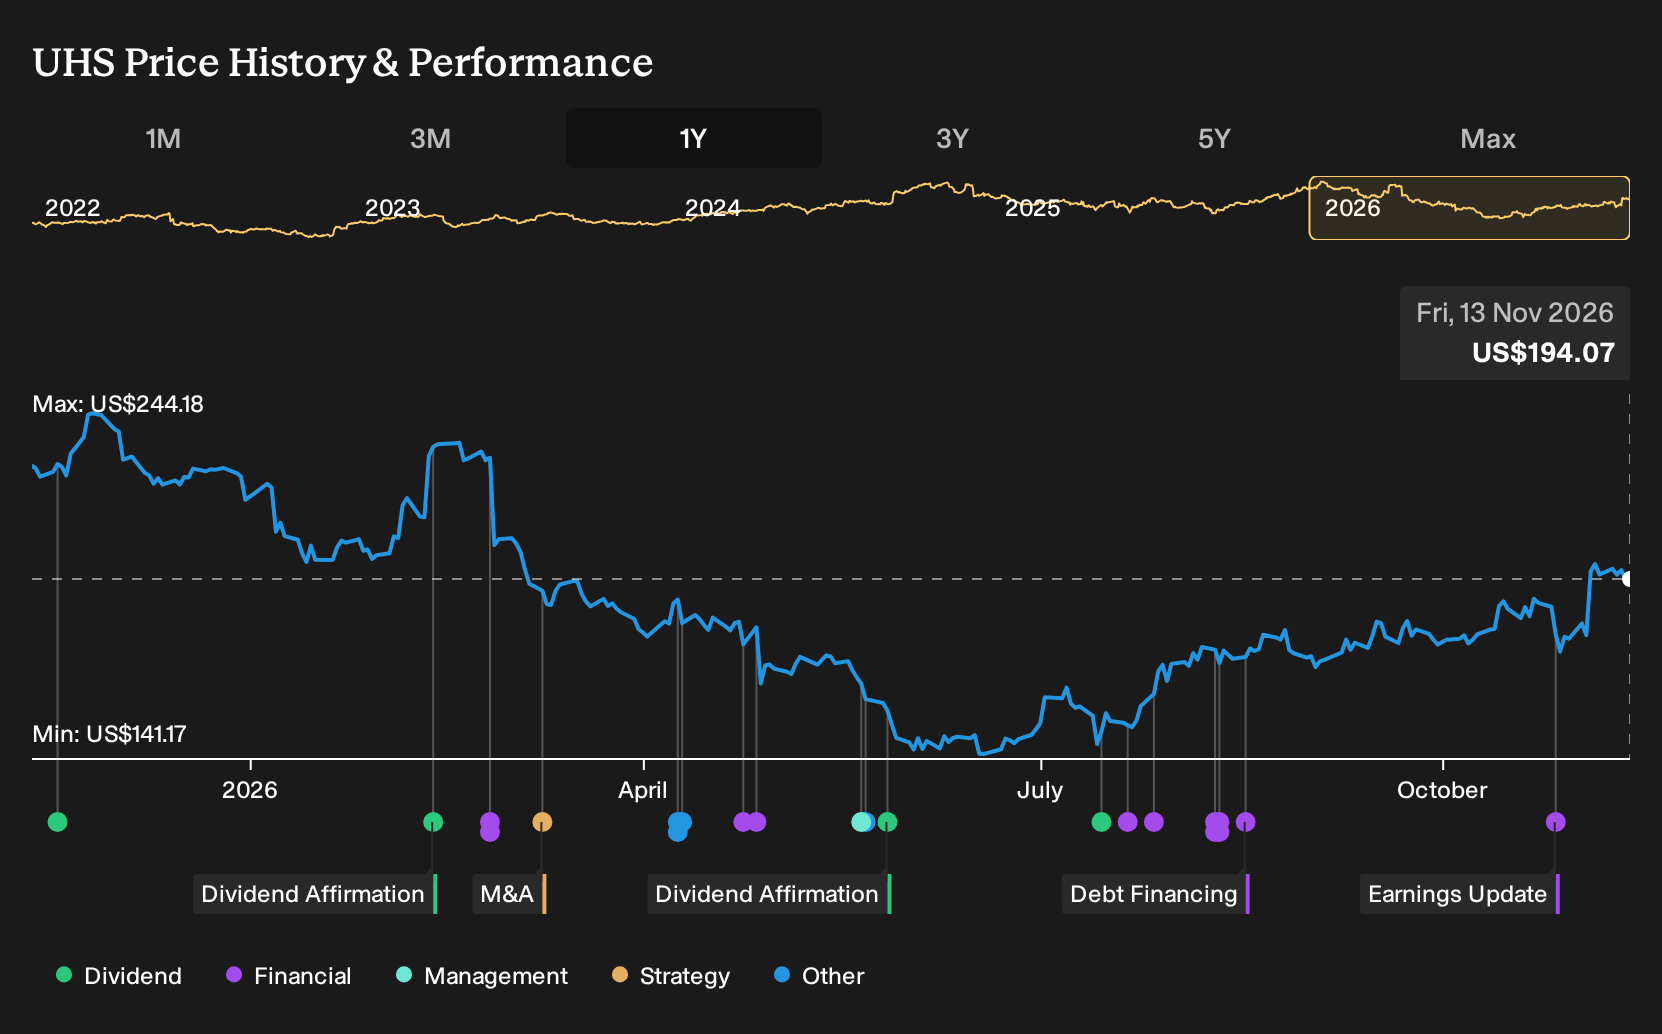
Exploring Other Perspectives
Some of the lowest Universal Health Services analysts leaned hard into reimbursement risk rather than Talkspace opportunity. They were modeling revenue of about US$20.1b and earnings near US$1.2b by 2029. That paints a more cautious story. Use this new Medicaid update as a prompt to compare those assumptions with your own view.
Explore 4 other Universal Health Services fair value estimates, including one that suggests it could be worth just $195.24.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own judgment.
- A great starting point for your Universal Health Services research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Universal Health Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal Health Services' overall financial health at a glance.
Looking For More Investment Ideas Beyond Universal Health Services?
If the Universal Health Services story has sharpened your thinking about risk, balance sheets and payout profiles, it can be useful to compare that against other opportunities using the Simply Wall St Screener.
- For investors who want quality and value working together, sift through a curated pool of 34 high quality undervalued stocks that pair healthy fundamentals with discounted prices.
- If capital preservation is front of mind, focus on defence first by scanning 29 resilient stocks with low risk scores that score well on resilience and downside protection.
- When income is the priority, build a watchlist of potential yield workhorses by reviewing 6 dividend fortresses offering payout levels that may complement your portfolio mix.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com