
Why Centrus Energy (LEU) Is Back In The Spotlight
Centrus Energy (LEU) just turned a June letter of intent with Oklo into binding, multi year HALEU supply contracts, supported by Meta funded prepayments that support new enrichment capacity in Ohio.
Centrus Energy’s latest HALEU contracts land after a rough stretch for the ticker, with the share price down about 10% over the past month and roughly 44% over 90 days, even though the 3 year total shareholder return is close to 98% and the 5 year total shareholder return is about 62%. This suggests long term holders have still seen meaningful gains while shorter term sentiment has weakened as investors weigh fresh capital plans, recent earnings and the new Ohio expansion against perceived risk.
Scan curated nuclear energy infrastructure opportunities alongside Centrus Energy by focusing on a hand picked list of 17 nuclear energy infrastructure stocks that could benefit from similar long term power demand themes.
Centrus Energy now has long term HALEU contracts, Meta backed prepayments and a stock that has already rerated hard over three years. Is most of the payoff already in the rear view mirror, or is the valuation still leaving room?
Most Popular Narrative: 45% Undervalued
Centrus Energy last closed at $103.78, while the most followed valuation narrative on Simply Wall St pegs fair value at about $190. That gap is the anchor for a thesis that leans heavily on HALEU as a fuel bottleneck, according to CentryResearch, an investor in the Simply Wall St Community who wrote the narrative.
Centrus Energy (LEU) offers the most direct public-market exposure to U.S. HALEU production, a critical bottleneck for advanced nuclear deployment.
HALEU fuel scarcity could constrain next-gen reactor rollouts, making LEU's enrichment capabilities strategically vital as AI-driven electricity demand surges.
See why 45 investors see Centrus Energy as 45% undervalued.
Result: Fair Value of $190 (UNDERVALUED)
Still, the Centrus Energy story could be challenged if domestic HALEU capacity expands faster than expected, or if advanced reactor deployment timelines stretch out again.
Find out about the key risks to this Centrus Energy narrative.
Another View: Centrus Energy Through The P/E Lens
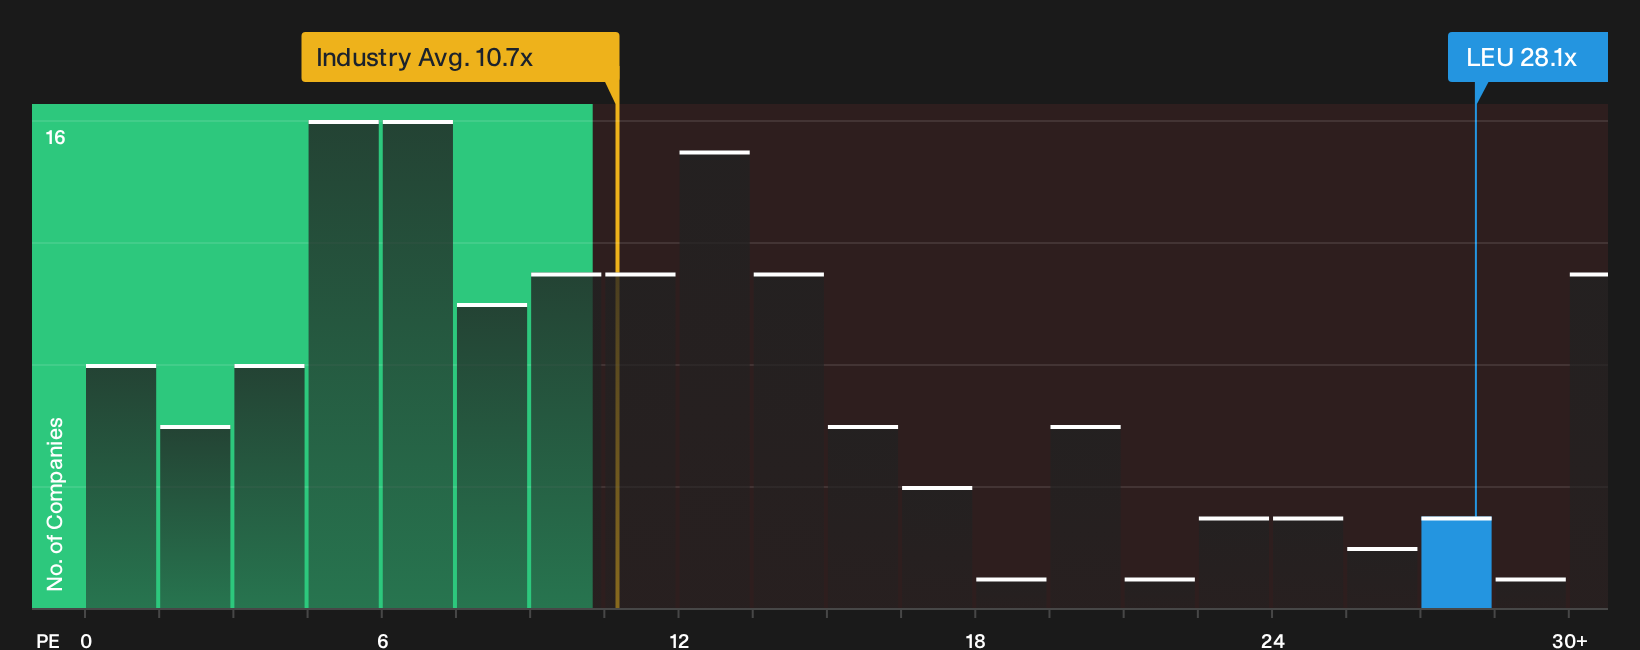
That $190 fair value narrative for Centrus Energy runs into a very different picture once you look at the P/E. At around 28.1x earnings, the stock trades well above the peer average of 24.6x and far above the US Oil and Gas group near 10.7x. The fair ratio of 7.8x suggests the market could shift closer to a level that implies much less optimism built into the price.
For investors comparing these signals, the question is simple: Is the HALEU bottleneck story strong enough to justify paying a multiple that screens as expensive on every relative yardstick?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of HALEU optimism and a punchy P/E leaves you split, put the numbers under your own microscope and pressure test the risks. Start by weighing the 3 important warning signs.
Looking for more Centrus Energy style investment ideas?
Do not stop your work with Centrus Energy alone. Broaden your watchlist now or you risk missing opportunities that better match your goals and risk appetite.
- Target long term value by scanning a focused universe of companies with strong earnings power using the 34 high quality undervalued stocks.
- Strengthen your income stream by reviewing the 6 dividend fortresses that combine higher yields with more resilient payout histories.
- Reduce portfolio stress by concentrating on resilience and balance sheet quality through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com