
Tootsie Roll Industries (TR) Could Be 119% Overvalued Following Weaker Third Quarter Earnings
Third quarter earnings put Tootsie Roll Industries in focus
Tootsie Roll Industries (TR) moved into the spotlight after reporting third quarter 2026 results, with revenue and net income lower than the same period last year. This has prompted fresh attention on the stock.
At a last close of $38.28, Tootsie Roll Industries has seen its share price climb 11.35% year to date. The 5 year total shareholder return of 45.24% contrasts with a softer 1 year total shareholder return of 1.09%, suggesting longer term holders have fared better than more recent buyers.
Compare how Tootsie Roll Industries stacks up against other confectionery and packaged food stocks that screen well on quality and value by scanning our hand picked 34 high quality undervalued stocks today.
Bulls point to Tootsie Roll Industries' long track record and recent share price resilience. Bears highlight the weaker 2026 earnings. The valuation now has to show which side has the stronger case.
Price-to-Earnings of 34.4x: Is it justified?
Tootsie Roll Industries currently trades on a P/E of 34.4x, which is being applied to a stock that recently reported softer earnings and net income margins than a year ago.
The P/E ratio compares the share price with earnings per share. For a mature confectionery producer like Tootsie Roll Industries, this yardstick often reflects how much investors are willing to pay for each dollar of profit in a sector where growth is usually steady rather than rapid.
Here the market is assigning a higher price tag to each dollar of earnings than it does for similar businesses. TR is described as expensive versus a peer average P/E of 22.2x and even richer against the broader US Food industry, which is at 18.1x. That premium sits alongside a recent decline in earnings of 11.5% over the past year and net profit margins that eased from 12.9% to 11.4%, which raises questions about whether the current pricing is too enthusiastic or simply reflects confidence in the company’s long operating history and perceived earnings quality.
When set directly against the sector, the contrast is sharp. A P/E of 34.4x is more than 50% higher than the peer group on 22.2x and close to double the US Food industry average of 18.1x, which signals that investors are paying a substantial premium for exposure to Tootsie Roll Industries at today’s levels.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 34.4x (OVERVALUED)
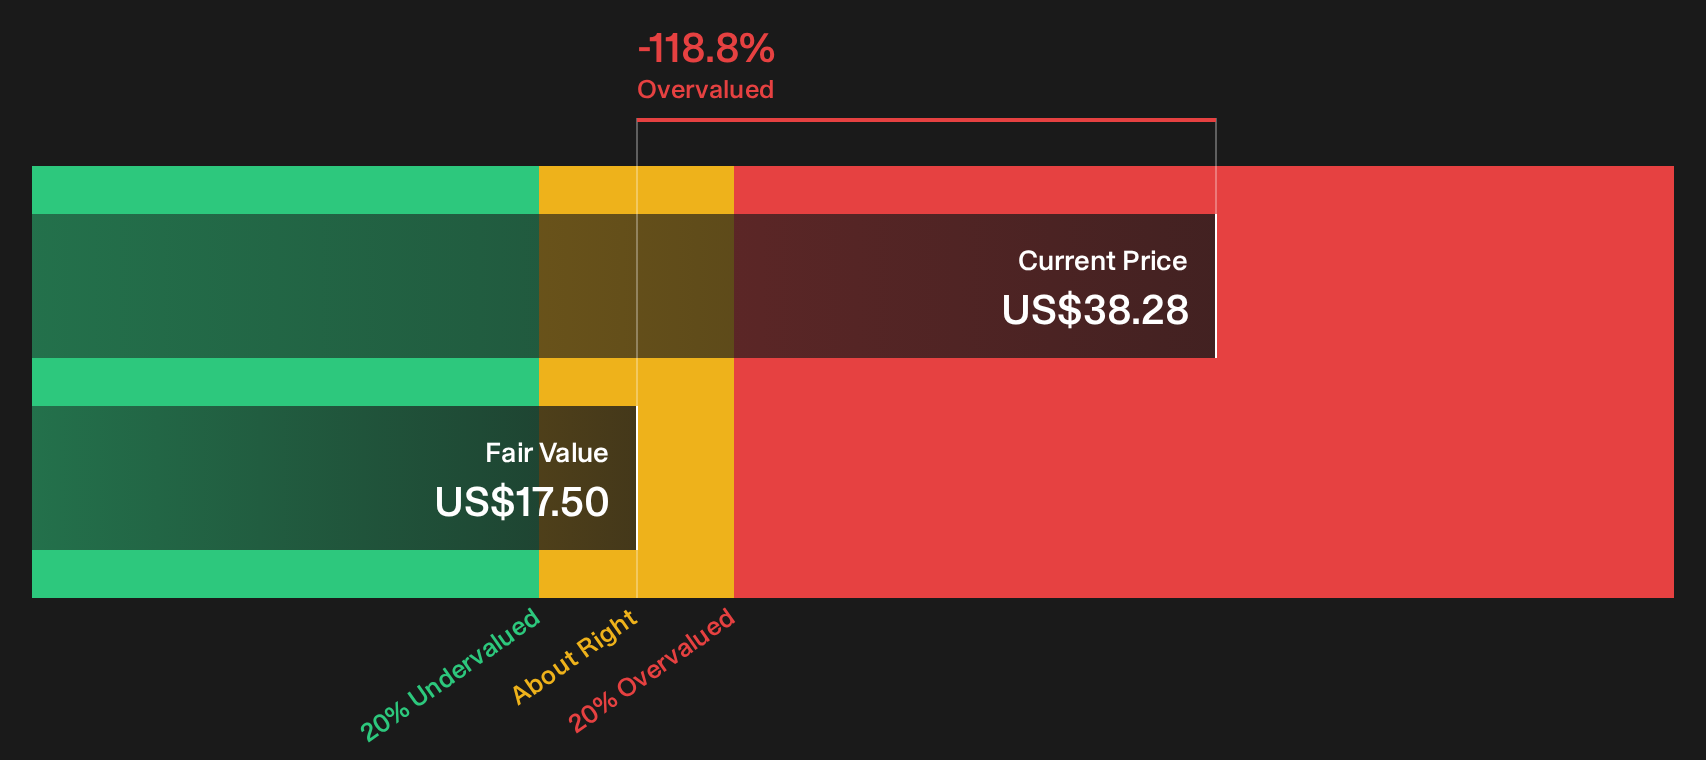
Still, the rich P/E and an intrinsic discount of 118.79% on some models leave Tootsie Roll Industries exposed if earnings softness persists or if investor appetite cools.
Find out about the key risks to this Tootsie Roll Industries narrative.
Another view on Tootsie Roll Industries using our DCF model
The rich P/E story for Tootsie Roll Industries meets a very different message from our DCF work. The SWS DCF model points to a future cash flow value of $17.50 a share, well below the current $38.28 price, which flags the stock as overvalued on this lens.
That gap implies limited protection if sentiment cools or earnings disappoint. The real question for you is which yardstick feels more reliable for a confectionery business like this.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tootsie Roll Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Looking for more investment ideas beyond Tootsie Roll Industries?
If Tootsie Roll Industries feels fully priced, do not stop there. Use this as a starting point to line up the next three ideas on your watchlist.
- Spot potential bargains early by scanning a curated pool of quality companies that still trade below their estimated worth with the 34 high quality undervalued stocks.
- Build a steadier income stream by checking out stocks that focus on robust cash returns to shareholders through the 6 dividend fortresses.
- Reduce portfolio stress by hunting for companies with cleaner finances and stronger balance sheets using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com