
Does Earnings Surge Change The Bull Case For Century Aluminum Stock (CENX)?
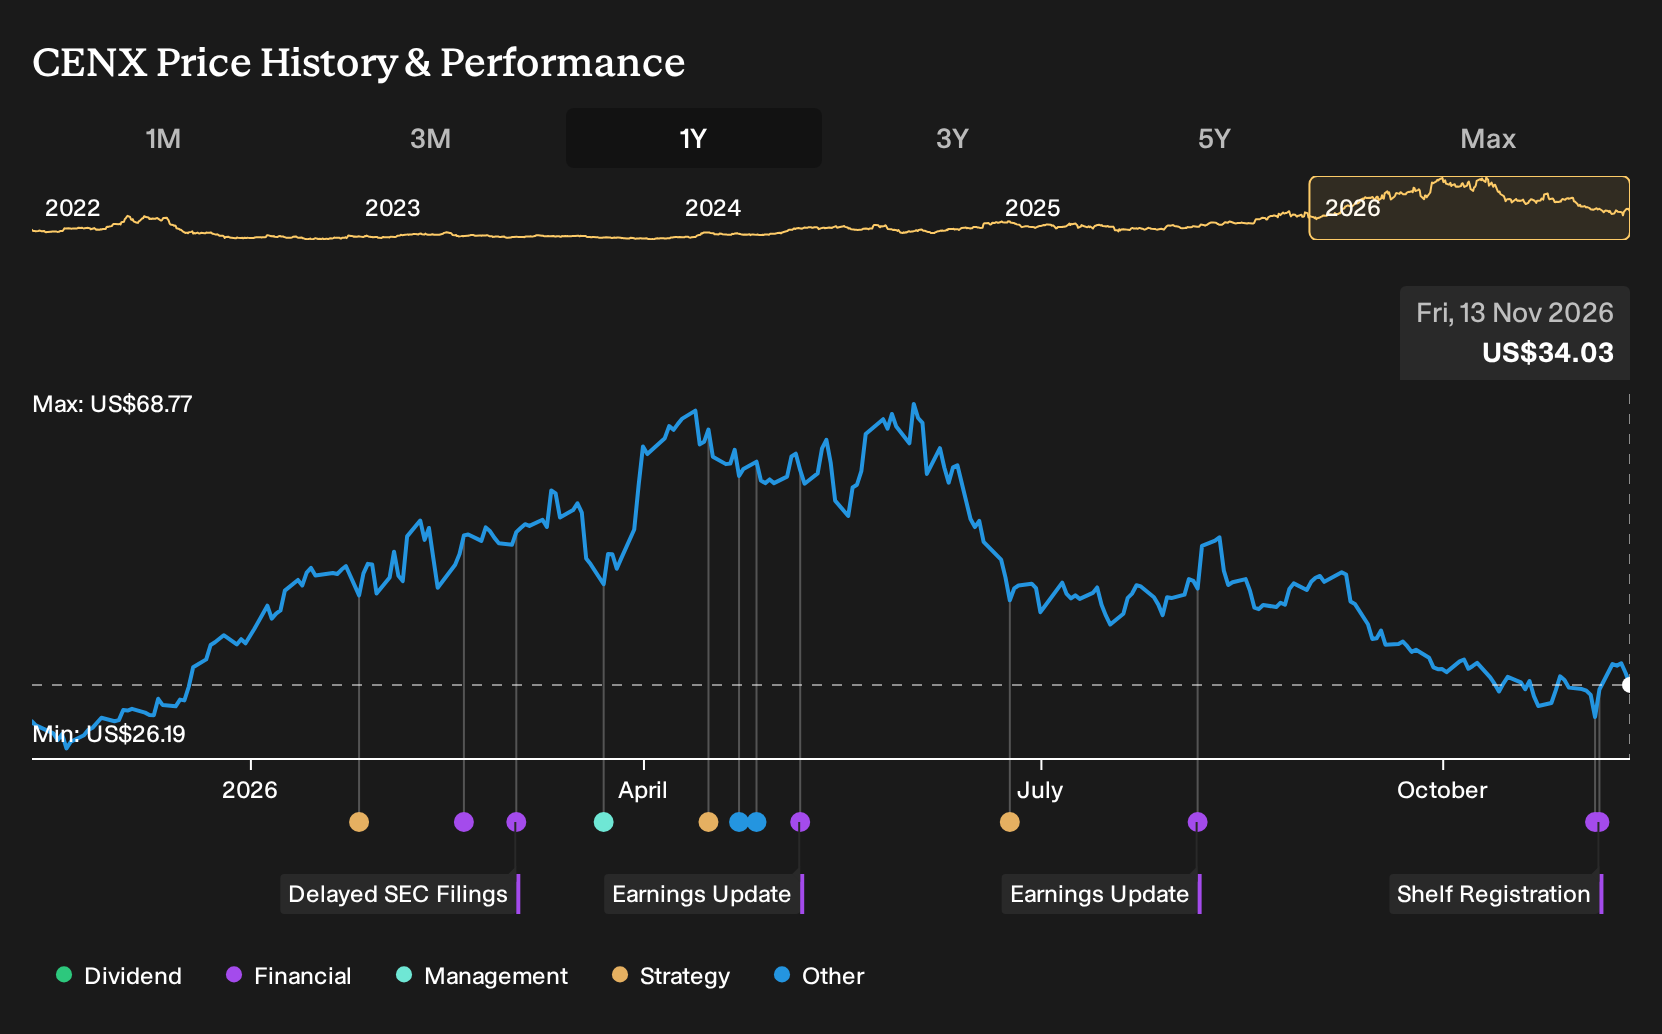
- Century Aluminum reported third quarter 2026 revenue of US$961.2 million and net income of US$302.6 million, with basic earnings per share from continuing operations of US$3.06, and also put an omnibus shelf registration in place covering a wide range of possible securities issuances.
- The combination of materially higher earnings for both the quarter and the nine month period, together with fresh shelf capacity, gives Century Aluminum added financial flexibility that could matter for funding large capital projects and managing the balance sheet.
- This article will look at how Century Aluminum's sharply higher quarterly net income affects the existing investment narrative around growth projects.
Scan other metal producers that pair balance sheet flexibility with earnings power by reviewing our curated list of list of solid balance sheet and fundamentals (24 results).
Century Aluminum Investment Narrative Recap
To own Century Aluminum, you need to be comfortable with a story built on tight aluminum supply, large capital projects like the Oklahoma smelter, and healthy LME and regional premiums. The analyst consensus Narrative on Simply Wall St leans on those themes, and the latest quarterly numbers show very strong earnings power, but do not remove exposure to commodity pricing.
The most important short term swing factor still sits with realized prices and premiums, which recently added US$95 million in a single quarter. Any softening there or further cost issues at assets like Jamalco could matter more to near term earnings than one strong quarter. As a result, the recent results do not eliminate key risks.
The universal shelf registration filed in early November is the announcement that ties most directly into this catalyst and risk mix. With the ability to issue common equity, preferred stock, debt, warrants and more, Century Aluminum now has extra flexibility if large spends are required at Oklahoma, Mt. Holly, Grundartangi or Jamalco.
For you as a shareholder, that tool cuts both ways. Extra funding capacity can support projects that aim to lift shipments and use of fixed costs, in line with the analyst consensus Narrative on Simply Wall St. At the same time, any substantial issuance could dilute existing holders or lift financial leverage while the business remains highly exposed to aluminum prices and premiums.
Century Aluminum's narrative projects US$4.6b revenue and US$905.4 million earnings by 2029. This assumes 15.1% yearly revenue growth and an earnings increase of about US$14 million from current earnings of US$891.4 million.
Uncover how Century Aluminum's fair value indicates a 64% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Some of the more cautious analysts focus less on the new shelf flexibility and more on Jamalco cost pressure. Before this quarter, the lowest forecasts were building in about US$4.0b of 2029 revenue and US$765.3 million of earnings. That is a much more pessimistic Century Aluminum story, and this latest news could shift those views.
Explore 4 other Century Aluminum fair value estimates, including one that suggests it could be worth just $40.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Century Aluminum research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Century Aluminum. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Century Aluminum's overall financial health at a glance.
Looking for more investment ideas beyond Century Aluminum?
If the Century Aluminum story has you thinking about position sizing, sector exposure, or simply fresh opportunities, it can help to line it up against a wider field of stocks with different risk and income profiles.
- For investors who want to focus on resilient balance sheets with room to fund growth, start with this curated list of solid balance sheet and fundamentals (24 results) and compare how those businesses manage debt and liquidity.
- If value is your priority and you like the idea of paying less than what fundamentals might justify, scan through a 34 high quality undervalued stocks that highlights companies combining quality metrics with potentially attractive pricing.
- For readers who care most about income and cash returns, put together a shortlist from a 6 dividend fortresses that screens for higher yielding businesses with the potential to support regular payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com