
We're Interested To See How Elementos (ASX:ELT) Uses Its Cash Hoard To Grow
Just because a business does not make any money, does not mean that the stock will go down. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. But while the successes are well known, investors should not ignore the very many unprofitable companies that simply burn through all their cash and collapse.
So should Elementos (ASX:ELT) shareholders be worried about its cash burn? In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. First, we'll determine its cash runway by comparing its cash burn with its cash reserves.
How Long Is Elementos' Cash Runway?
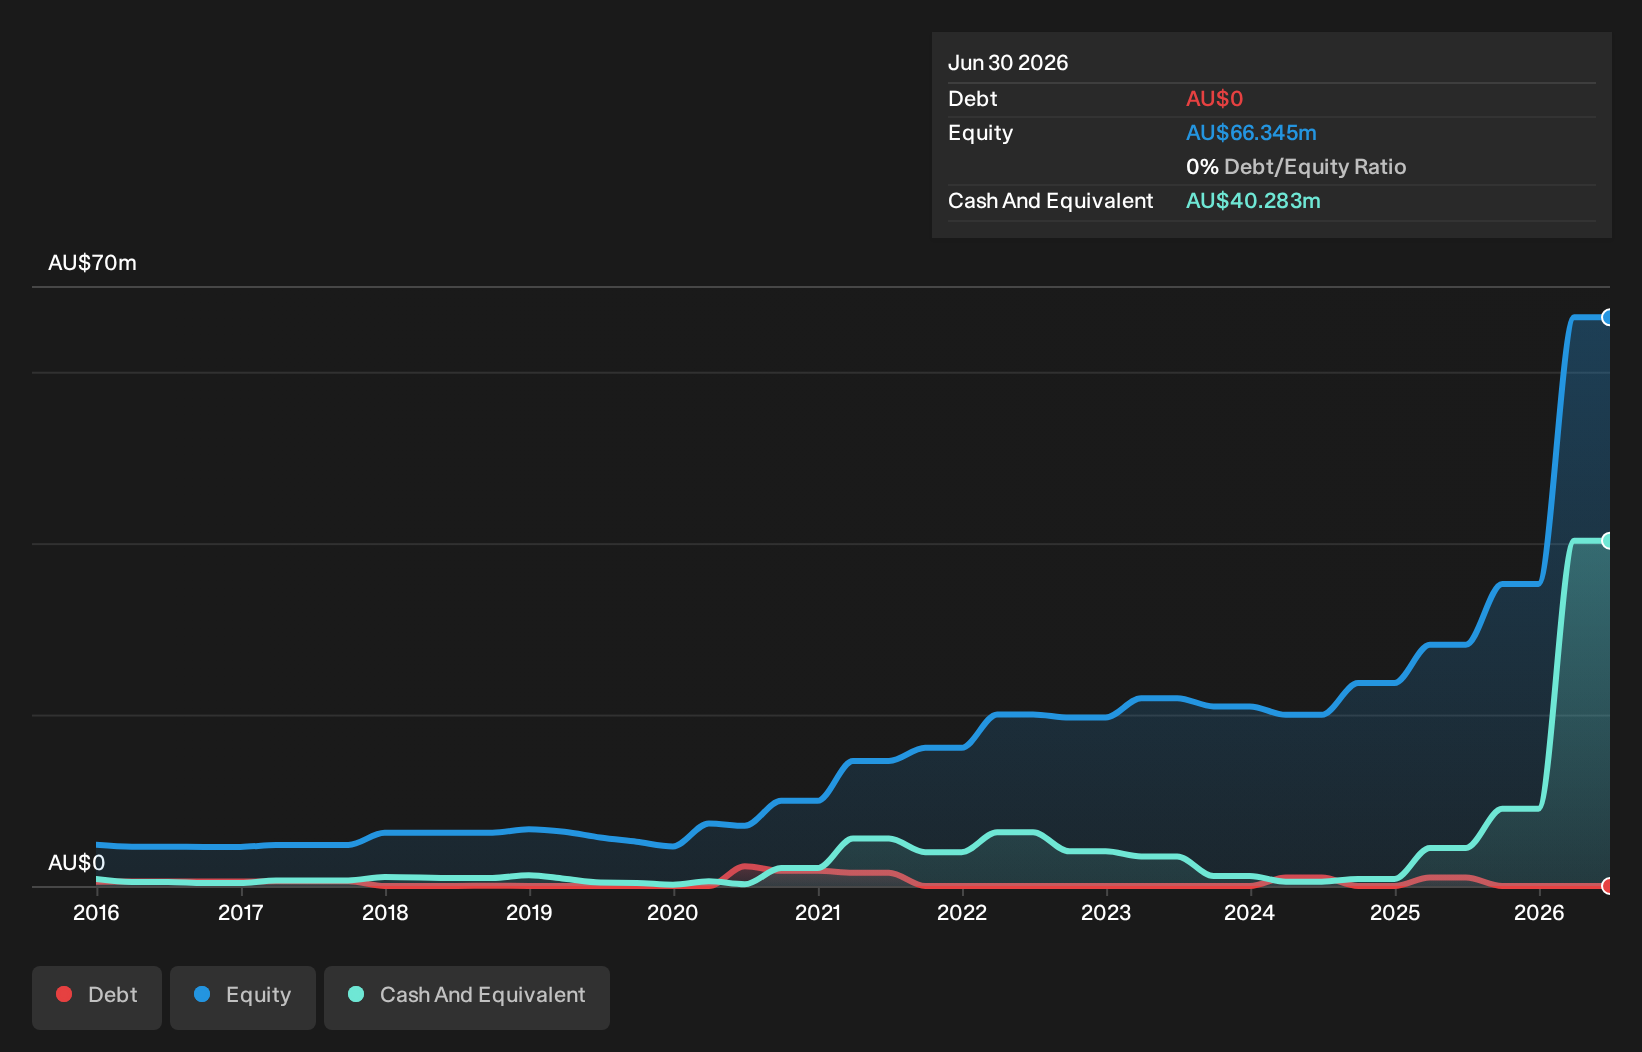
A cash runway is defined as the length of time it would take a company to run out of money if it kept spending at its current rate of cash burn. When Elementos last reported its June 2026 balance sheet in September 2026, it had zero debt and cash worth AU$40m. Importantly, its cash burn was AU$4.6m over the trailing twelve months. That means it had a cash runway of about 8.8 years as of June 2026. While this is only one measure of its cash burn situation, it certainly gives us the impression that holders have nothing to worry about. Depicted below, you can see how its cash holdings have changed over time.
Check out our latest analysis for Elementos
How Is Elementos' Cash Burn Changing Over Time?
Although Elementos reported revenue of AU$10k last year, it didn't actually have any revenue from operations. That means we consider it a pre-revenue business, and we will focus our growth analysis on cash burn, for now. With cash burn dropping by 2.4% it seems management feel the company is spending enough to advance its business plans at an appropriate pace. While the past is always worth studying, it is the future that matters most of all. For that reason, it makes a lot of sense to take a look at our analyst forecasts for the company.
Can Elementos Raise More Cash Easily?
Even though it has reduced its cash burn recently, shareholders should still consider how easy it would be for Elementos to raise more cash in the future. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Since it has a market capitalisation of AU$178m, Elementos' AU$4.6m in cash burn equates to about 2.6% of its market value. So it could almost certainly just borrow a little to fund another year's growth, or else easily raise the cash by issuing a few shares.
How Risky Is Elementos' Cash Burn Situation?
It may already be apparent to you that we're relatively comfortable with the way Elementos is burning through its cash. In particular, we think its cash runway stands out as evidence that the company is well on top of its spending. Its weak point is its cash burn reduction, but even that wasn't too bad! After taking into account the various metrics mentioned in this report, we're pretty comfortable with how the company is spending its cash, as it seems on track to meet its needs over the medium term. Readers need to have a sound understanding of business risks before investing in a stock, and we've spotted 3 warning signs for Elementos that potential shareholders should take into account before putting money into a stock.
Of course Elementos may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.