
How Investors May Respond To Schwab (SCHW) Record Client Asset Growth
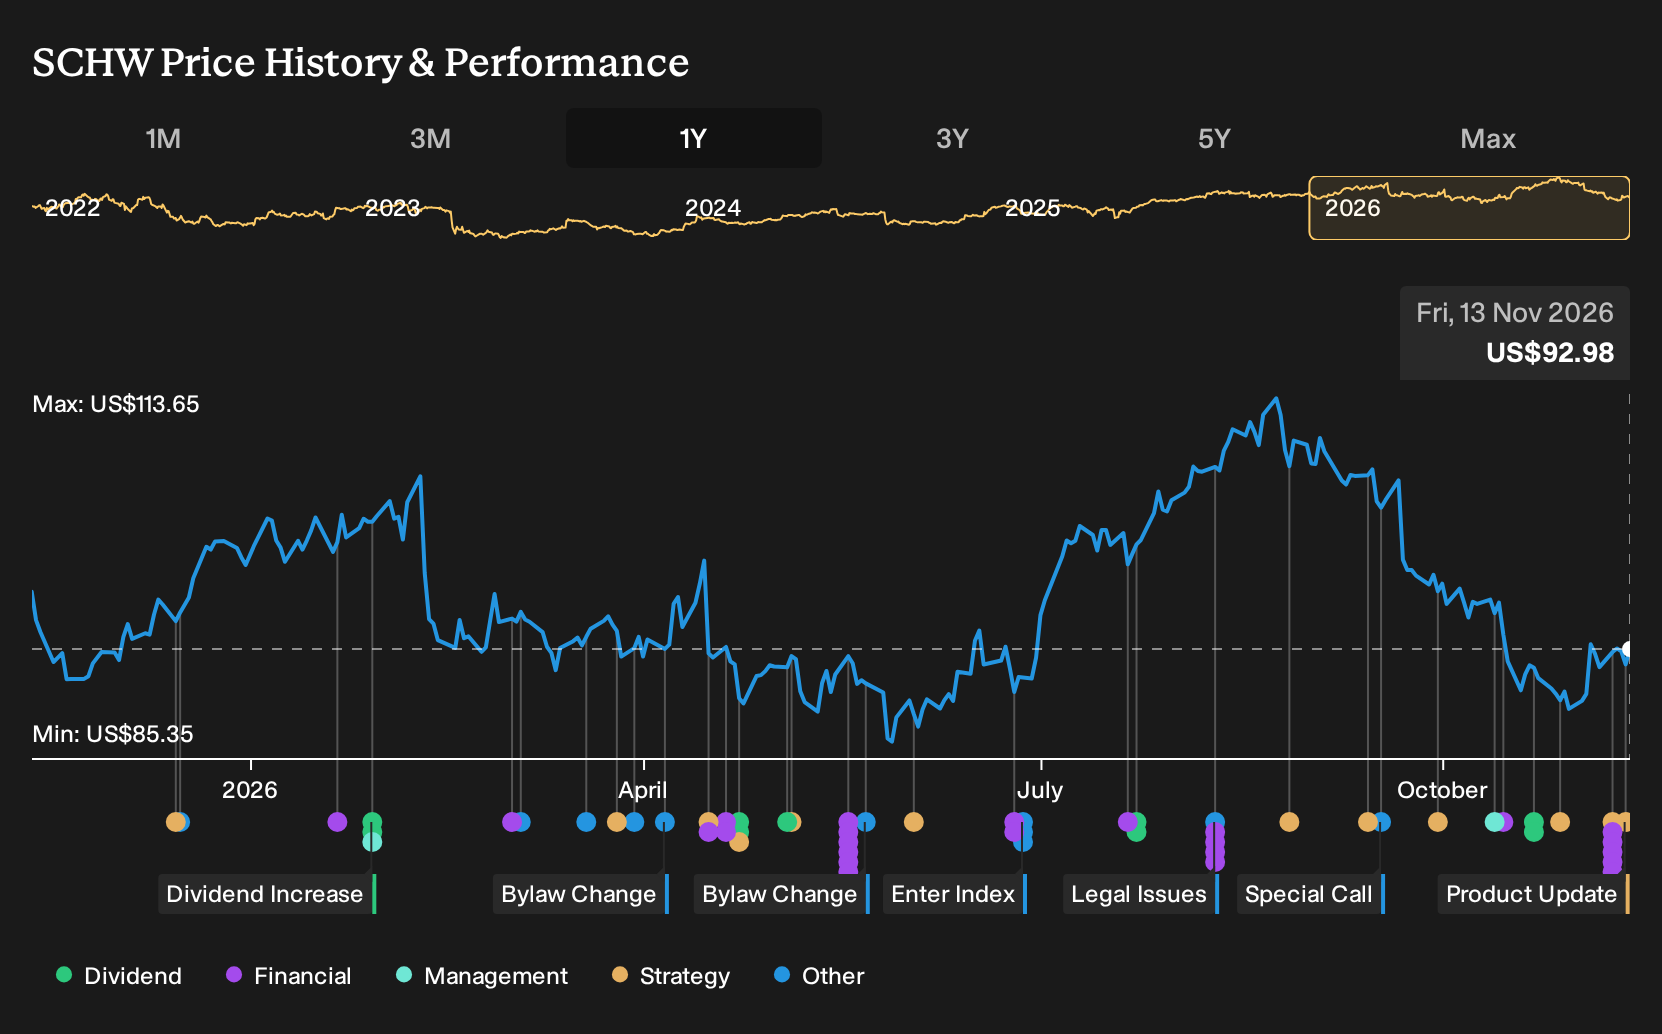
- Charles Schwab recently reported record core net new assets of US$66.5b in October and US$13.27t in total client assets, alongside a wave of AI driven trading tools, platform upgrades, and expanded crypto access covering five major tokens.
- The combination of asset gathering, extended hours options trading, and integrated digital assets access highlights Schwab focusing on increased client engagement across both traditional and newer investment products.
- We will now look at how Charles Schwab's record core net new assets relate to its investment narrative and long term business mix.
Scan how Charles Schwab is reshaping trading with AI tools, crypto access, and extended hours, then size it up against a hand-picked set of 53 AI infrastructure stocks in the broader market.
Charles Schwab Investment Narrative Recap
To own Charles Schwab, you need to believe the brokerage can keep deepening client engagement and monetizing a very large asset base through interest income, trading, and advice while holding the cost line. The analyst consensus Narrative on Simply Wall St leans on expense discipline and steady revenue growth. The recent AI and platform upgrades mainly reinforce that story rather than change the near term setup.
Right now, the key short term swing factor is how efficiently Schwab converts client asset growth and higher trading activity into earnings without letting technology and regulatory costs run away. Rising spend on AI tools, expanded crypto access, and platform improvements could pressure margins if volumes or pricing do not keep pace.
The most relevant announcement for this catalyst is Schwab’s new Model Context Protocol server and generative AI tools like thinkorswim Assistant and Charley. These additions pull account data, trading, education, and service into a more conversational, automated experience that could lift activity, deepen relationships, and support cross selling across brokerage, banking, and lending.
There is execution and cost risk here. Building and running AI infrastructure, extended hours options trading, and richer portfolio analytics adds complexity and operating expense. The potential benefit is lower cost per interaction and better retention. The risk is that higher technology and compliance spend appears before revenue benefits and reduces operating leverage.
Charles Schwab's narrative projects US$36.3b revenue and US$15.0b earnings by 2029. This is based on analysts using a 10.3% yearly revenue growth rate and an earnings increase of about US$4.7b from US$10.3b today.
Uncover why Charles Schwab's fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest ranked analysts lean on weaker net interest margin as the key risk for Charles Schwab, which sits in direct tension with today’s AI, crypto, and extended hours upgrades that could influence client cash behavior. Those cautious views were built on revenue reaching about US$34.4b and earnings of roughly US$13.7b by 2029 before this news, so you can see how far opinions already differ. Use this spread in expectations as a prompt to compare several narratives and decide which assumptions around interest income and funding stability feel more realistic to you if these new tools shift how clients use Schwab’s platform.
Explore 3 other Charles Schwab fair value estimates, including one that suggests it could be worth just $116.86!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Charles Schwab research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Charles Schwab. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Charles Schwab's overall financial health at a glance.
Looking for more investment ideas beyond Charles Schwab?
If the Charles Schwab story has you thinking about portfolio upgrades, it can help to scan a few focused shortlists where the heavy lifting has already been done on balance sheets, cash flows, and potential income streams.
- If capital preservation sits high on your priority list, start with a 29 resilient stocks with low risk scores that screens strongly on stability metrics and risk scores.
- For those hunting for opportunities where price and quality look out of sync, line up your watchlist against a curated 34 high quality undervalued stocks that already clears basic balance sheet and earnings hurdles.
- Income focused investors can zero in on potential cash generators by reviewing a 6 dividend fortresses that combines higher yields with a focus on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com