
Madison Square Garden Entertainment (MSGE) Returned To Profit, Is It Still Undervalued?
Madison Square Garden Entertainment (MSGE) drew fresh attention after first quarter results showed revenue of US$217.13 million and net income of US$8.91 million, compared with a loss in the same period a year earlier.
At a share price of US$79.49, Madison Square Garden Entertainment has seen a 46.28% year to date share price return. The 1 year total shareholder return of 72.80% and 3 year total shareholder return of 159.43% suggest strong momentum building behind the story despite a 6.33% share price return decline over 90 days.
Scan how Madison Square Garden Entertainment compares with other entertainment and media stocks showing strong price and earnings momentum using our curated 19 high quality undiscovered gems.
After that kind of swing from loss to profit and a strong share price run this year, the real test for Madison Square Garden Entertainment now is whether the current valuation still leaves enough potential upside for new money to feel comfortable buying in.
Most Popular Narrative: 13% Undervalued
On the analyst consensus Narrative on Simply Wall St, Madison Square Garden Entertainment screens as undervalued, with a fair value of $91.63 against a last close of $79.49. That gap rests on a detailed view of event volumes, cash generation, and venue bookings rather than broad sector optimism.
The main thing that has to go right is that high event volumes, marquee content like the Christmas Spectacular, and sponsorship and premium hospitality spending continue to offset higher operating and SG&A costs as the company invests in technology and venue upgrades.
The current numbers, including share repurchases and management’s guidance for significant underlying free cash flow in fiscal 2027, imply the share price assumes the company will convert its busy venues and long-dated arena license fees into durable cash generation, with limited disruption from legal and data-privacy risks.
See why 1 investors see Madison Square Garden Entertainment as 13% undervalued.
Result: Fair Value of $91.63 (UNDERVALUED)
Still, legal scrutiny around the large data breach and any sustained rise in operating or SG&A costs could quickly challenge the bullish Madison Square Garden Entertainment narrative.
Find out about the key risks to this Madison Square Garden Entertainment narrative.
Another View: Multiples Paint a Tougher Picture for Madison Square Garden Entertainment
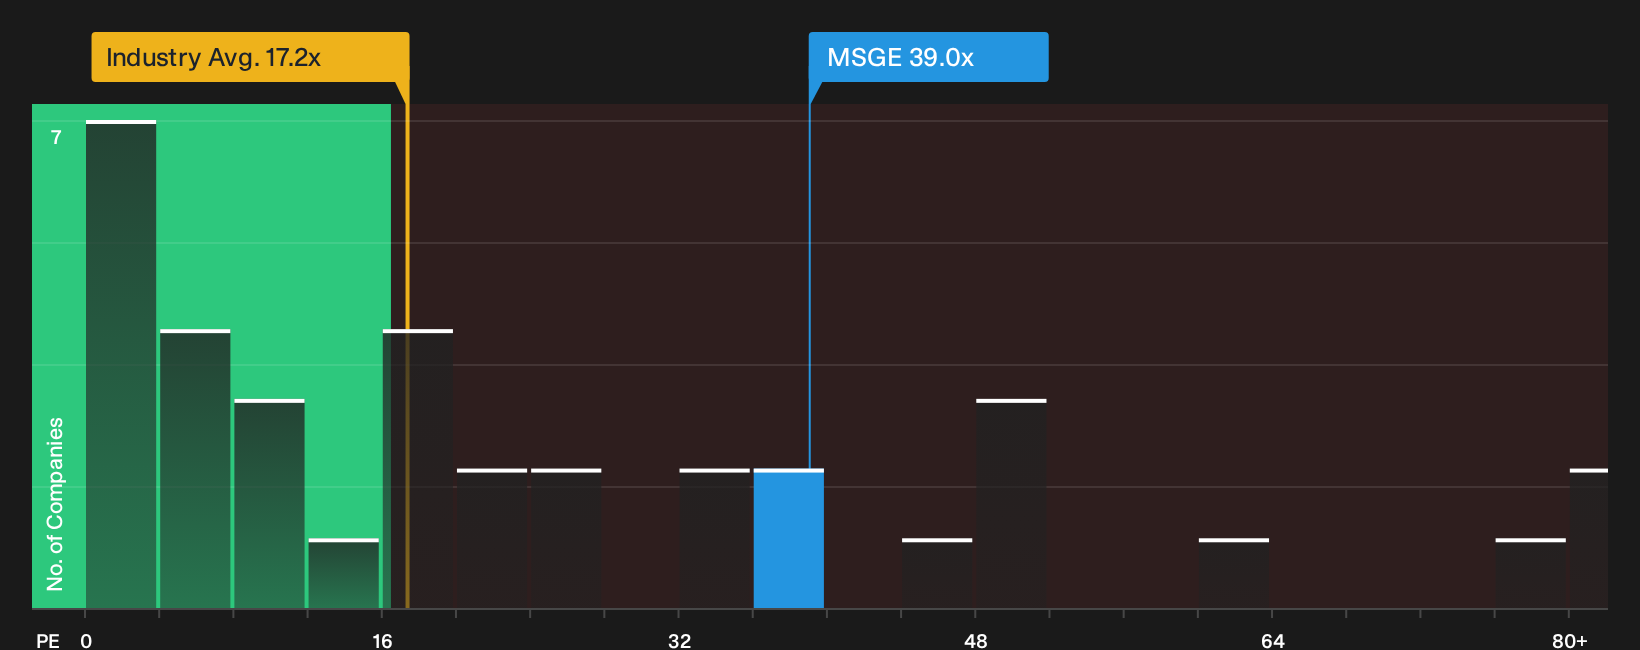
Fair value from the analyst narrative pegs Madison Square Garden Entertainment at $91.63, yet the market is already assigning a rich tag. The stock trades on a P/E of 39x, almost double the fair ratio of 18.7x and well above the US Entertainment industry on 17.2x and peers on 18.2x. That kind of gap suggests investors are paying a premium for execution and balance sheet risk, so the key question is whether you think earnings quality and future returns justify staying this far ahead of the pack.
See what the numbers say about this price in our valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Madison Square Garden Entertainment so far. If you want to move quickly and make your own call, weigh both sides carefully and start by sizing up the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Madison Square Garden Entertainment?
Broaden your watchlist now with a few focused stock sets so you are not relying on just one story when fresh opportunities appear.
- Target resilience with companies that pair healthy finances and steady cash generation using the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced potential by scanning the 34 high quality undervalued stocks where quality and pricing line up more tightly.
- Build a cash-flow focused shortlist through the 6 dividend fortresses so regular income stays on your radar alongside capital gains potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com