
Missed i-80 Gold's Run? What Holders Had To Believe
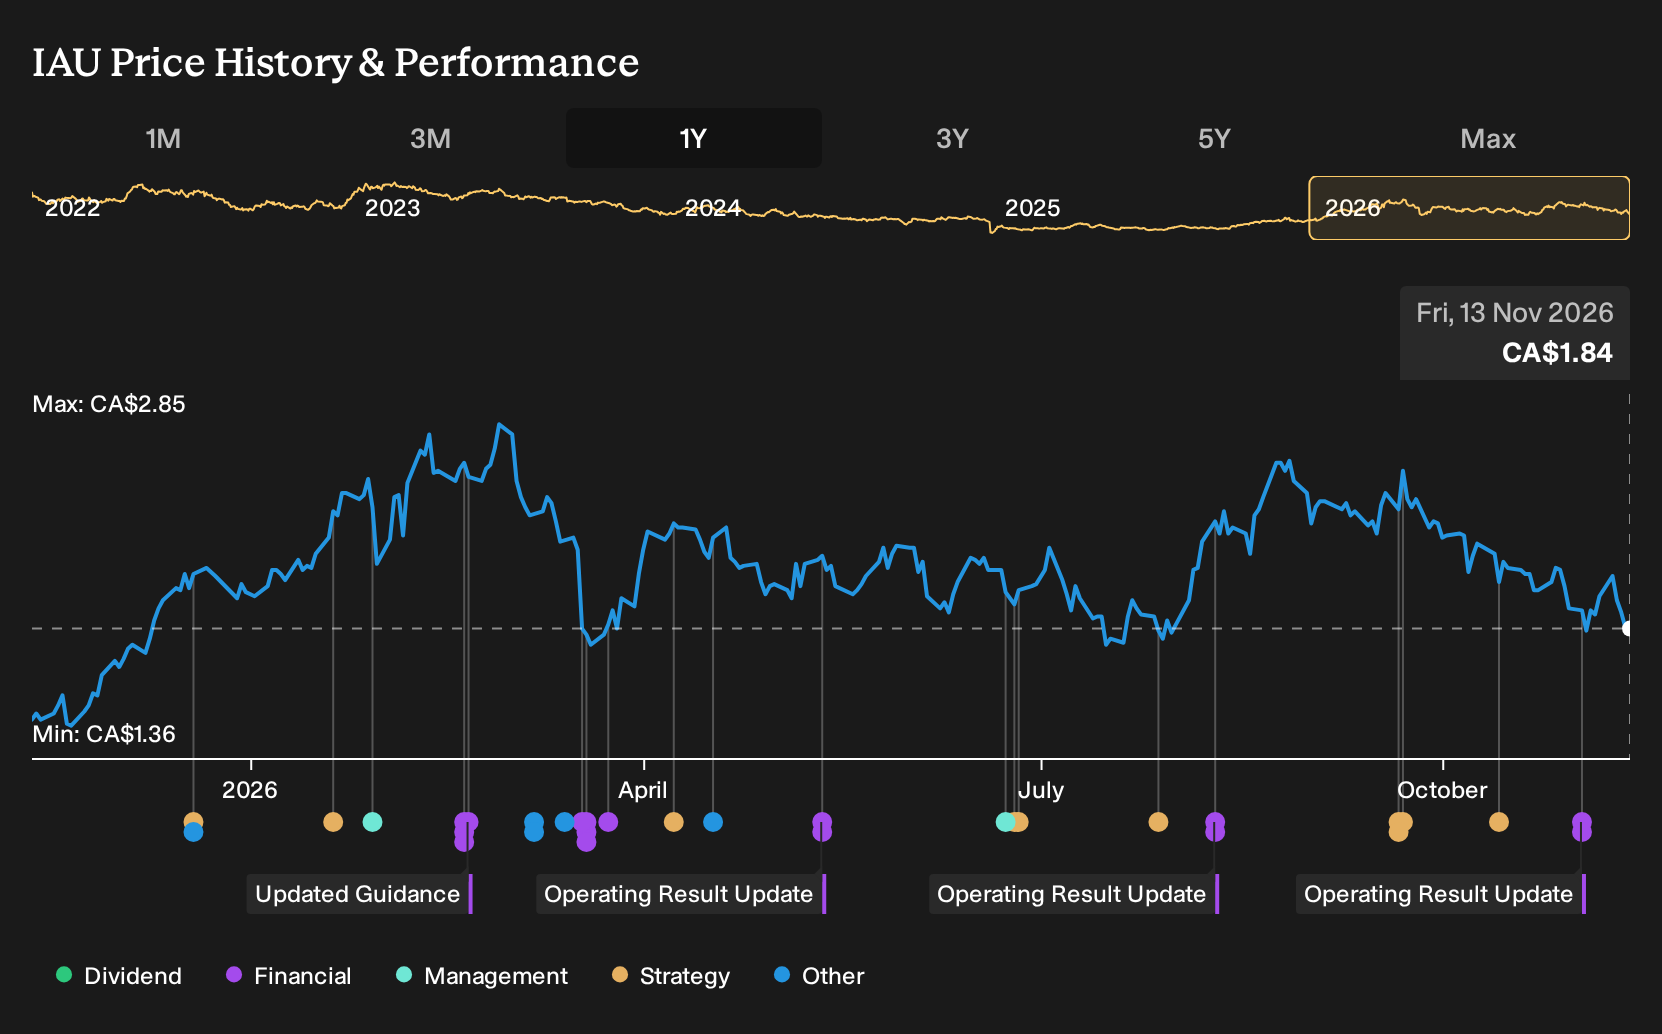
If you had backed i-80 Gold a year ago, the outcome looks straightforward on paper. Investors who held i-80 Gold over the past year are up 32.4%, including dividends. The decision at the time was anything but simple though, with analysts split between a higher fair value and a sharply lower one as they weighed Nevada project ambitions, heavy funding needs, and regulatory risk. If you were choosing on 13 November 2025, which of those trade offs would have mattered most?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
This theme extends beyond i-80 Gold. See which of 33 elite gold producer stocks may still merit a closer look.
The Two i-80 Gold Stories Investors Had To Choose Between
The shares cost CA$1.42 at the start of the period, and anyone weighing up i-80 Gold then had to choose between two very different stories.
The bullish narrative saw Fair Value at CA$2.28, based on assumptions that revenue would climb 72.4% a year and that margins would move from a heavy loss to a 17.3% profit level within about three years.
The more cautious view set Fair Value at CA$1.05 and focused on Nevada concentration risk and large funding needs, with revenue growth assumptions of 57.0% a year and a future P/E of 11.7x.
What The Results Changed For The i-80 Gold Story
The clearest update for i-80 Gold was Q3 2026, where total revenue was US$32.728m compared with US$32.019m a year earlier, while the firm still reported a loss and net margin moved further into negative territory from -130.8% to -147.7%. That challenged the bullish profitability path and gave the cautious case more weight.
The lesson is simple. When a thesis leans on fast margin repair, you track net margin and absolute profit each reporting date and test them against the story, not the share price.
What You Are Paying For In i-80 Gold Now
Today i-80 Gold trades at CA$1.84, after a 32.4% gain over the past year. The analyst consensus Narrative on Simply Wall St places Fair Value above that level and frames the gap as a question about how reliably Nevada plans turn into cash generation.
At this price, you are effectively judging whether Lone Tree and the broader Nevada hub can ramp as envisioned and convert heavy current spending into sustained, higher margin production that the Narrative argues is not yet fully credited.
"Analysts expect i-80 Gold to build on its Nevada growth plan and new processing capacity, with the goal that higher output and improved cash margins can increasingly feed through to revenue and operating cash flow over the next several years. The main factor that has to go right is execution of the Lone Tree hub and Nevada mine build out, including on-time refurbishment of the autoclave, delivery of feasibility studies, and conversion of drilled resources into long-lived, profitable production."
The price and this Narrative do not agree. → Uncover what this Narrative says i-80 Gold is actually worth
Looking Beyond i-80 Gold
Once you understand i-80 Gold, it is natural to look nearby in metals.
Gold projects often hinge on funding cycles, while silver producers face different demand drivers.
One producer concentrates on silver output and related by products, relying on efficient established mines and cautious ramp up of newer assets.
Exploration results, mine life and firm cost control shape how its story develops.
If precious metals continue attracting capital, this operator may confront some notably complex decisions.
One Narrative has put that dependency into a written case. → See the silver company one Narrative values 69% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com