
3 Dividend Stocks That Could Hold Up Better If Fed Rates Stay Higher
Investors are watching the Federal Reserve hint at tighter policy again, with inflation still described as “uncomfortably” above target and futures now fully pricing in a December hike. That kind of backdrop can punish rate sensitive growth stories and push attention toward steadier dividend payers. This article walks through three stocks exposed to this macro shock from our High-Quality Dividend Value screener and explains why each one may warrant closer examination at this time.
The three stocks that follow are just a sample set, and the full screen surfaced 20 more dividend payers with equally detailed stories that are not covered here. If you want to identify, compare, and analyze which ideas best fit your watchlist, head straight to the High-Quality Dividend Value Stocks screener.
McCormick (MKC)
Overview: McCormick is a global consumer staples group that produces and sells herbs, spices, seasonings, condiments and flavor solutions to retailers and foodservice customers worldwide.
Operations: McCormick generates about US$4.6b from its Consumer segment and US$3.1b from Flavor Solutions, with revenue primarily tied to branded flavor products.
Market Cap: US$12.6b
McCormick fits the High-Quality Dividend Value Stocks theme as a consumer staples business with recurring demand and global reach. The bullish analyst Narrative on Simply Wall St states that the key focus is how those cash flows are slowly being reweighted away from the U.S. toward faster growing regions.
"Consumer EMEA has recorded 11 consecutive quarters of positive volume, with recent 5% organic growth supported by both volume and pricing, which points to a developing second consumer growth pillar for McCormick that can widen the revenue base and reduce earnings reliance on the U.S."
What happens to McCormick’s income profile if one unseen pressure subtly shifts how much of that expanding profit pool actually reaches shareholders?
That pressure point is exactly where the full narrative for McCormick digs in, unpacking how McCormick’s payout story could be quietly accelerating or getting masked by regional mix shifts.

A. O. Smith (AOS)
Overview: A. O. Smith manufactures essential residential and commercial water heaters, boilers and water treatment systems, aligning with the screener’s focus on cash-generative, dividend-oriented industrials.
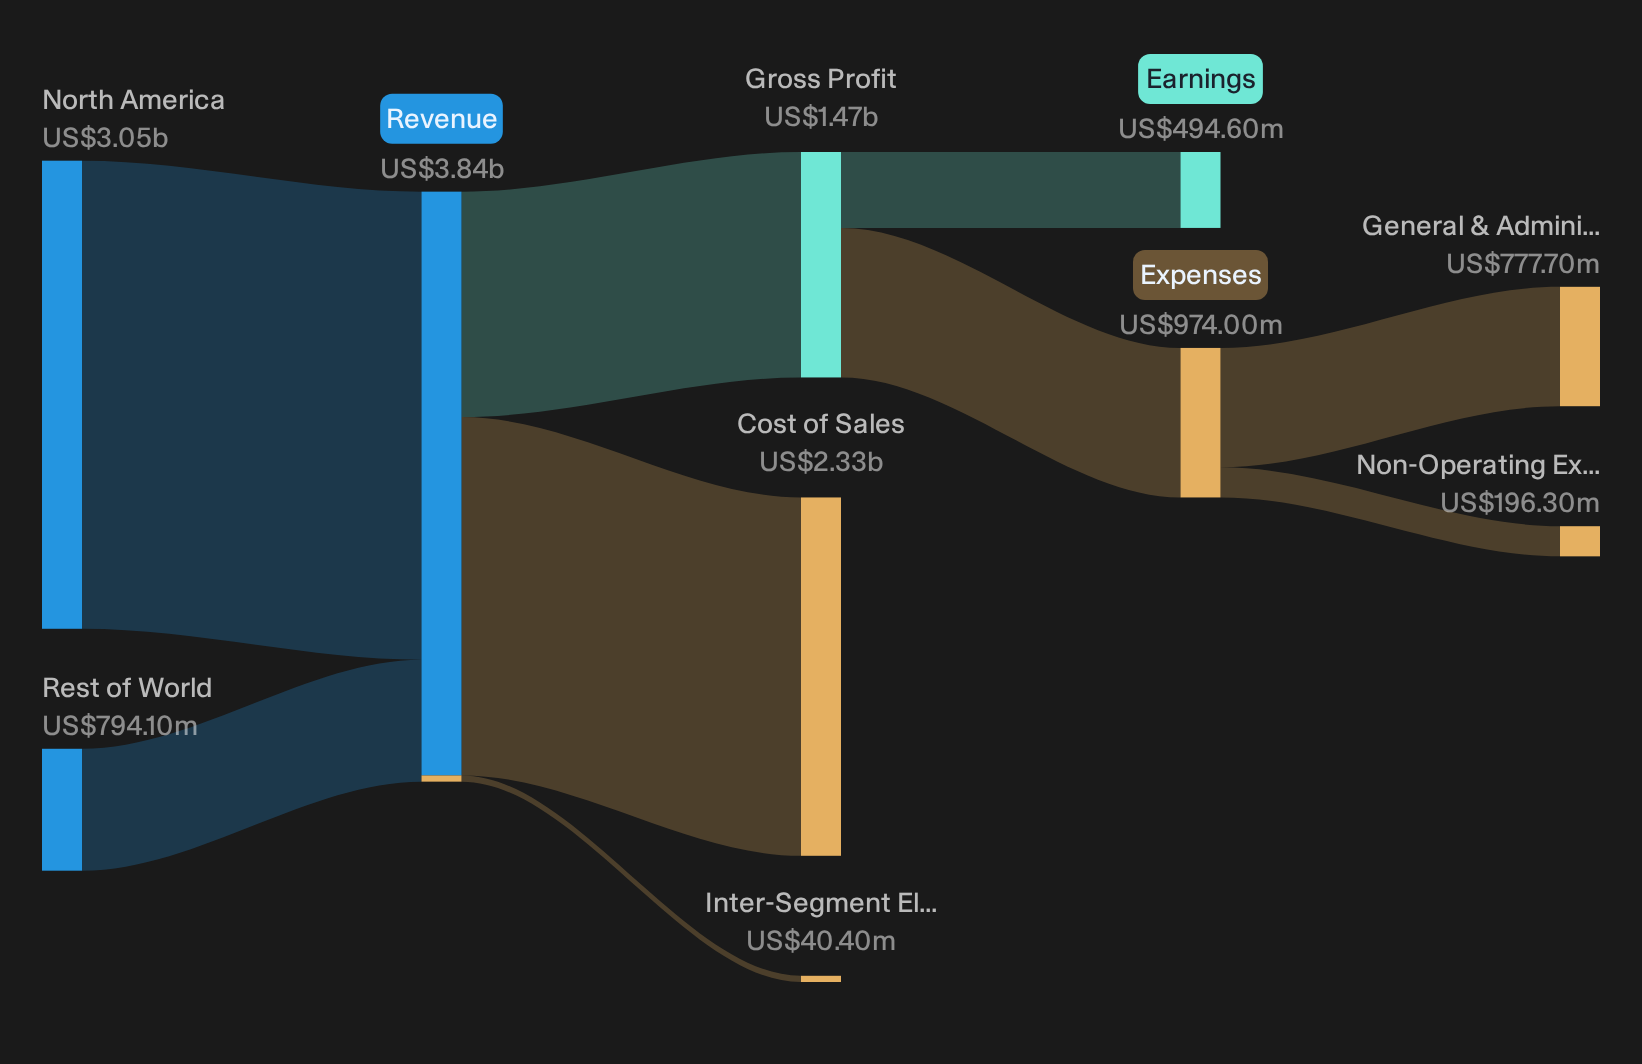
Operations: A. O. Smith generates about US$3.0b of revenue from North America and roughly US$800 million from the Rest of World, after eliminations.
Market Cap: US$8.6b
Where McCormick leans on pantry staples, A. O. Smith taps into everyday water heating and treatment. The analyst consensus Narrative on Simply Wall St highlights it as a classic replacement-driven dividend story that can matter even more when higher rates weigh on growth stocks.
"Increasing regulatory focus on energy efficiency and sustainability in water heating is prompting A. O. Smith to accelerate investment and launch new high efficiency and smart products such as condensing boilers and tankless water heaters, which could support future revenue and gross margin growth as higher priced systems gain share."
The twist for A. O. Smith is what happens to that margin and dividend profile if a single cost and pricing assumption stops holding.
If that assumption breaks, the full full narrative for A. O. Smith shows where A. O. Smith’s pricing power, input costs and dividend ambitions could be quietly decoupling.
Lineage (LINE)
Overview: Lineage is a global temperature-controlled warehouse REIT that runs refrigerated logistics facilities supporting food and beverage producers, retailers and distributors.
Operations: Lineage generates about US$4.0b from Global Warehousing and roughly US$1.3b from Global Integrated Solutions, centered on cold-chain logistics services.
Market Cap: US$9.0b
Lineage fits the High-Quality Dividend Value Stocks theme as a large cold-storage REIT where mission-critical food logistics can support occupancy and rental income, and Ontological, an investor in the Simply Wall St Community, argues the real story now is how that income profile reacts to a more aggressive Federal Reserve.
"Risks facing the cold-storage giant are the Federal Reserve’s recent rate hike to 3.75 to 4.00% in September 2026, with projections of another increase to 4.25%, which raises financing costs for REITs like Lineage."
What investors are really weighing is how one unresolved pressure on funding costs reshapes the gap between Lineage’s payout and its cash engine.
To see how that funding squeeze could be accelerating or masking Lineage’s real income engine, read the full narrative for Lineage for the full risk and payout story.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time the crowd notices a breakout or a dropping entry point, the sweet spot can be gone. Scan these curated lists and act now.
- Chase early momentum in niche miners before sentiment flips by reviewing the 33 elite gold producer stocks, which screens for producers already passing strict financial filters.
- Spot under the radar growth with real cash backing it by scanning the 43 profitable AI stocks that aren't just burning cash, built around smaller players already funding their own AI push.
- Track mission critical infrastructure plays where electrification pressure meets balance sheet strength by using the curated 44 power grid technology and infrastructure stocks, focused on grid and transmission specialists.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com