
Tyson Foods posts better-than-expected sales in Q3 CY2026
Meat company Tyson Foods (NYSE:TSN) reported calendar Q3 2026 [fiscal Q4 2026] results beating Wall Street’s revenue expectations, with revenue up 5.2% year on year to $14.59 billion. Its non-GAAP profit of $0.61 per share was 1.7% above analysts’ consensus estimates.
For more on Tyson Foods, read our free full research report.
Tyson Foods Q3 CY2026 highlights:
- Revenue $14.59 billion vs S&P analyst consensus of $14.22 billion (5.2% year-on-year growth, 2.6% beat)
- Adjusted EPS $0.61 vs S&P analyst consensus of $0.60 (1.7% beat)
- Operating margin 0%, down from 1.1% in the same quarter last year
- Free cash flow margin 5.1%, up from 1.8% in the same quarter last year
- Sales volumes rose 6.8% year on year (-1.6% in the same quarter last year)
- Market capitalization $20.64 billion
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can report a good quarter or two, but the best consistently grow over the long term.
With $56.42 billion in revenue over the past 12 months, Tyson Foods is one of the most widely recognized consumer staples companies. Its influence over consumers gives it negotiating leverage with distributors, enabling it to choose where it sells its products, an advantage many companies lack. However, its scale is a double-edged sword because there are only so many big store chains to sell into, making it harder to find incremental growth. For Tyson Foods to boost its revenue, it likely needs to adjust its prices, launch new offerings or expand in foreign markets.
Tyson Foods grew its revenue at a sluggish 2.2% compounded annual growth rate over the last three years, but on the positive side, consumers bought more of its products.
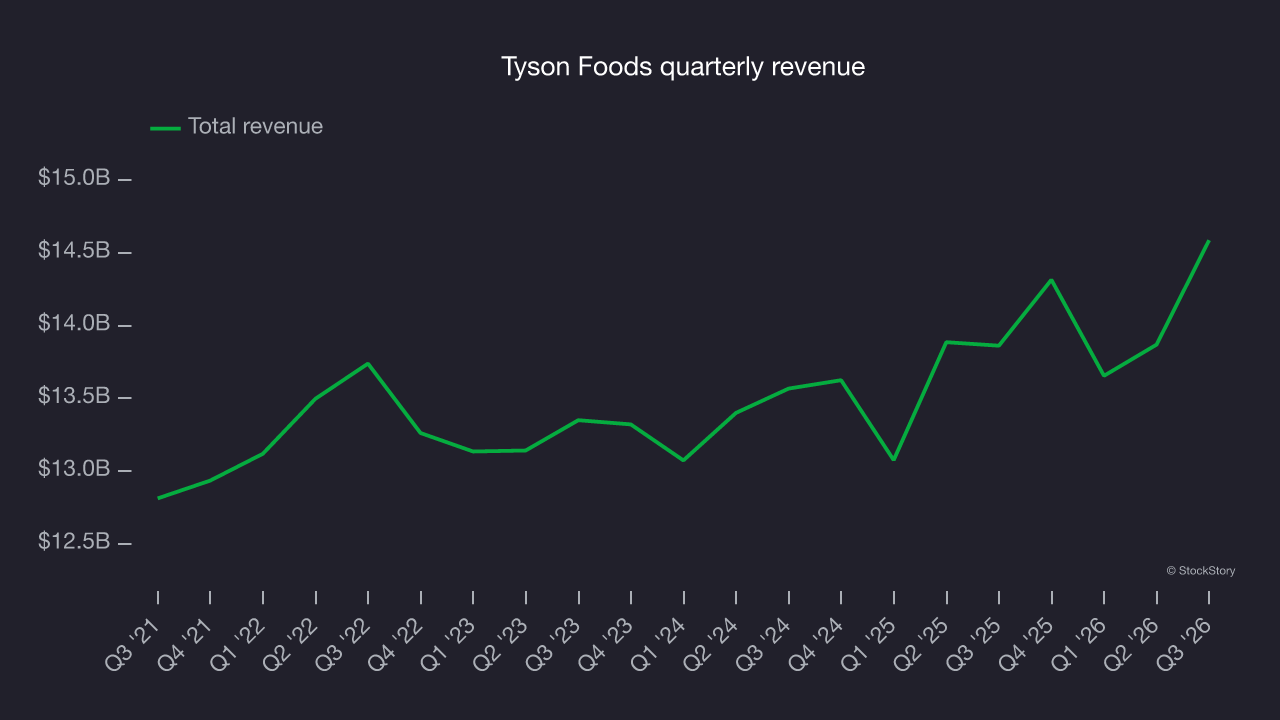
This quarter, Tyson Foods reported year-on-year revenue growth of 5.2%, and its $14.59 billion in revenue exceeded Wall Street’s consensus estimates by 2.6%.
Looking ahead, sell-side analysts expect revenue to decline by 1.4% over the next 12 months, according to S&P, a deceleration versus the last three years. This projection is underwhelming and indicates its products will see some demand headwinds.
Volume growth
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is critical to a staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
Tyson Foods’s quarterly sales volumes have, on average, stayed about the same over the last two years. This stability is normal because the quantity demanded for consumer staples products typically doesn’t see much volatility. 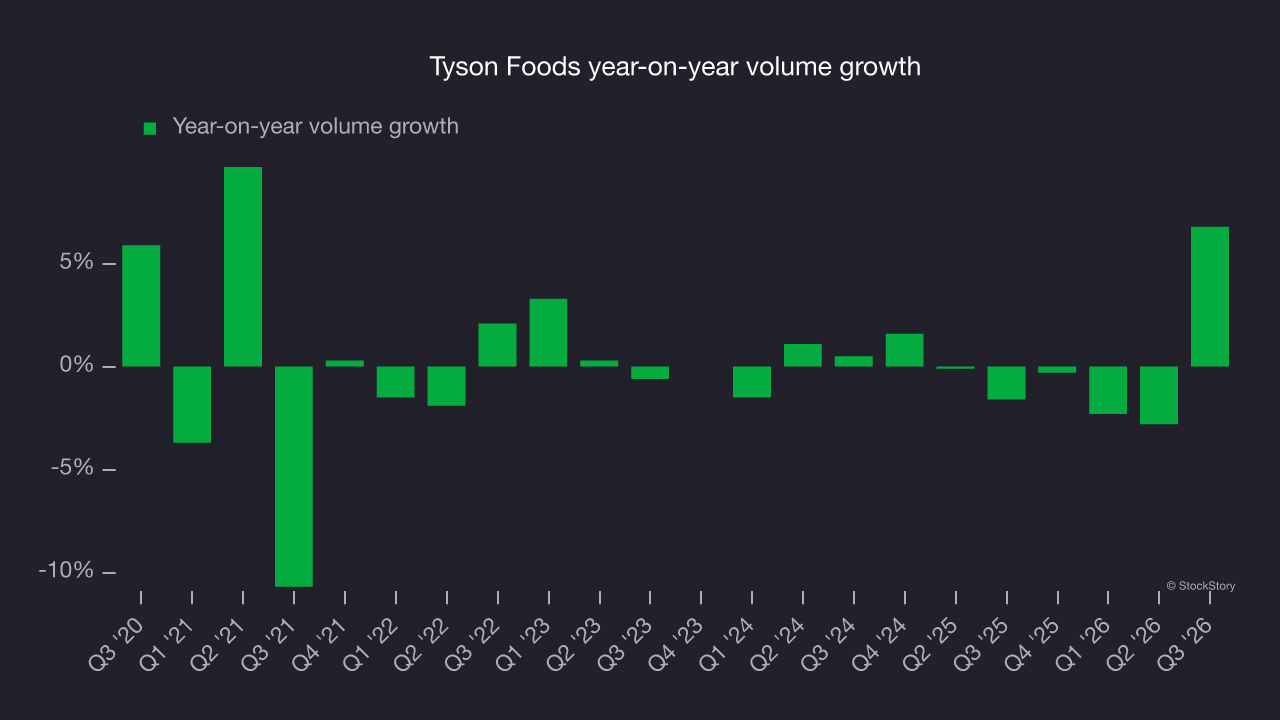
In Tyson Foods’s Q3 2026, sales volumes surged 6.8% year on year. This marked an acceleration from its historical levels, a positive signal.
Key takeaways from Tyson Foods’s Q3 results
Tyson Foods’ revenue beat analysts’ consensus estimates, giving the quarter a key positive, but gross margin fell short of expectations. The results were mixed overall. Shares remained flat at $59.35 immediately after the report.
For investors considering Tyson Foods at its current price, the latest quarter is only one part of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. Read the full research report here (it’s free).