
Did TPU Orders Just Shift Google Stock's Investment Narrative?
- Alphabet has been expanding its AI and cloud footprint, with Google TPUs securing multi year orders from leading AI labs and the Gemini 4 Hydrogen model priced well below some rivals for automation workloads.
- The same in house chips that power Google services are now a product in their own right, turning AI infrastructure spending into a potential external revenue engine for Alphabet.
- This article examines how Alphabet's investment narrative is affected by its growing TPU demand as AI infrastructure spending accelerates.
Alphabet Investment Narrative Recap
To own Alphabet, you need to believe the search and YouTube cash engine can fund a long AI and cloud buildout without crushing free cash flow. According to tripledub, a Simply Wall St Community investor who wrote the Narrative, the debate is whether that spending earns more than it costs over time. The near term catalyst is proof that Gemini and TPUs convert into higher quality Google Cloud and AI usage rather than just higher capex.
The biggest risk today still sits in that same AI infrastructure bill. Alphabet is leaning into heavy capital outlays and an $80b equity raise while free cash flow already feels pressure. Recent moves in drones, energy prepay deals, and Anthropic exposure do not obviously change that risk reward balance yet.
The clearest link to the current AI infrastructure story is the report that OpenAI and Anthropic have placed large multi year orders for Alphabet TPUs, with shipment visibility to 2029. That kind of backlog can help offset some concern that the chip and data center build is a “field of dreams” project with no paying tenants.
It still leaves execution risk. Alphabet must deliver those TPU systems on time and keep them cost competitive as rivals try to undercut pricing or shift architectures. For you as a shareholder, the practical question is whether this external demand shortens the payback period on the heavy capex that tripledub worries could otherwise drag margins and cash returns lower.
Tripledub estimates Alphabet’s narrative fair value at $198.53 per share by modeling a middle-road scenario that combines 14.0% annual revenue growth with a future profit margin of 26.0%. It treats that mix of growth and profitability as a reasonable base case rather than a best-case outcome.
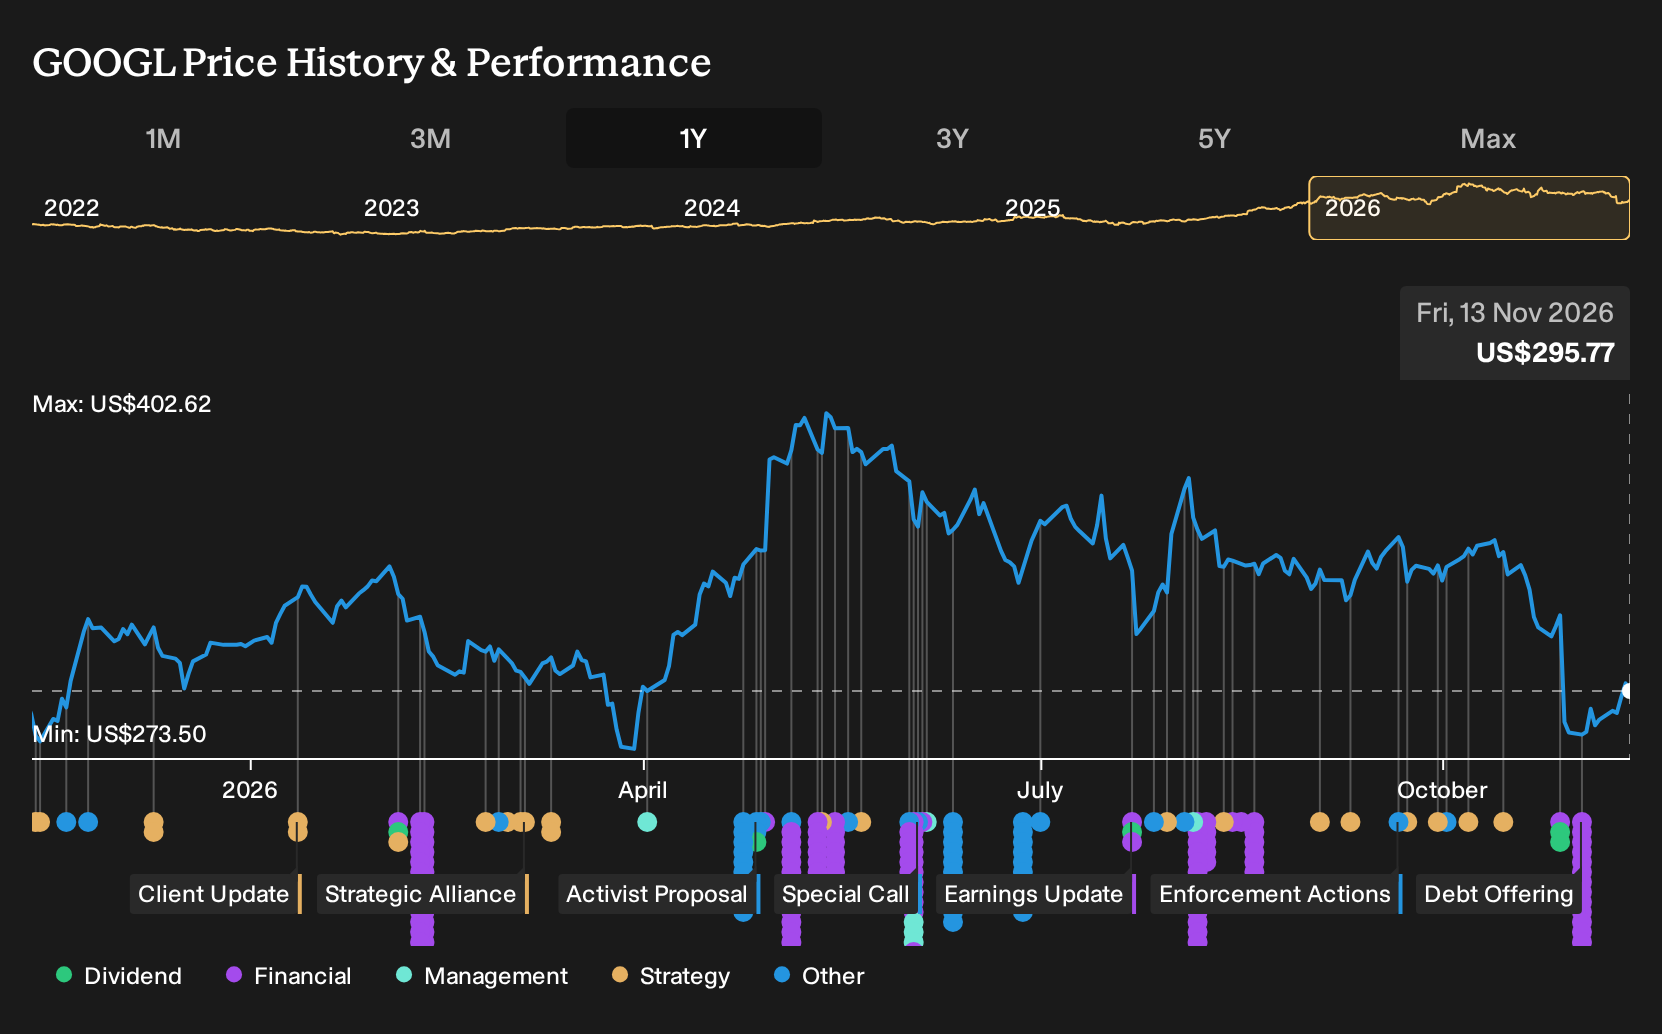
Uncover why Alphabet's fair value indicates a 30% potential downside to its current price, resulting in a premium that leaves little room for error.
Exploring Other Perspectives
Some of the lowest ranked analysts put regulatory and compliance risk at the center of their Alphabet story. They were already assuming revenue of about US$746.6b and earnings of US$146.7b by 2029, with margins compressing sharply. That is a much harsher view than the baseline. The fresh TPU order news could eventually force both camps to rethink their assumptions.
Explore 66 other Alphabet fair value estimates, including one that suggests as much as 30% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Alphabet research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alphabet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alphabet's overall financial health at a glance.
Looking for more investment ideas beyond Alphabet?
If the Alphabet AI narrative has sharpened your thinking about where the next wave of value might come from, broaden that lens across the market. The Simply Wall St Screener can help you surface stocks that fit very different risk and return profiles without relying on headlines or hype.
- Prefer businesses that already generate cash and may be priced below what their fundamentals suggest? Start with a focused set of 37 high quality undervalued stocks that combine quality metrics with attractive valuations.
- If capital preservation comes first for you, consider companies that score well on balance sheet strength and financial resilience, using our list of solid balance sheet and fundamentals (24 results) as a starting filter.
- For readers looking for under the radar opportunities, narrow the field to a curated 19 high quality undiscovered gems that pair solid fundamentals with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com