
Disney beats Q3 CY2026 sales expectations
Global entertainment and media company Disney (NYSE:DIS) announced better-than-expected revenue in calendar Q3 2026 [fiscal Q4 2026], with revenue up 15.5% year on year to $25.95 billion. Its non-GAAP profit of $1.77 per share was 5.5% above analysts’ consensus estimates.
For more on Disney, read our free full research report.
Disney Q3 CY2026 highlights:
- Revenue $25.95 billion vs S&P analyst consensus of $25.12 billion (15.5% year-on-year growth, 3.3% beat)
- Adjusted EPS $1.77 vs S&P analyst consensus of $1.68 (5.5% beat)
- Operating margin 19.2%, up from 11.9% in the same quarter last year
- Free cash flow margin 18.6%, up from 11.4% in the same quarter last year
- Market capitalization $205 billion
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Disney’s revenue grew at a weak 8.7% compounded annual growth rate, falling short of the consumer discretionary sector standard.
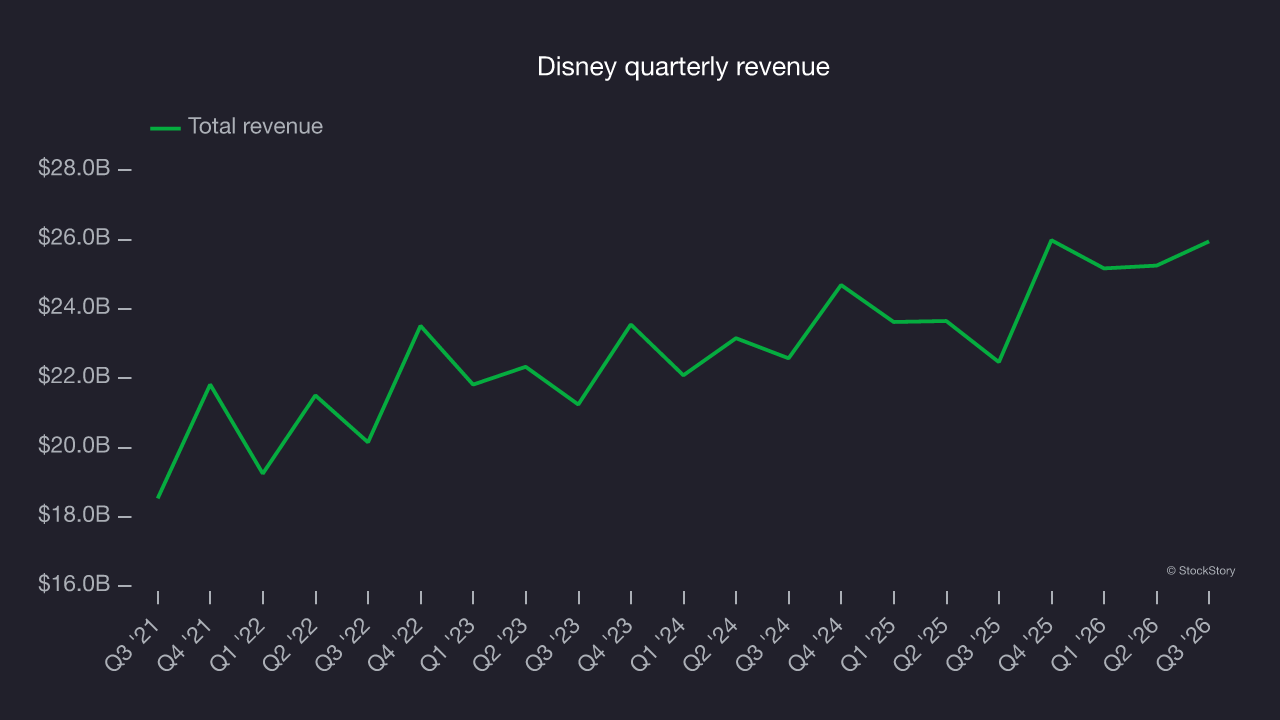
Long-term growth matters most, but within consumer discretionary, a stretched historical view may miss a company riding a successful new product or trend. Disney’s recent performance shows its demand has slowed as its annualized revenue growth of 5.8% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 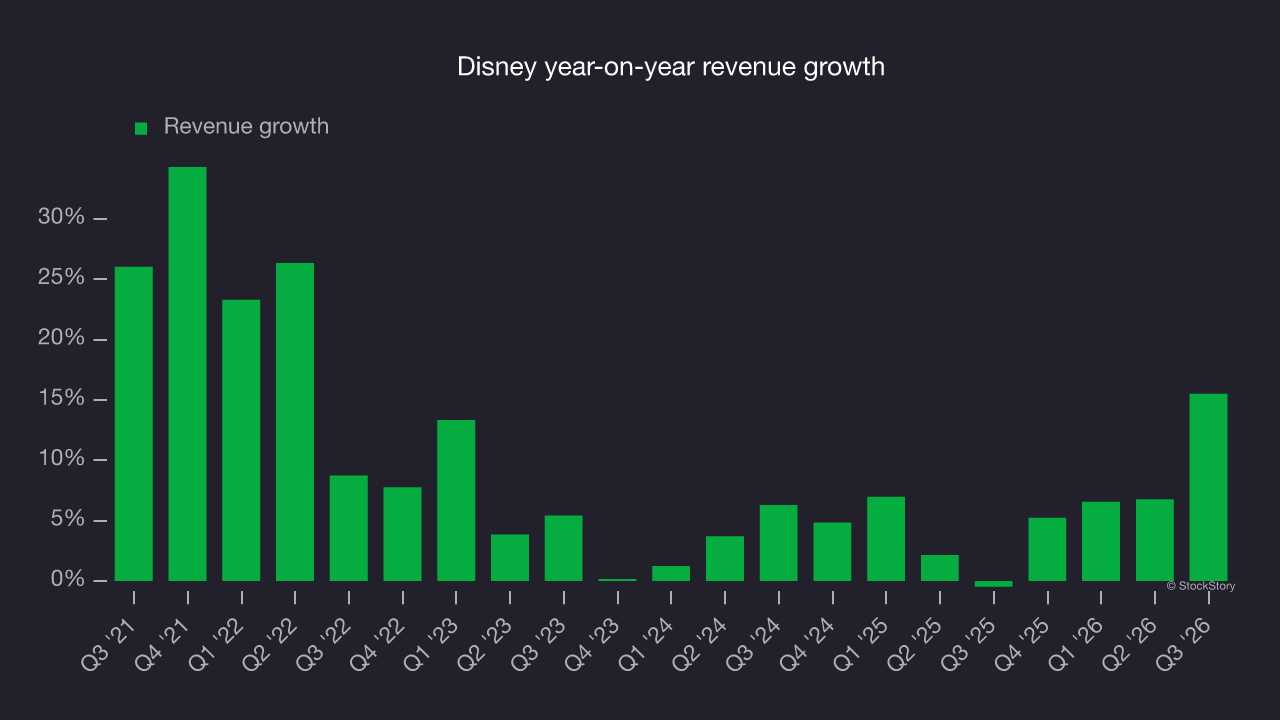
Disney also breaks out the revenue for its three most important segments: Entertainment, Sports and Experiences, which are 45.8%, 17.8% and 38.9% of revenue. Over the last two years, Disney’s revenue in all three segments increased. Its Entertainment revenue (movies, Disney+) averaged year-on-year growth of 6.5% while its Sports (ESPN, SEC Network) and Experiences (theme parks) revenue averaged growth of 3.1% and 7.7%. 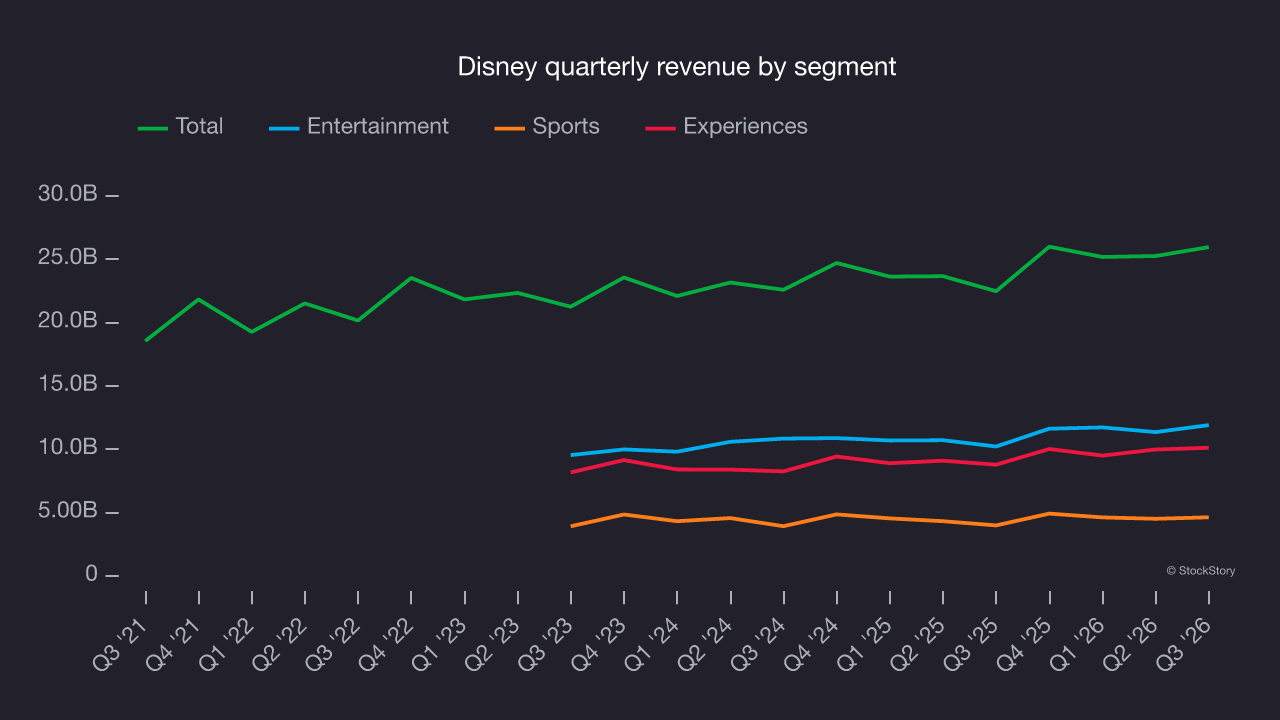
This quarter, Disney reported year-on-year revenue growth of 15.5%, and its $25.95 billion of revenue exceeded Wall Street’s consensus estimates by 3.3%.
Looking ahead, sell-side analysts expect revenue to grow 3.7% over the next 12 months, according to S&P, a slight deceleration versus the last two years. This projection is underwhelming and indicates its products and services will face some demand challenges.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Disney’s operating margin has risen over the last 12 months and averaged 16.2% over the last two years. The company’s improved efficiency is a positive sign, but its suboptimal cost structure means profitability remains thin for a consumer discretionary business.
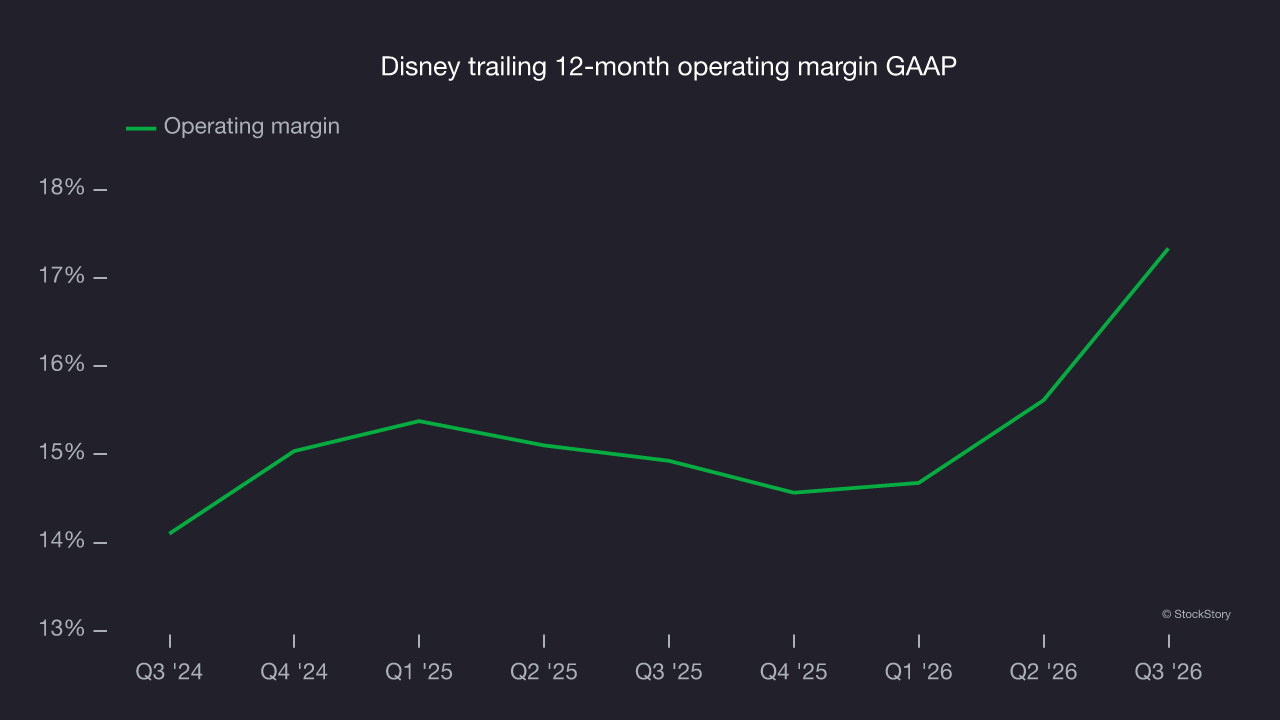
This quarter, Disney generated an operating profit margin of 19.2%, up 7.3 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Disney’s EPS grew at a 25.1% compounded annual growth rate over the last five years. On the positive side, this outpaced its 8.7% annualized revenue growth, indicating the company became more profitable on a per-share basis as it expanded.
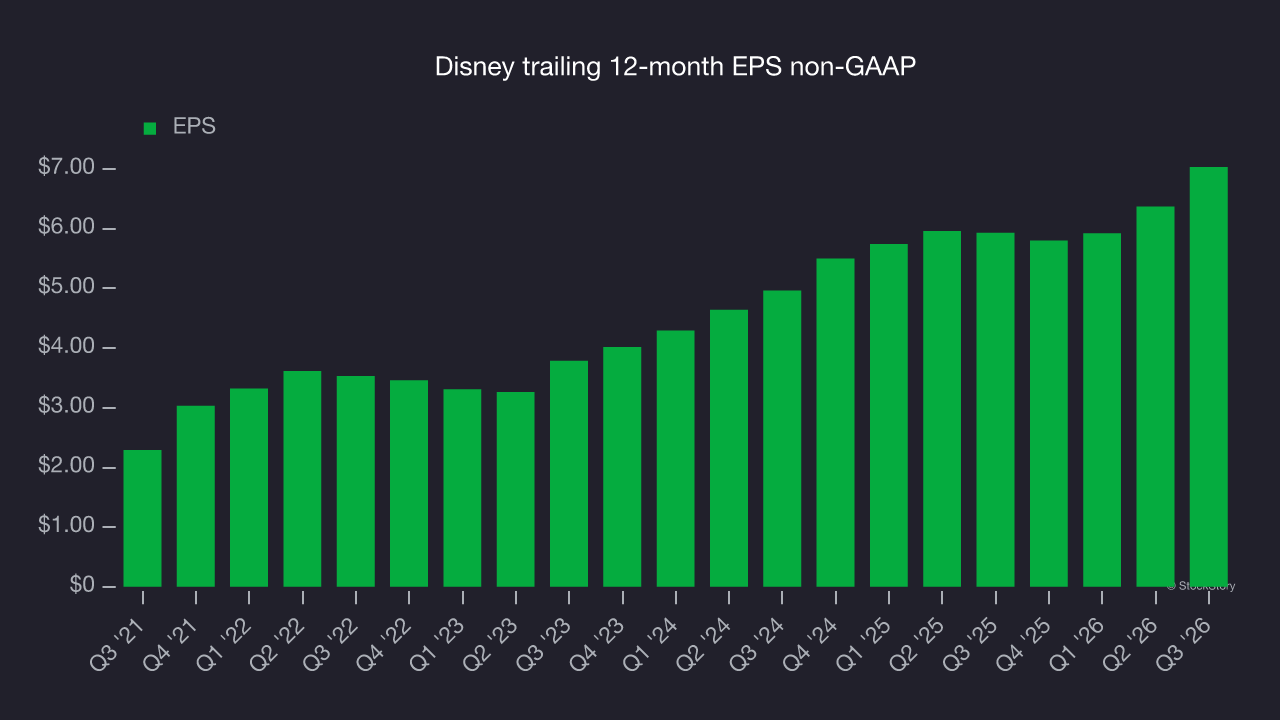
In Q3, Disney reported adjusted EPS of $1.77, up from $1.11 in the same quarter last year. This result beat analysts’ consensus estimates by 5.4%. Over the next 12 months, Wall Street expects Disney’s full-year EPS to grow 6.5% from $7.03 to $7.48, according to S&P.
Key takeaways from Disney’s Q3 results
Revenue and EPS both topped Wall Street’s consensus estimates, making this a solid quarter for Disney. Shares edged higher 1% to $120.00 immediately after the results.
Disney had a solid quarterly earnings result, but that alone doesn’t make the stock a good investment. When making that decision, consider valuation and business quality as well as the latest earnings. For more on Disney, read our full research report here (it’s free).