
Why Honeywell International (HON) Is Back In The Spotlight
Honeywell International (HON) is back in focus after its LenelS2 OnGuard software underpinned a major overhaul of Vanderbilt Health’s campus-wide access control, covering thousands of doors and hundreds of thousands of users.
Recent trading tells a mixed story for Honeywell International. The share price has slipped 4.1% over the past week but still shows a 3.6% gain over 30 days. Total shareholder return of 10.9% over one year and 23.0% over three years points to momentum that has been built over a longer stretch as investors weigh fresh product launches, access control wins like Vanderbilt Health, and the company’s raised 2026 guidance against shorter term swings.
Scout other building automation and security plays riding similar demand by checking our hand picked 91 robotics and automation stocks alongside Honeywell International’s latest access control win.Honeywell International has already rewarded patient holders over the past year, yet the recent pullback and raised 2026 targets put fresh attention on the next leg. Does the current price still leave meaningful upside on the table?
Most Popular Narrative: 15% Undervalued
Honeywell International last closed at $218.96, while the analyst consensus Narrative on Simply Wall St points to a fair value of $257.61 using an 8.55% discount rate and detailed revenue and earnings forecasts. That gap frames a story where execution in automation and software has to work hard against falling revenue and profit assumptions baked into the model.
The company is reallocating commercial resources and new product investment toward eight higher growth verticals such as data centers, LNG, life sciences and semiconductors, with high growth verticals already representing about 20% of the mix and targeted to reach 25%, which management connects to 4% to 6% organic growth and higher segment margins.
See why 132 investors see Honeywell International as 15% undervalued.
Result: Fair Value of $257.61 (UNDERVALUED)
Still, the story around Honeywell International only holds if restructuring costs stay contained and cyclical exposure in areas like oil and gas does not drag earnings below current analyst assumptions.
Find out about the key risks to this Honeywell International narrative.
Another View On Honeywell International
The narrative fair value presents Honeywell International as 15% undervalued, yet Simply Wall St’s DCF model offers a different perspective. On that future cash flow view, HON at $218.96 trades above an estimated value of $169.09, which frames the shares as overvalued. Which lens do you trust more when cash flow and multiples disagree?
Look into how the SWS DCF model arrives at its fair value.
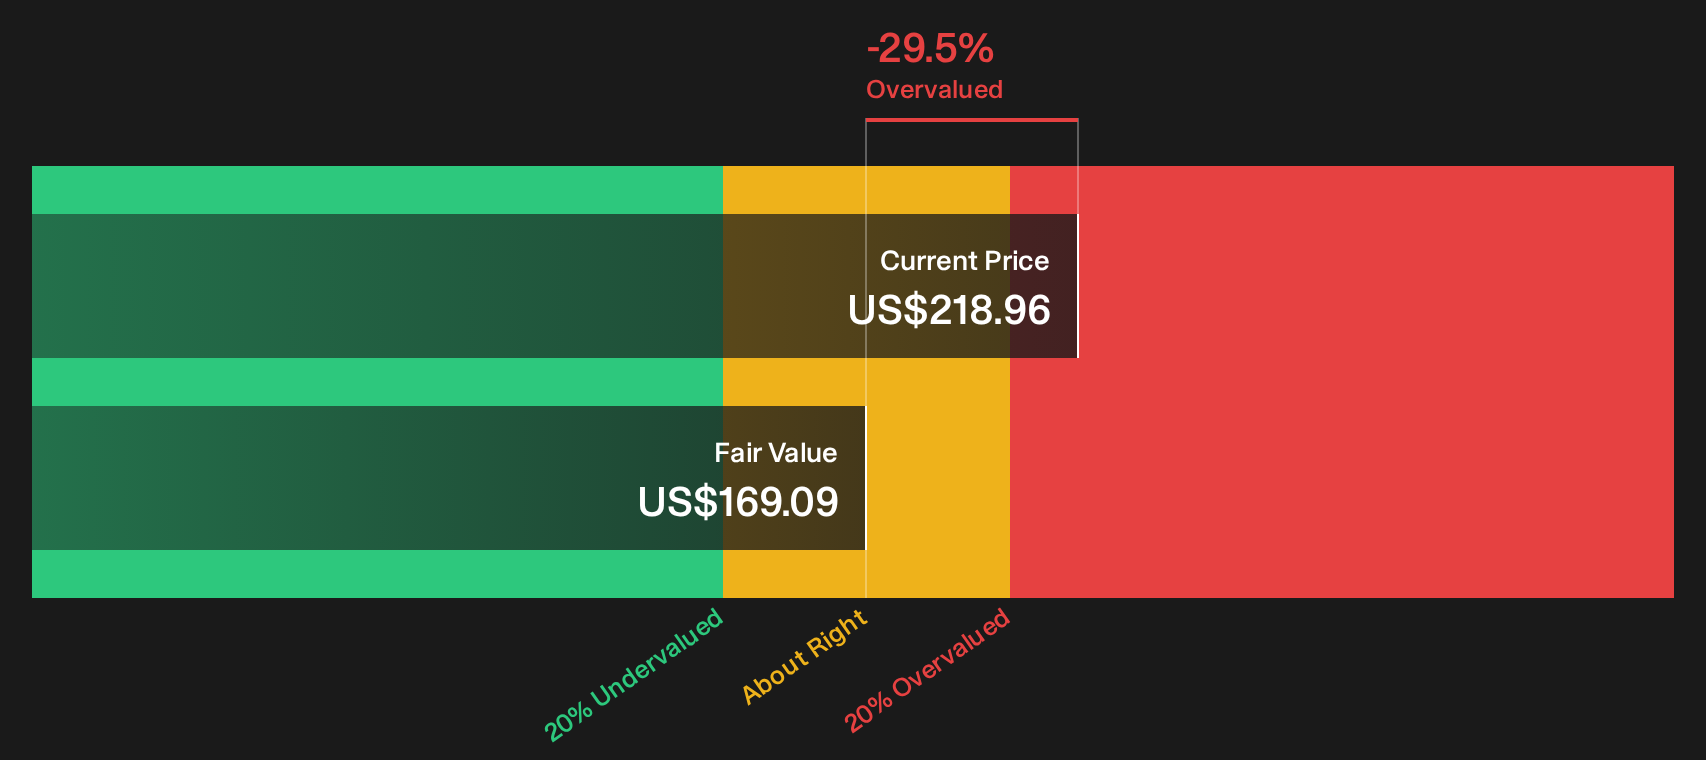
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Honeywell International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 37 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Honeywell International’s value case and risk profile only matter if you act on them. Pressure test the data yourself, weigh both the upside and the red flags, and ground your stance in 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Honeywell International?
If you stop at Honeywell International, you risk missing other potential opportunities that fit your style, your risk tolerance, and your return expectations.
- Target stronger value potential by checking companies on the 37 high quality undervalued stocks that combine solid fundamentals with what may be mispriced market expectations.
- Prioritise resilience and capital strength by scanning the list of solid balance sheet and fundamentals (24 results) so you are not caught off guard by weak financial foundations.
- Hunt for lesser known opportunities by reviewing the 18 high quality undiscovered gems before other investors start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com