
Cheniere Energy (LNG) Debt Raise Keeps Its Undervalued Narrative In Focus
Cheniere Energy (LNG) has just closed a US$1.2b offering of 5.800% senior notes due 2037, providing a fresh piece of long term funding that gives stockholders more detail on the company’s capital structure.
Recent trading has been strong for Cheniere Energy, with the share price at US$301.97 after a 7 day share price return of 2.89% and a 90 day share price return of 10.09%, while the year to date share price return of 52.66% sits alongside a 1 year total shareholder return of 43.47%. This points to momentum that has been building rather than fading as the company issues new long term debt and elevates long serving finance leader Zach Davis to President and Chief Financial Officer.
Scan other energy infrastructure plays showing similar momentum shifts and disciplined funding moves through our curated list of list of solid balance sheet and fundamentals (24 results)
Cheniere Energy now combines a large LNG infrastructure footprint, growing earnings, and fresh long term debt on the balance sheet. The open question is whether that strength already sits fully in the share price.
Most Popular Narrative: 10% Undervalued
With Cheniere Energy last closing at $301.97 against an analyst consensus fair value of $335.70, the analyst consensus Narrative on Simply Wall St frames the stock as undervalued based on contracted LNG volumes, earnings forecasts and cash flow assumptions built into that model.
The highly contracted nature of Cheniere Energy’s LNG platform through 2030 and into 2035, combined with an investment grade credit profile and a capital return program that targets dividend growth and share repurchases, is set to keep a large portion of future EBITDA and distributable cash flow tied to recurring, contracted revenue.
Actions to apply normal purchases and normal sales accounting to a majority of IPM gas supply volumes are intended to reduce the volatility of reported net income that comes from LNG linked derivatives, which can help future earnings more closely reflect the underlying cash generating capacity of the business.
See why 72 investors see Cheniere Energy as 10% undervalued.
Result: Fair Value of $335.70 (UNDERVALUED)
Still, Cheniere Energy faces live pressure points, including swings in LNG-linked derivatives and the federal probe into a US$370m alternative fuel tax credit payout.
Find out about the key risks to this Cheniere Energy narrative.
Another View: What The P/E Says About Cheniere Energy
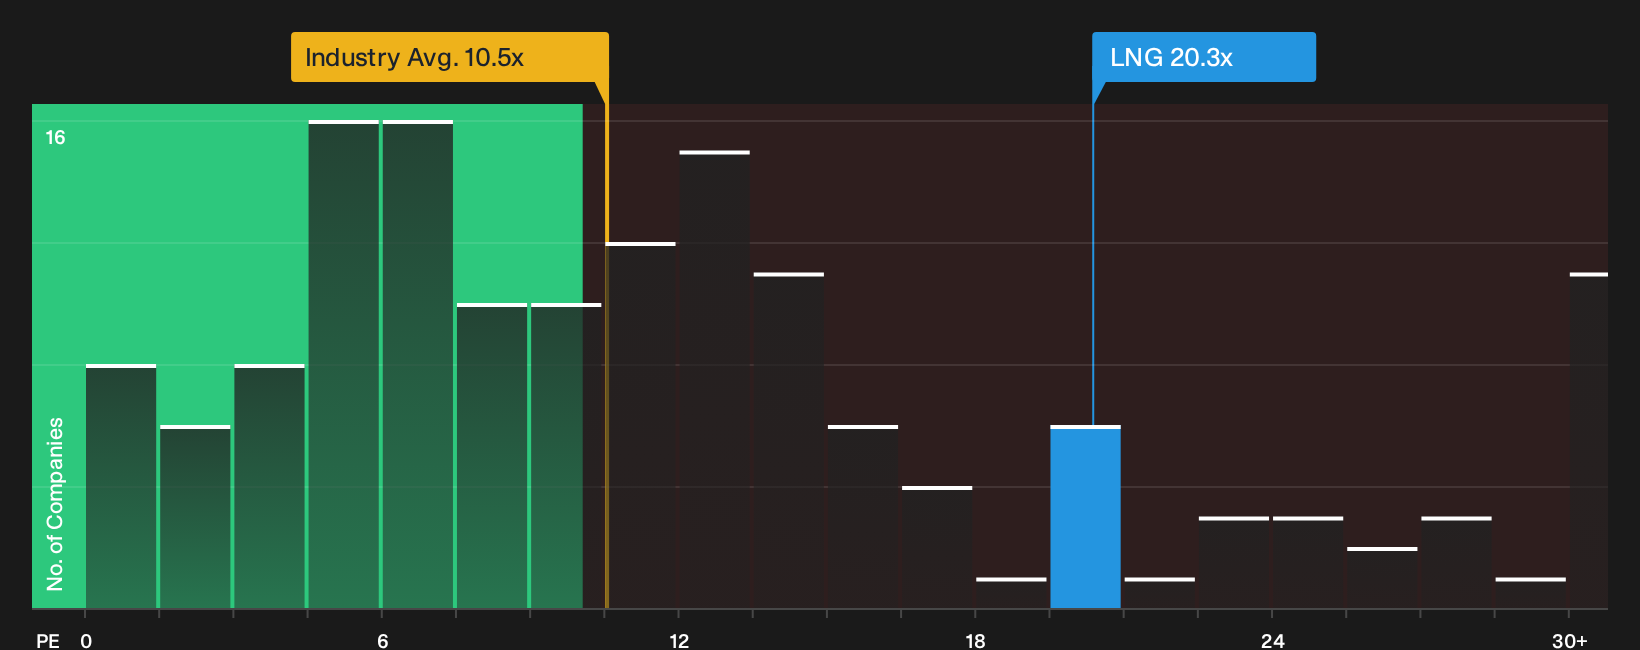
The SWS DCF model views Cheniere Energy as trading at a discount to its future cash flow value, yet the P/E ratio presents a tougher picture. LNG changes hands at about 20.3x earnings compared with 10.5x for the wider US Oil and Gas group and 17.8x for peers, and only slightly above a fair ratio of 20.2x. That kind of premium can limit upside potential if sentiment cools, so the question is whether you think the LNG contract profile justifies paying more for the stock.
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Cheniere Energy is mixed, with strong recent returns sitting alongside live risks that could reshape the story quickly. Dig into the details yourself, weigh both sides carefully, and then anchor your own view with 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Cheniere Energy?
Use Cheniere Energy as a reference point, then widen your lens with a few focused stock ideas that could sharpen your watchlist and challenge your assumptions.
- Target potential mispricing by scanning a curated pool of quality companies through 37 high quality undervalued stocks.
- Prioritize resilience first by reviewing a 29 resilient stocks with low risk scores that emphasizes sturdier balance sheets and steadier fundamentals.
- Spot opportunities others might overlook by checking a 18 high quality undiscovered gems that filters for strong underlying business quality before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com