
What UPS Earnings Beat Means For Shareholders
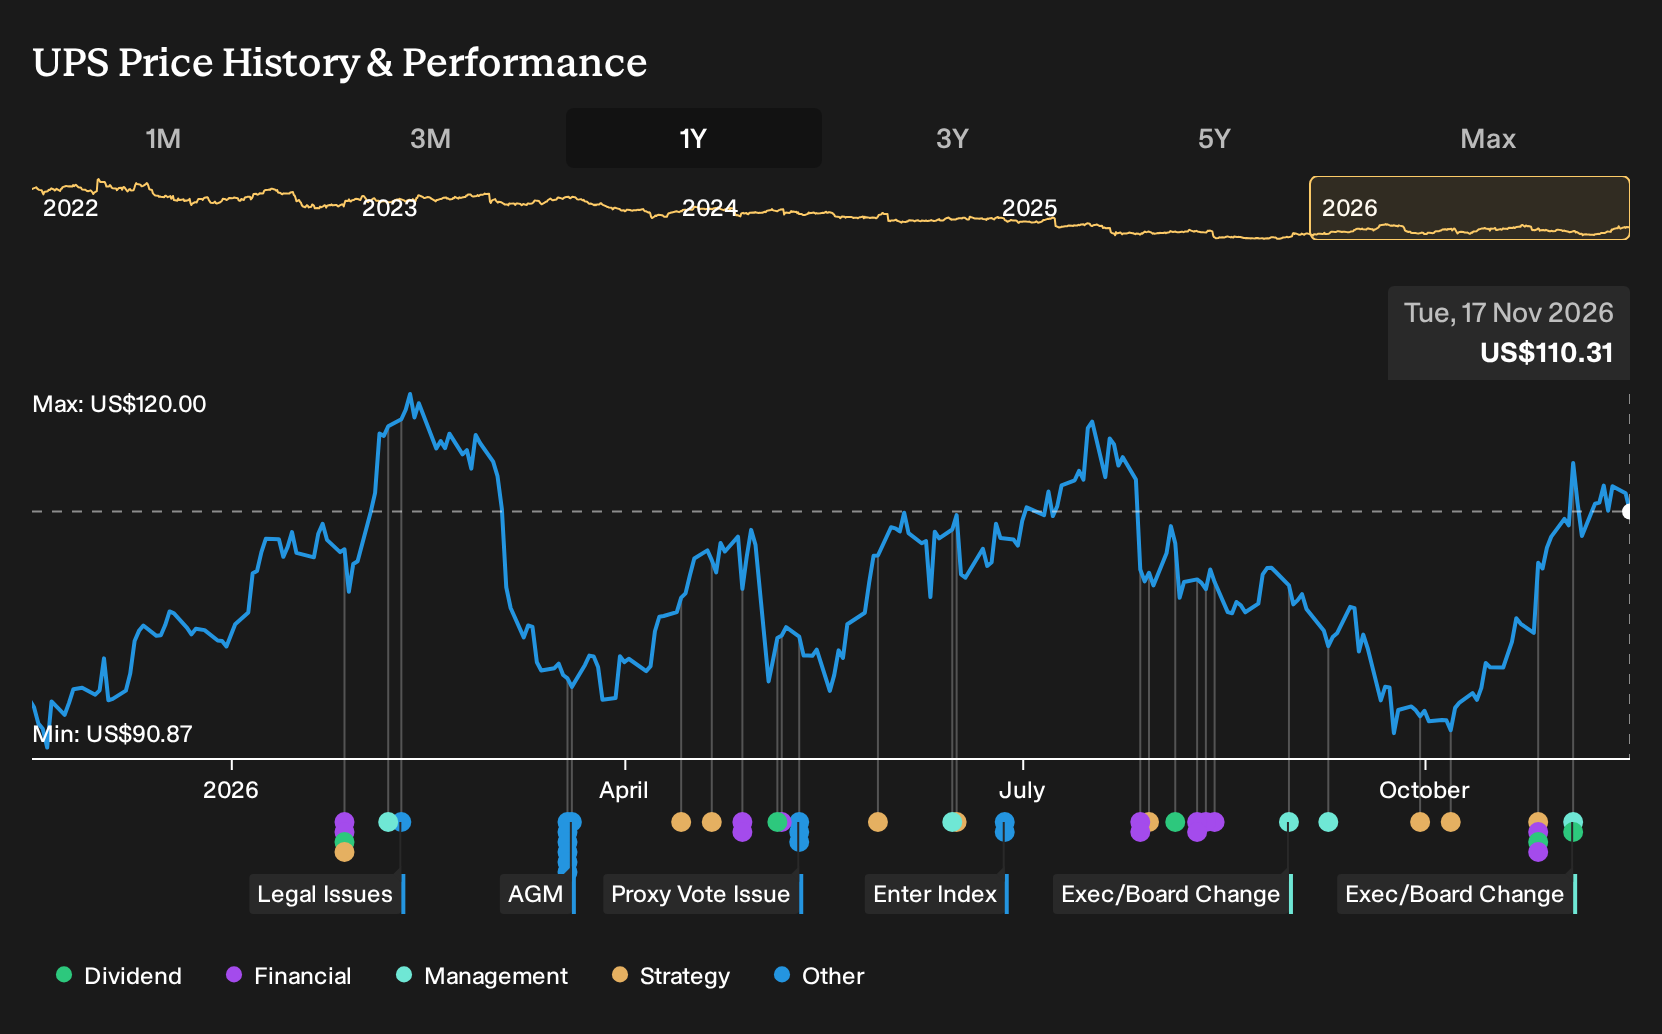
- United Parcel Service reported Q3 2026 results that exceeded analyst expectations for revenue and adjusted EPS, raised full year adjusted EPS guidance, and signaled confidence in Q4 revenue, alongside board changes, a regular dividend of $1.64 per share, and an agreement to acquire healthcare courier Smartways Logistics in Australia and New Zealand.
- The combination of stronger than expected earnings, a maintained dividend, and planned expansion of UPS Healthcare through the Smartways deal reinforces how United Parcel Service is leaning into higher value, time critical logistics rather than chasing low yield volume.
- The next area of focus will be how United Parcel Service's stronger Q3 earnings and higher guidance interact with its existing efficiency driven investment narrative.
Scan how United Parcel Service is leaning into higher value logistics, then size up a curated group of peers with resilient fundamentals using the list of solid balance sheet and fundamentals (24 results).
United Parcel Service Investment Narrative Recap
To own United Parcel Service, you need to believe the shift toward higher yielding SMB, B2B and healthcare shipments keeps gaining traction, and that automation plus building consolidation actually drop unit costs instead of disrupting service. The analyst consensus Narrative on Simply Wall St leans on that mix and efficiency story as the core earnings driver over the next few years.
Right now, the key near term catalyst is execution on network consolidation and automation while keeping on time performance intact during peak periods. The biggest risk sits around high fixed costs and labor, along with a dividend that already absorbs a large share of expected earnings, which limits flexibility if volumes or pricing soften.
The Smartways Logistics deal is the most relevant announcement here because it plugs directly into United Parcel Service's healthcare focus. Smartways gives UPS Healthcare more time critical courier capacity in Australia and New Zealand and ties Oceania customers into the broader global network, which lines up with the ongoing tilt toward premium healthcare volume.
For you, the operational question is whether UPS can integrate Smartways cleanly while still pushing through building closures, automation and cost cuts that the analyst consensus Narrative on Simply Wall St already assumes. Any execution slip, whether from integration issues, regulatory delays, or service hiccups during peak season, would likely hit that efficiency and mix story first.
United Parcel Service's narrative projects US$102.7b revenue and US$7.3b earnings by 2029. This implies 4.0% yearly revenue growth and an earnings increase of about US$2.9b from US$4.4b today.
Uncover why United Parcel Service's fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest UPS analysts focus less on healthcare expansion and more on dividend strain. They were working off projections of roughly US$91.2b in revenue and US$6.4b in earnings by 2029, so a new healthcare courier deal and a seasoned CFO joining the board could nudge those cautious views, for better or worse.
Explore 8 other United Parcel Service fair value estimates, including one that suggests as much as 20% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your United Parcel Service research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for United Parcel Service. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Parcel Service's overall financial health at a glance.
Looking for more investment ideas beyond United Parcel Service?
Once you have a view on United Parcel Service, it can help to compare its profile with other opportunities that share some of the qualities you care about, whether that is quality, resilience, or income.
- If you want potential upside with stronger fundamentals than typical micro caps, take a look at 13 elite penny stocks with strong financials that already clear key financial quality hurdles.
- For investors who care about buying strength at a reasonable price, scan a curated 37 high quality undervalued stocks that pair solid cash generation with balance sheets that are not stretched.
- If your focus is income and capital resilience, you can filter for consistent payers from a 7 dividend fortresses that combine higher yields with robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com