
What Are Wall Street Analysts' Target Price for CMS Energy Stock?
With a market cap of $21.8 billion, CMS Energy Corporation (CMS) is a diversified energy company primarily engaged in the generation, purchase, transmission, distribution, and sale of electricity and natural gas. Headquartered in Jackson, Michigan, the company serves residential, commercial, and industrial customers, primarily through its principal utility subsidiary, Consumers Energy.
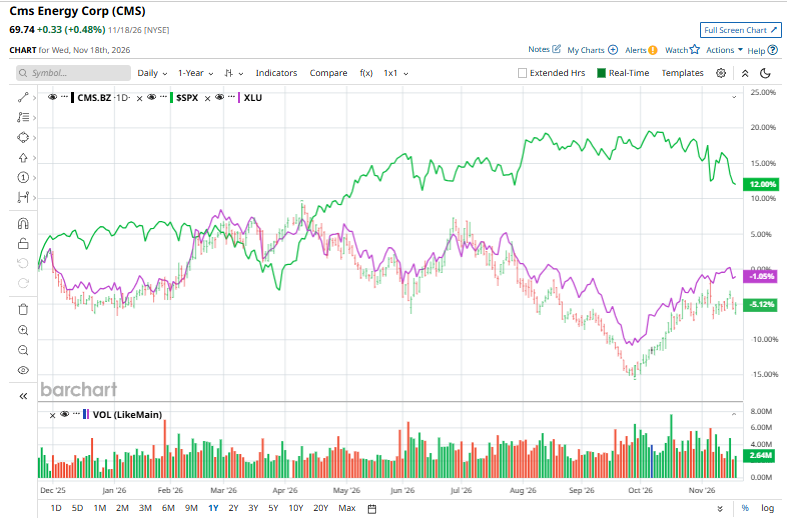
Shares of the Jackson, Michigan-based company have lagged behind the broader market over the past 52 weeks. CMS stock has plunged 6.1% over this time frame, while the broader S&P 500 Index ($SPX) has rallied 10.7%. Moreover, shares of the company have fallen 3.3% over the past six months, compared to SPX's 1.1% dip.
Looking closer, shares of the energy company have underperformed the State Street Utilities Select Sector SPDR ETF's (XLU) 2.4% increase over the past 52 weeks and have declined marginally over the past six months.
On Oct. 27, CMS Energy reported fiscal 2026 third-quarter results, with an 8% year-over-year increase in operating revenue to $2.18 billion and a 54.8% jump in adjusted diluted EPS to $1.44. Growth was supported by stronger performance across its regulated electric and natural gas utility operations. However, reported operating income plunged 90.2% to $47 million from $481 million a year earlier, primarily due to approximately $525 million in impairment, disposal, and restructuring charges associated with its NorthStar Clean Energy business.
Management reaffirmed its full-year adjusted EPS guidance of $3.83–$3.90, along with its FY2027 adjusted EPS forecast of $4.08–$4.17.
For the fiscal year ending in December 2026, analysts expect CMS' adjusted EPS to grow 7.2% year-over-year to $3.87. The company's earnings surprise history is promising. It beat or met the consensus estimates in the last four quarters.
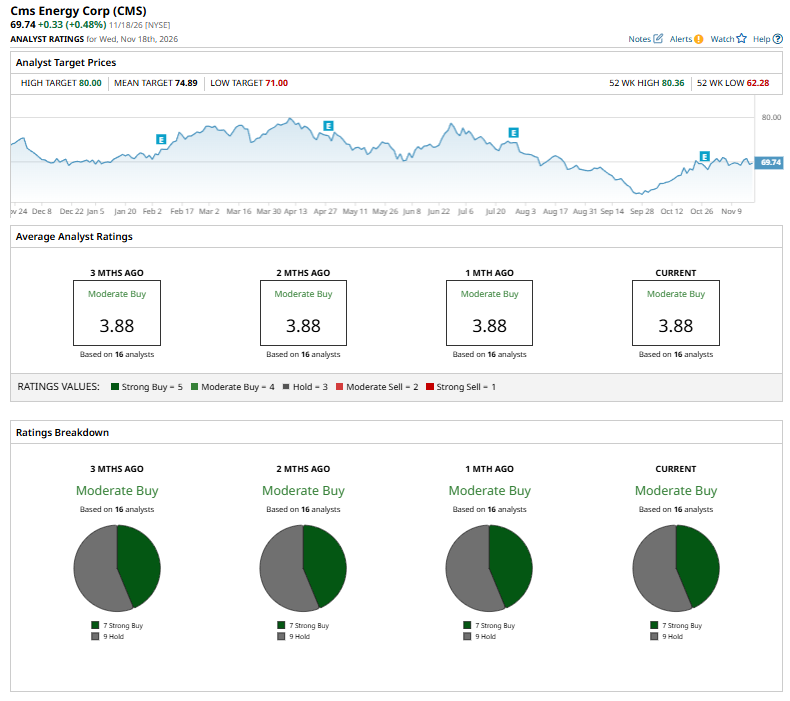
Among the 16 analysts covering the stock, the consensus rating is a “Moderate Buy.” That’s based on seven “Strong Buy” ratings and nine “Holds.”
On Oct. 22, HSBC initiated coverage on CMS Energy with a “Hold” rating and a $69 price target, citing relatively modest growth prospects compared with its utility peers. The firm projects an 11% CAGR in rate base and 8% EPS CAGR over 2026–2030, both below peer averages. HSBC also forecasts 6% annual dividend growth, with the payout ratio expected to gradually decline from approximately 60% to 55%, indicating a balanced approach to shareholder returns and earnings retention.
The mean price target of $74.89 represents a 7.4% premium to CMS’ current price levels. The Street-high price target of $80 suggests a 14.7% potential upside.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.