
Construction Partners exceeds Q3 CY2026 expectations, full-year sales guidance is solid
Civil infrastructure company Construction Partners (NASDAQ:ROAD) beat Wall Street’s revenue expectations in calendar Q3 2026 [fiscal Q4 2026], with revenue up 21.8% year on year to $1.1 billion. The company’s full-year revenue guidance of $4.23 billion at the midpoint came in 1.6% above analysts’ consensus estimates. Its GAAP profit of $1 per share was in line with analysts’ consensus estimates.
For more on Construction Partners, read our free full research report.
Construction Partners Q3 CY2026 highlights:
- Revenue $1.1 billion vs S&P analysts’ consensus estimates of $1.09 billion (21.8% year-on-year growth, 0.5% beat)
- EPS (GAAP) $1 vs analysts’ consensus estimates of $0.99 (in line)
- EBITDA guidance $602.5 million at the midpoint for fiscal 2027, above analysts’ consensus estimates of $592.2 million
- Operating margin 9.5%, down from 11.2% in the same quarter last year
- Free cash flow margin 5.9%, down from 9.5% in the same quarter last year
- Backlog $3.29 billion at quarter end, up 9.7% year on year
- Market capitalization $4.43 billion
Smith continued, "Following record fourth quarter revenue, our backlog entering fiscal 2027 strongly supports our guidance of 15% revenue growth. Additionally, in the first few weeks of fiscal 2027, we completed three acquisitions that added $65.0 million of backlog, substantially all of which we expect to convert to revenue in fiscal 2027. Looking beyond the first half of fiscal 2027, we see two primary catalysts for meaningful margin improvement: the continued integration of our fiscal 2026 acquisitions and improved recovery of elevated diesel fuel costs through project pricing. As we move through the second half of fiscal 2027, we expect to benefit from completing lower-margin projects in our acquired backlog and replacing them with higher-margin work, while progressively incorporating increased diesel fuel costs into project pricing through our cost pass-through operating model. Additionally, greater economic certainty and improving conditions in residential and commercial construction markets could provide further opportunities for margin expansion."
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Construction Partners’s revenue grew at a strong 32.2% annualized rate over the last five years. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
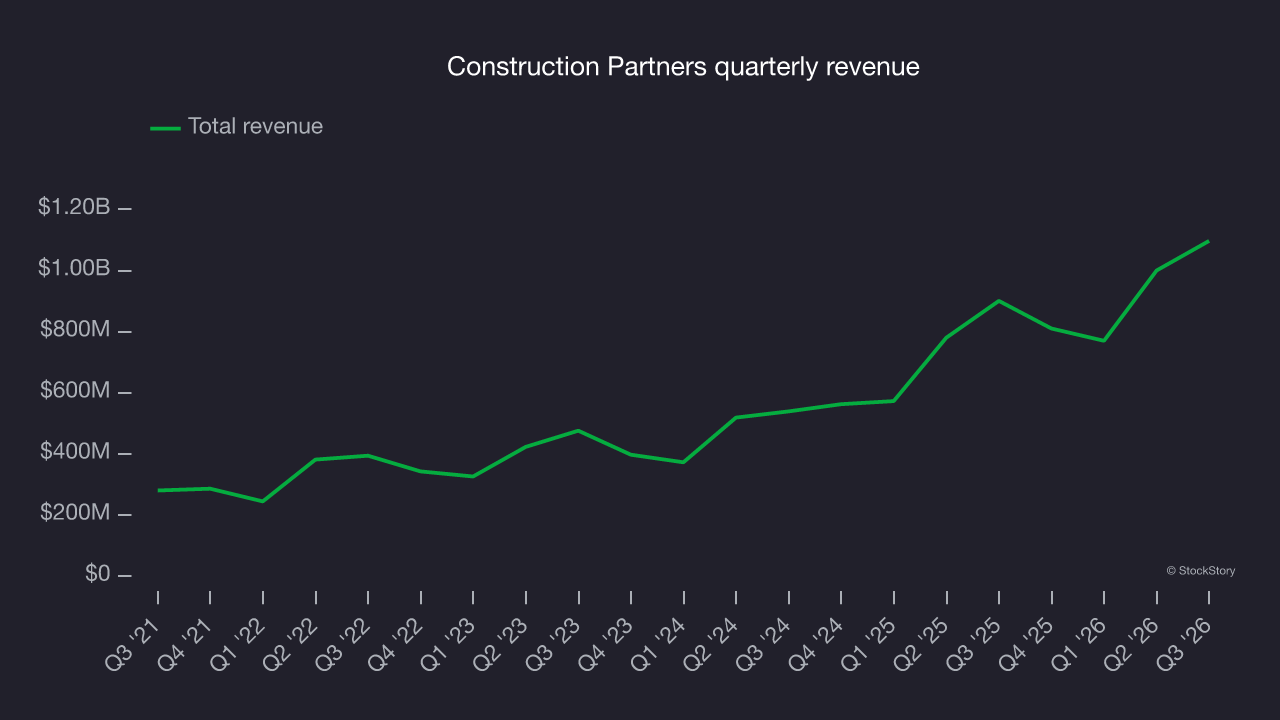
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Construction Partners’s annualized revenue growth of 41.9% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. Construction Partners isn’t alone in its success as the construction and maintenance services industry experienced a boom, with many similar businesses also posting double-digit growth. 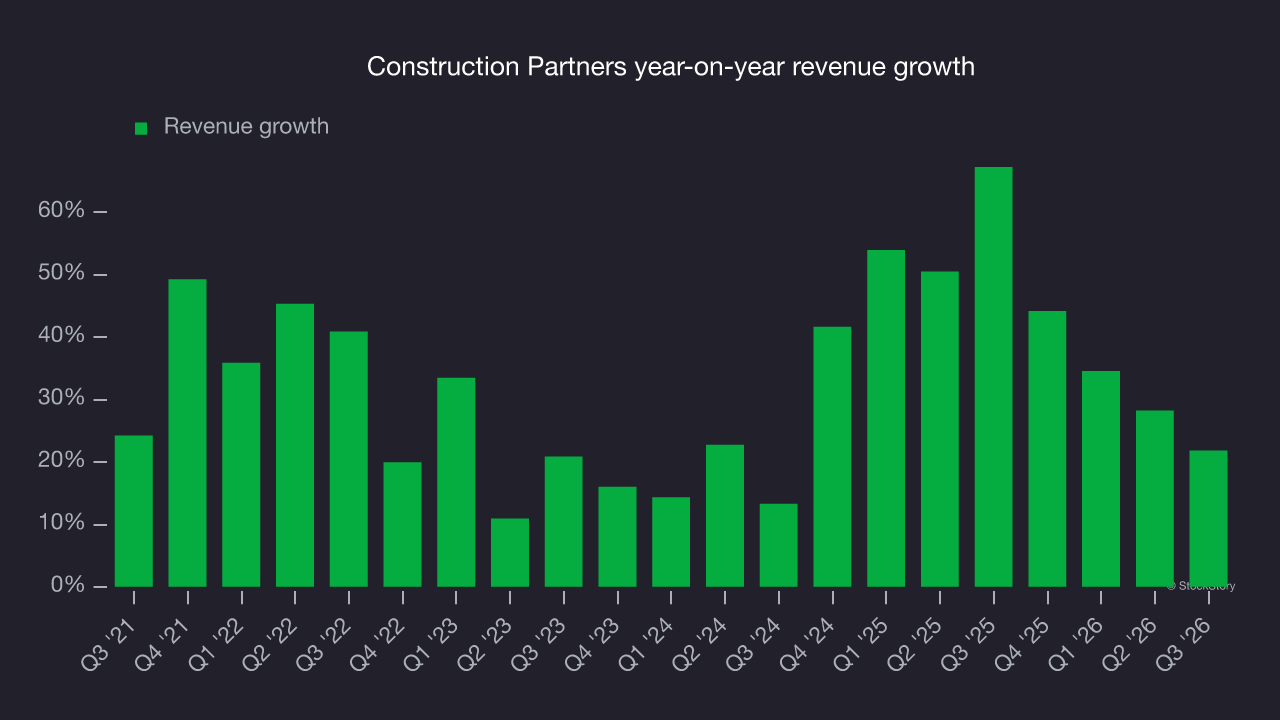
Analyzing the company’s backlog, or the value of its outstanding orders that have not yet been executed or delivered, provides a closer look at its revenue dynamics. Construction Partners’s backlog reached $3.29 billion in the latest quarter and averaged 20.7% year-on-year growth over the last two years. Revenue growth outpaced backlog growth, indicating the company fulfilled orders at a faster rate than it added new orders to the backlog. This implies Construction Partners was operating efficiently but raises questions about the health of its revenue pipeline. 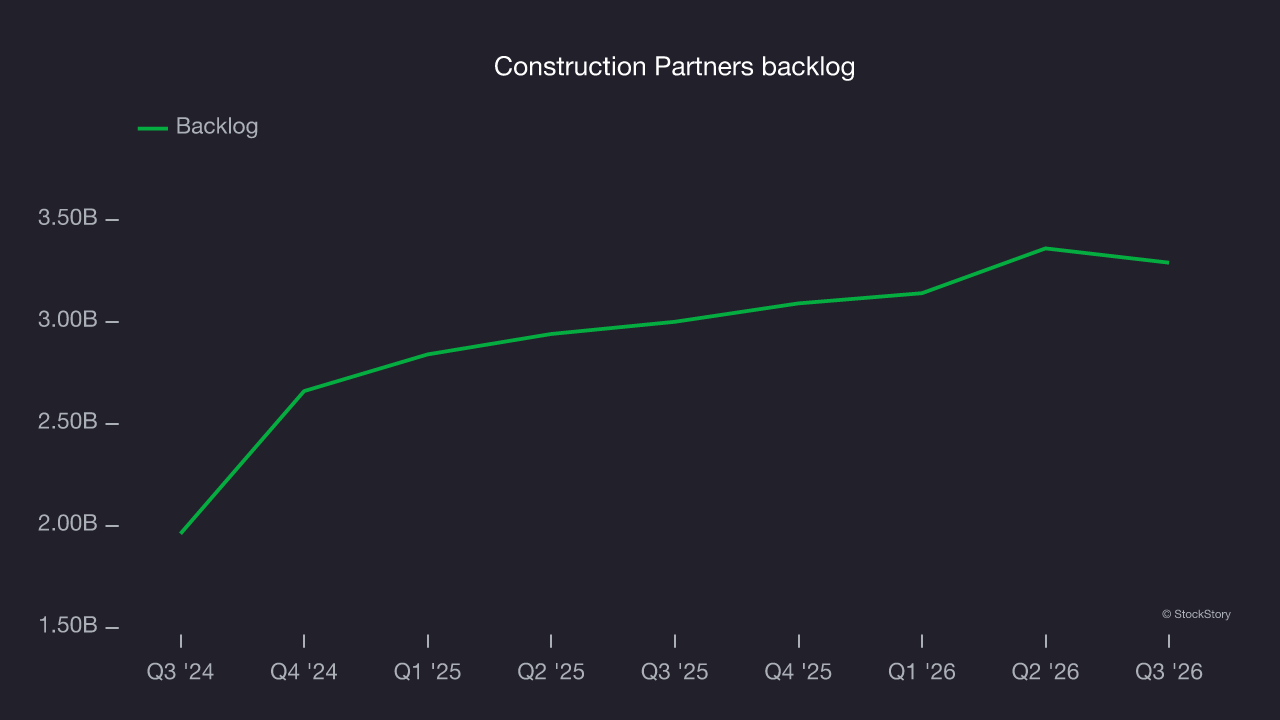
This quarter, Construction Partners reported strong year-on-year revenue growth of 21.8%, and its $1.1 billion of revenue topped Wall Street’s consensus estimates by 0.5%.
Looking ahead, sell-side analysts expect revenue to grow 13.1% over the next 12 months, according to S&P, a deceleration versus the last two years. Despite the slowdown, this projection is noteworthy and indicates the market sees success for its products and services.
Operating margin
Over the last five years, Construction Partners’s operating margin rose by 5.5 percentage points. This improvement shows its costs declined relative to revenue. Its trailing 12-month operating margin was 8.2%.
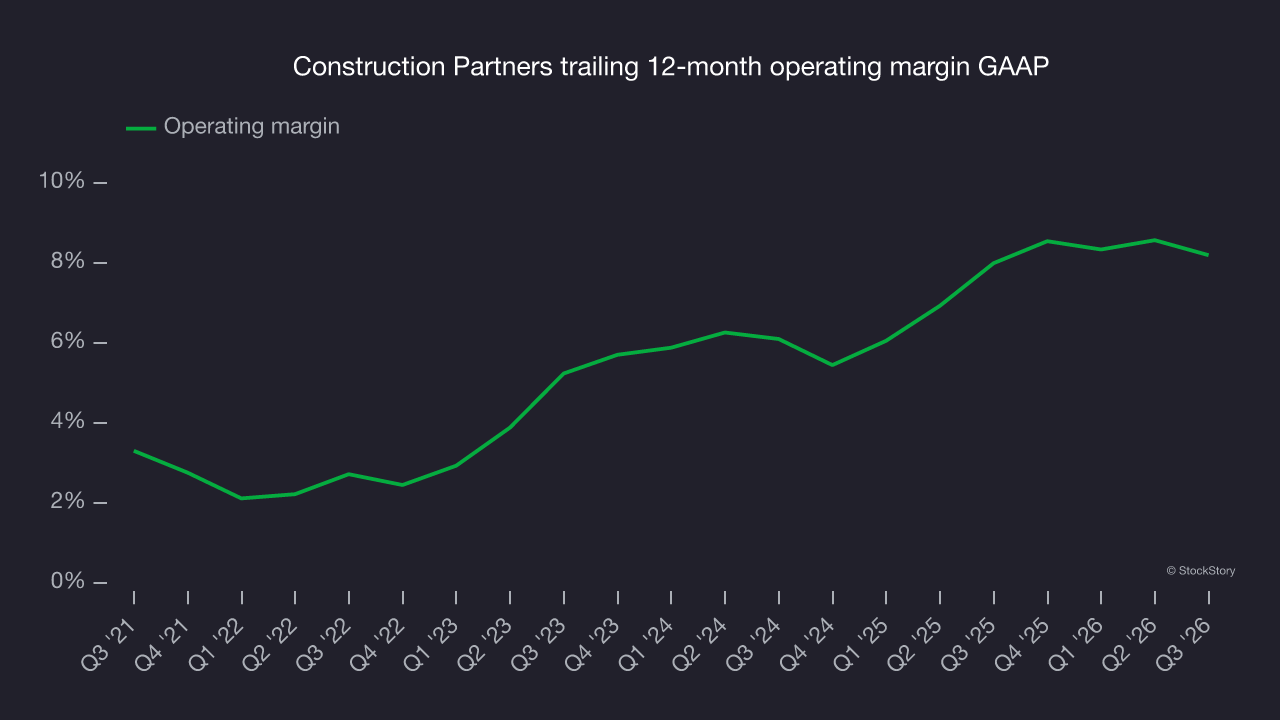
In Q3, Construction Partners generated an operating profit margin of 9.5%, down 1.7 percentage points year on year. Since Construction Partners’s gross margin decreased more than its operating margin, its recent inefficiencies appear to have stemmed more from weaker leverage on its cost of sales than from increased marketing, R&D and administrative overhead expenses.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Construction Partners’s EPS grew at a 45.4% compounded annual growth rate over the last five years, higher than its 32.2% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
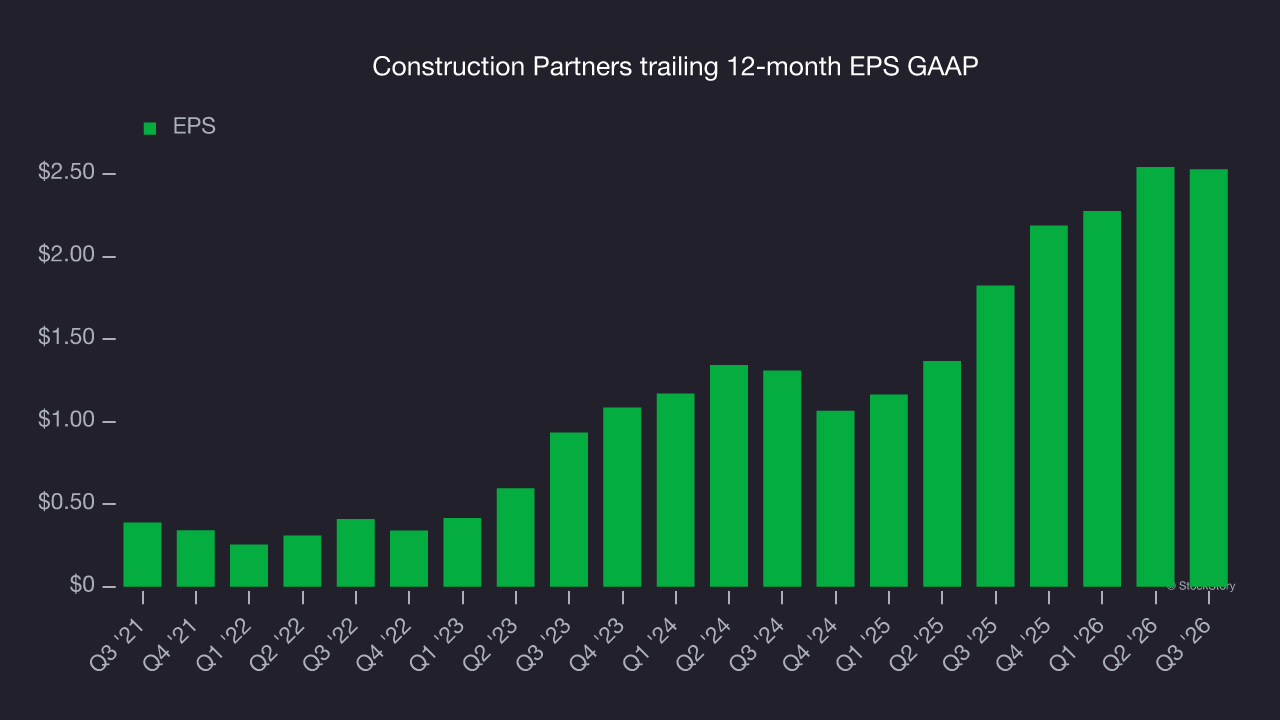
We can take a deeper look into Construction Partners’s earnings to better understand the drivers of its performance. As we mentioned earlier, Construction Partners’s operating margin declined this quarter but expanded by 5.5 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
Construction Partners’s two-year annual EPS growth of 38.9% was lower than its five-year trend but remained healthy.
In Q3, Construction Partners reported EPS of $1, down from $1.01 in the same quarter last year. This result was close to analysts’ consensus estimates. Over the next 12 months, Wall Street expects Construction Partners’s full-year EPS to grow 18.7% from $2.53 to $3.00, according to S&P.
Key takeaways from Construction Partners’s Q3 results
Higher-than-expected full-year guidance for both EBITDA and revenue gave Construction Partners’ quarter some clear positives. It was a decent quarter overall, and shares rose 2.2% to $79.75 immediately after the report.
Construction Partners had a solid quarter, but is the stock a buy? Consider valuation and business quality as well as the latest earnings when making that decision. For more on Construction Partners, read our full research report here (it’s free).