
2 Growth Stocks to Buy in November Without Any Hesitation
Key Points
Vertex Pharmaceuticals' core business remains healthy, and it has a portfolio of kidney disease candidates that could top $10 billion in annual sales.
Regeneron's Dupixent looks unstoppable, while a newer formulation of Eylea cushions the decline of the older version.
Vertex Pharmaceuticals (NASDAQ:VRTX) and Regeneron (NASDAQ:REGN) did not have a strong start to the year -- both biotech giants were in decline for much of the first half of 2026. However, they have rebounded, and as of this writing, both have delivered above-average returns this year. They haven't peaked yet: Vertex Pharmaceuticals and Regeneron arguably remain excellent stocks to buy this month and hold onto over the medium term. Let me explain.
Image source: Getty Images.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
1. Vertex Pharmaceuticals
Vertex Pharmaceuticals could soon receive approval for a brand-new product, povetacicept. This investigational medicine for IgA nephropathy (a kidney disease) performed well in a Phase 3 study earlier this year, and regulators in the U.S. are expected to decide whether to approve it or not by the end of November. Povetacicept would be a nice addition to Vertex's lineup, which is still dominated by its cystic fibrosis (CF) medicines.
The drugmaker derives most of its revenue from CF therapies, an area where it is the undisputed leader. In the third quarter, Vertex's total revenue increased by 12% year over year to $3.44 billion. Vertex is unlikely to face stiff competition, generic or otherwise, within its core CF market anytime soon. But newer medicines, like povetacicept, will help expand and diversify its lineup.
Povetacicept could be the first of several drugs across kidney diseases for which Vertex earns approval. The company's pipeline also includes inaxaplin, an investigational medicine for APOL1-mediated kidney disease that is currently undergoing late-stage studies. Then there is VX-407, which is being developed to treat autosomal dominant polycystic kidney disease; VX-407 is in Phase 2 studies. Between them, these three drugs could eventually generate over $10 billion in peak annual sales, according to some estimates, which isn't that far off from the annual revenue it currently makes from its CF franchise.
Further, Vertex recently expanded its lineup and pipeline through the $10 billion acquisition of Crinetics Pharmaceuticals. The biotech estimated that the products it acquired through this buyout could eventually generate more than $5 billion in peak annual sales. And we haven't considered the company's newer launches, such as Casgevy, a gene-editing medicine for two rare blood diseases, and Journavx, a therapy for acute pain. Vertex boasts several other pipeline candidates, too. Vertex's prospects look very attractive as it continues posting excellent results while making meaningful clinical and regulatory progress.
2. Regeneron
Regeneron's financial results have smashed expectations this year, powered by a strong performance from its biggest growth driver, Dupixent, a medicine for eczema that it co-markets with Sanofi (NASDAQ:SNY). In the third quarter, Regeneron's revenue increased by 36% year over year to $5.1 billion. That was the fastest quarterly year-over-year growth rate the biotech company has recorded in years.
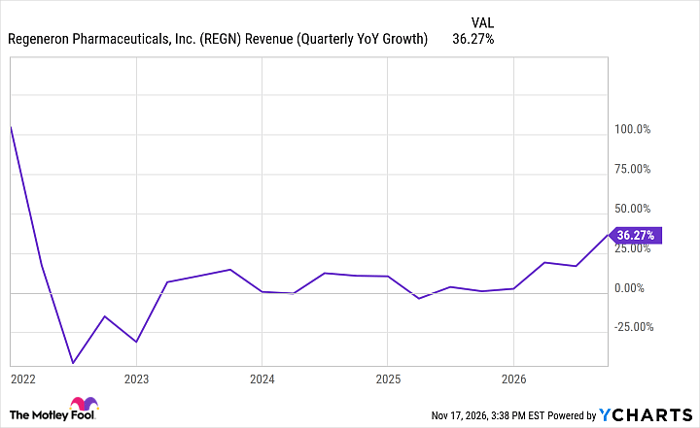
REGN Revenue (Quarterly YoY Growth) data by YCharts
Dupixent's total sales (as reported by Sanofi) were $6.5 billion, up 35% from the year-ago period. Regeneron is achieving impressive financial results despite continued pressure on its Eylea franchise. This medicine for several eye-related disorders has been facing stiff competition, biosimilar and otherwise.
But a newer, higher-dose (HD) formulation of Eylea with a more convenient dosing schedule is helping to smooth out the losses. In the third quarter, U.S. sales of Eylea HD increased 62% year over year to $699 million, although total Eylea and Eylea HD combined U.S. sales declined by 1% year over year to $1.1 billion.
Still, overall, Regeneron is performing very well, and the company could maintain solid momentum as the impact of the older version of Eylea on its financial results fades. Meanwhile, Regeneron boasts an attractive pipeline across oncology, weight loss, fatty liver disease, and other areas. The company should have a much stronger approved lineup within the next few years.
And while Dupixent could lose patent exclusivity in the early 2030s, Regeneron and Sanofi are planning to launch another formulation of the blockbuster drug that could grant it a more convenient dosing schedule and help it retain a decent market share.
That, combined with newer products it should launch by then, could allow Regeneron to continue posting solid financial results and deliver superior returns.
Prosper Junior Bakiny has positions in Vertex Pharmaceuticals. The Motley Fool has positions in and recommends Regeneron Pharmaceuticals and Vertex Pharmaceuticals. The Motley Fool has a disclosure policy.