
QuantumScape (QS) Stock May Trade At A Premium As Osprey Debuts
QuantumScape has been back in the headlines after unveiling its Osprey all solid state battery platform, yet the stock’s long slide raises a basic question about what investors are really paying for on the balance sheet. With the share price now far below levels seen in earlier years, the issue is whether today’s valuation lines up with the company’s book value.
- Over the past 5 years the share price has fallen about 90.5%, which puts the spotlight squarely on how the current market value compares with the equity recorded on QuantumScape’s books.
- The new Osprey platform, which targets fast charging, high energy density and operation at standard atmospheric pressure, may support expectations for how quickly QuantumScape can turn its technology into commercial assets that feed into book value over time.
- There is a second opinion on QuantumScape worth weighing. See what analysts think QuantumScape's shares could be worth.
The stock’s next move may depend on whether the recent share price now sits in line with, or far away from, the book value backing QuantumScape on its balance sheet.
If you want to test this same book value question across a wider set of potential opportunities, compare QuantumScape with companies in the 34 high quality undervalued stocks list.
Has QuantumScape Run Too Far on Book Value?
P/B fits QuantumScape because investors are mainly weighing the value of its balance sheet against the share price rather than current earnings.
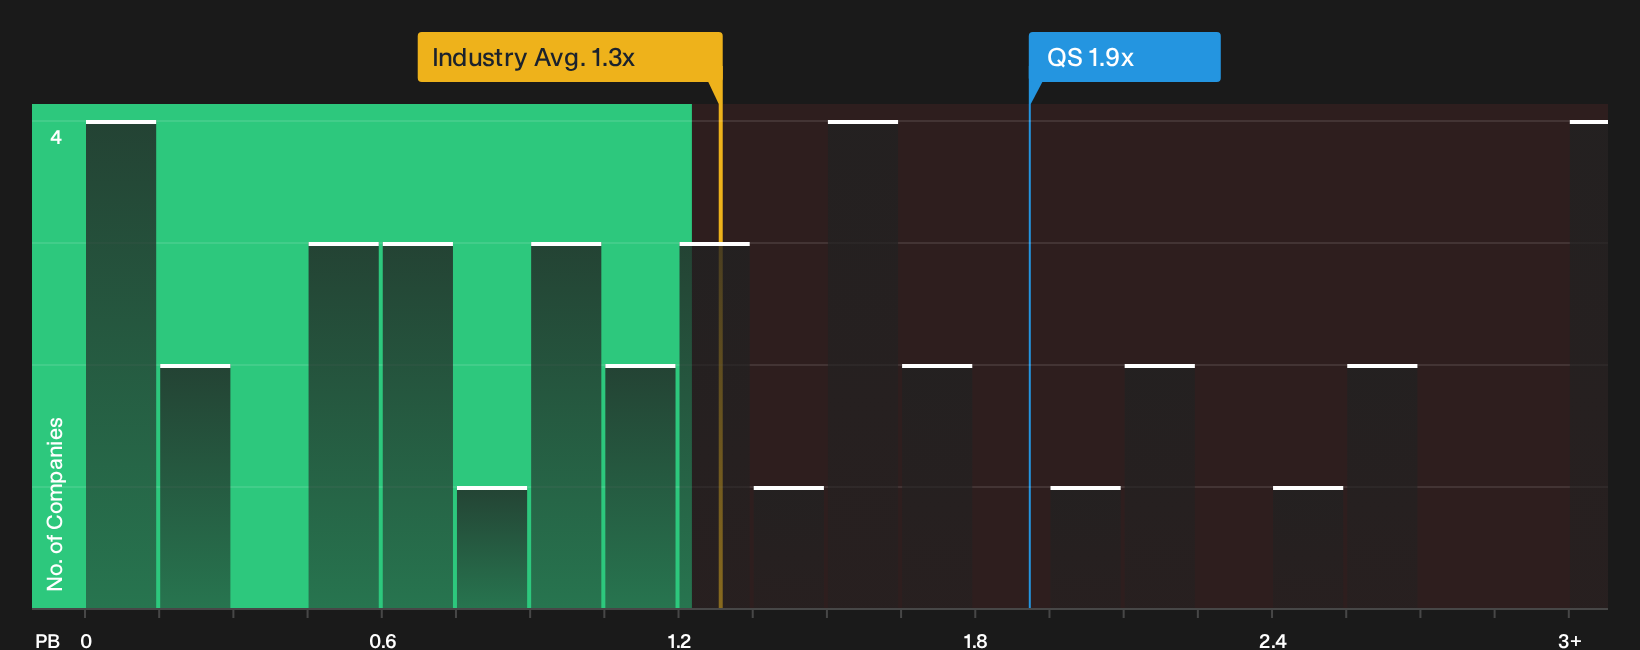
The stock trades on a P/B of about 1.9x, compared with an auto components industry average near 1.3x and a peer group around 1.8x. That points to QuantumScape changing hands at a premium to the sector benchmark on this metric, even though the ratio is only slightly ahead of closer peers. After the Osprey announcement sharpened attention on the technology roadmap, the market is still asking you to pay more than the broader industry level for each dollar of book equity.
For anyone assessing QuantumScape, the question is whether its R&D heavy asset base and commercialisation path justify paying that higher multiple relative to the industry average or whether the balance sheet support does not fully explain the current P/B level. Explore the numbers behind QuantumScape's P/B valuation.
The QuantumScape Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where QuantumScape's price to book puzzle leaves off and explain what kind of growth, margins and earnings profile would need to materialise for the stock to appear meaningfully cheap or expensive compared with today's quote. Each scenario links a fair value estimate to a clear set of potential catalysts and risks, so you can follow over time which storyline about QuantumScape's future is actually unfolding on the Community page.
QuantumScape attracts two very different readings, split between a licensing led upside story and a long, costly road to commercial proof.
Bull case: 84% undervalued
According to davidlsander, an investor in the Simply Wall St Community, the upside rests on QuantumScape turning Osprey into a licensing standard.
"With $819.8M in liquidity and initial customer billings logged from Honda and defense partners in Q3 2026, the shift from pre-revenue R&D lab to an industry-standard licensing platform is finally taking shape..."
Discover why this Narrative puts QuantumScape at 84% undervalued.
Bear case: 22% overvalued
The bearish analyst Narrative on Simply Wall St focuses on the long stretch of high spending before QuantumScape proves large scale commercial demand.
"Although QuantumScape is billing customers in data centers and advanced applications, the long delay to broad commercialization around 2029 and continued lack of GAAP revenue leave a multi year gap where operating expenses remain high and the path to meaningful revenue and earnings is still unproven..."
Explore why this Narrative puts QuantumScape at 22% overvalued.
Before acting on QuantumScape's valuation, there is one more angle to weigh
Numbers only tell part of the story. The people steering QuantumScape and the way their rewards line up with shareholder outcomes can tilt the whole risk and reward profile. See who runs QuantumScape and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com