
Southern Copper (SCCO) Could Be 19% Undervalued Following Its Peru And Mexico Buildout
Capital investment plans sharpen focus on Southern Copper
Fresh commentary around Southern Copper (NYSE:SCCO) has zeroed in on its more than US$20.5b capital investment program across Peru and Mexico, and how that spending ties into copper shortage narratives investors are tracking.
Southern Copper’s share price has retreated sharply in recent weeks, with the stock down 29.35% on a 30 day share price return and 33.82% over 90 days, even though total shareholder return over five years sits at 218.36%.
Scan how other copper producers are priced against similar supply themes and balance sheet profiles by reviewing the hand picked 16 top copper producer stocks alongside Southern Copper.
After a near one third slide from recent highs, Southern Copper now trades well below both analyst targets and some intrinsic estimates. Is the gap pointing to mispricing, or simply catching up with fair value when projects are already priced in?
Most Popular Narrative: 19% Undervalued
On the analyst consensus Narrative on Simply Wall St, Southern Copper screens as undervalued, with a fair value of $175.30 against a last close of $141.46. This puts the recent share price slide in a different light and frames the capex debate around execution rather than hype.
Southern Copper is pursuing a capital investment program of more than US$20.5b across Peru and Mexico. A bearish view is that current valuation already factors in the full revenue and earnings uplift from this spending even though the assets are still under construction and not yet generating matching cash flows.
See why 58 investors see Southern Copper as 19% undervalued.
Result: Fair Value of $175.30 (UNDERVALUED)
Still, the Southern Copper story can break if projects in Peru or Mexico encounter regulatory or community roadblocks, or if copper prices slip below analyst assumptions.
Find out about the key risks to this Southern Copper narrative.
Another View: Southern Copper Through The P/E Lens
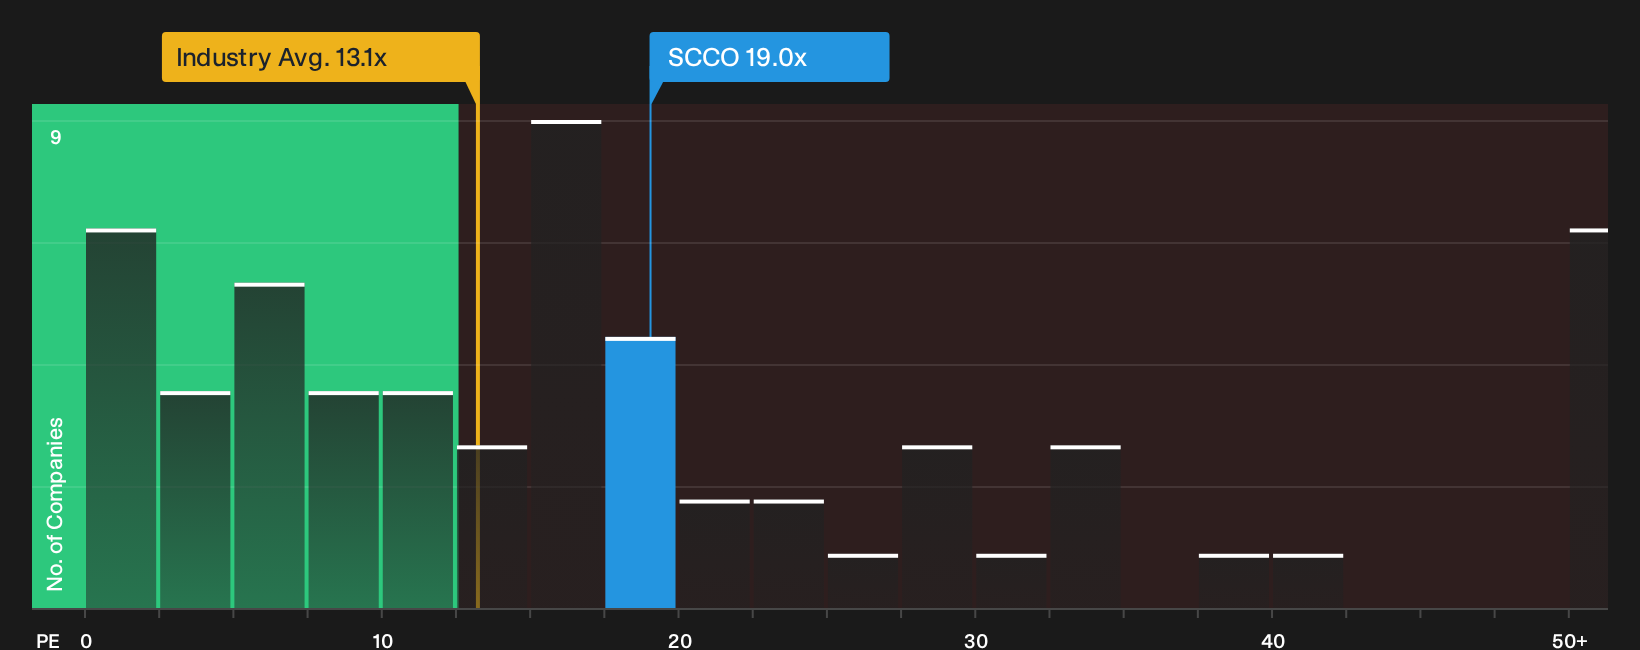
The fair value story around Southern Copper looks different once the P/E is front and center. The stock trades on roughly 19x earnings. That is richer than the US Metals and Mining industry on 13.1x and above peers at 15.1x, even though the fair ratio sits close by at 19.4x.
This mix points to limited room for error. The market already pays a premium against the sector, while the fair ratio hints that valuation might only adjust at the margin rather than reset sharply. For an investor weighing copper exposure, the question is whether that premium feels like a cushion or a tightrope.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Southern Copper can create confusion, so move quickly, review the numbers, and weigh both sides of the story. For a clear snapshot of the key trade offs, start with the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Southern Copper?
Do not stop at Southern Copper. Fresh opportunities often sit just outside your current watchlist, and waiting too long can mean missing cleaner entries.
- Target stability by reviewing a 30 resilient stocks with low risk scores that groups businesses with lower risk scores and more resilient profiles when markets turn choppy.
- Hunt for value by scanning a 19 high quality undiscovered gems that highlights financially strong companies the crowd has not piled into yet.
- Prioritize quality balance sheets by checking a list of solid balance sheet and fundamentals (25 results) that surfaces firms with robust finances backing their operations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com