
Is Veeva Systems (VEEV) Undervalued After The ACTO AI CRM Integration?
Why the ACTO Integration Matters for Veeva Systems
Veeva Systems (VEEV) just saw ACTO Technologies plug its CxZone AI roleplay tool directly into Vault CRM through X-Pages, giving life sciences reps AI practice sessions inside their existing workflow.
This is not a headline grabbing deal like a merger or big financing round. It does, however, draw attention to how Veeva Systems keeps layering third party tools onto its commercial platform, which is part of what investors are watching with this stock.
Recent trading tells a mixed story for Veeva Systems. The share price is up 21.29% year to date and 7.39% over 90 days, yet down 16.95% on a 30 day view. This suggests momentum has cooled even as the 3 year total shareholder return of 50.77% still points to a stronger longer term track record than the 9.08% total shareholder return over 1 year.
Compare Veeva Systems with other AI enabled healthcare platforms by scanning our hand picked 35 healthcare AI stocks that are also building tools directly into clinicians' and field teams' daily workflows.
Veeva Systems now has fresh product news, but its share price has pulled back sharply in the last month. Is this AI integration a chance to step in now, or is it better to wait for a cheaper entry point for the stock?
Most Popular Narrative: 30% Undervalued
The Simply Wall St Community narrative pegs Veeva Systems at a fair value of about $383.14 per share versus the recent $266.22 close, which frames the ACTO integration inside a wider undervaluation story according to John_Eric, an investor in the Simply Wall St Community who wrote the narrative.
"Veeva’s attraction is not simply that it sells software to pharmaceutical companies. Its attraction is that it sits inside workflows where reliability, compliance, historical data, and institutional trust matter enormously. Those characteristics can produce customer relationships that are unusually long-lived and difficult to displace."
See why 53 investors see Veeva Systems as 31% undervalued.
Result: Fair Value of $383.14 (UNDERVALUED)
Still, Veeva Systems faces real pressure points, including potential disruption from large pharmaceutical mergers and the risk that Falcon AI tools fail to gain meaningful adoption.
Find out about the key risks to this Veeva Systems narrative.
Another View: What Veeva Systems’ P/E Is Telling You
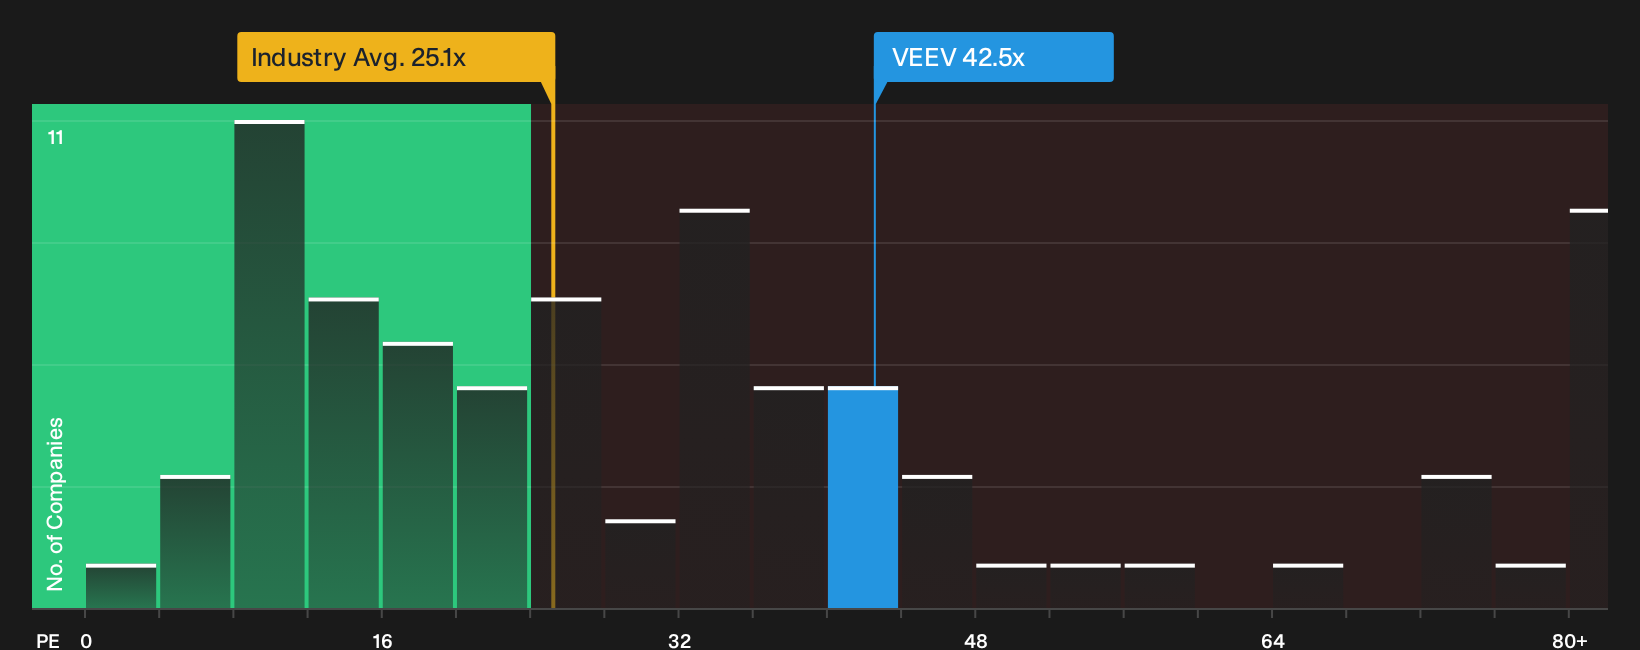
DCF work points to Veeva Systems trading about 17.2% below an estimated future cash flow value of $321.69, which fits the undervalued story. The P/E picture is less forgiving. At 42.5x, the stock looks expensive versus the global Healthcare Services average of 25.1x and a fair ratio of 33.4x. That gap can mean investors are paying up for quality, or taking on valuation risk if expectations cool from here. Which lens do you trust more for your own hurdle rate?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Veeva Systems feels familiar, treat it as a signal to move quickly, examine the data, and decide where you stand once you have weighed 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Veeva Systems?
If Veeva Systems has sharpened your thinking, do not stop here. Broaden your watchlist and pressure test your thesis against other high quality opportunities.
- Target potential mispricing by scanning a curated pool of quality candidates through the 42 high quality undervalued stocks.
- Find income-focused opportunities by checking companies with reliable payouts inside the 8 dividend fortresses.
- Focus on financially resilient businesses by filtering for strong balance sheets and fundamentals using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com