
Should Growing Order Backlogs Require Action From Accenture (ACN) Investors?
- Ontario's Workplace Safety and Insurance Board reported that its employer registration process, modernized with Guidewire and Accenture, shifted from paper-heavy, multi-day processing to an online flow. About 90% of roughly 30,000 annual new employers can now register in under ten minutes with instant decisions for routine cases.
- The success of this long-running partnership, capped by a 100 customer satisfaction score and reduced manual workloads, highlights how Accenture’s delivery track record and role as lead implementation adviser can support demand for complex digital and future AI-driven transformations.
- Next, the focus turns to how Accenture’s backlog resilience and this kind of large-scale digital execution could shape the broader investment narrative.
Accenture Investment Narrative Recap
To own Accenture, you need to believe large enterprises will keep paying for complex digital and AI-heavy projects, even as IT budgets get more selective. According to C_Coffeen, a Simply Wall St Community investor who wrote the Narrative, Accenture is effectively selling the shovels for corporate AI. The recent Ontario registration overhaul supports that view, but the near term still depends on how quickly clients commit to new transformation programs after recent IT spending caution.
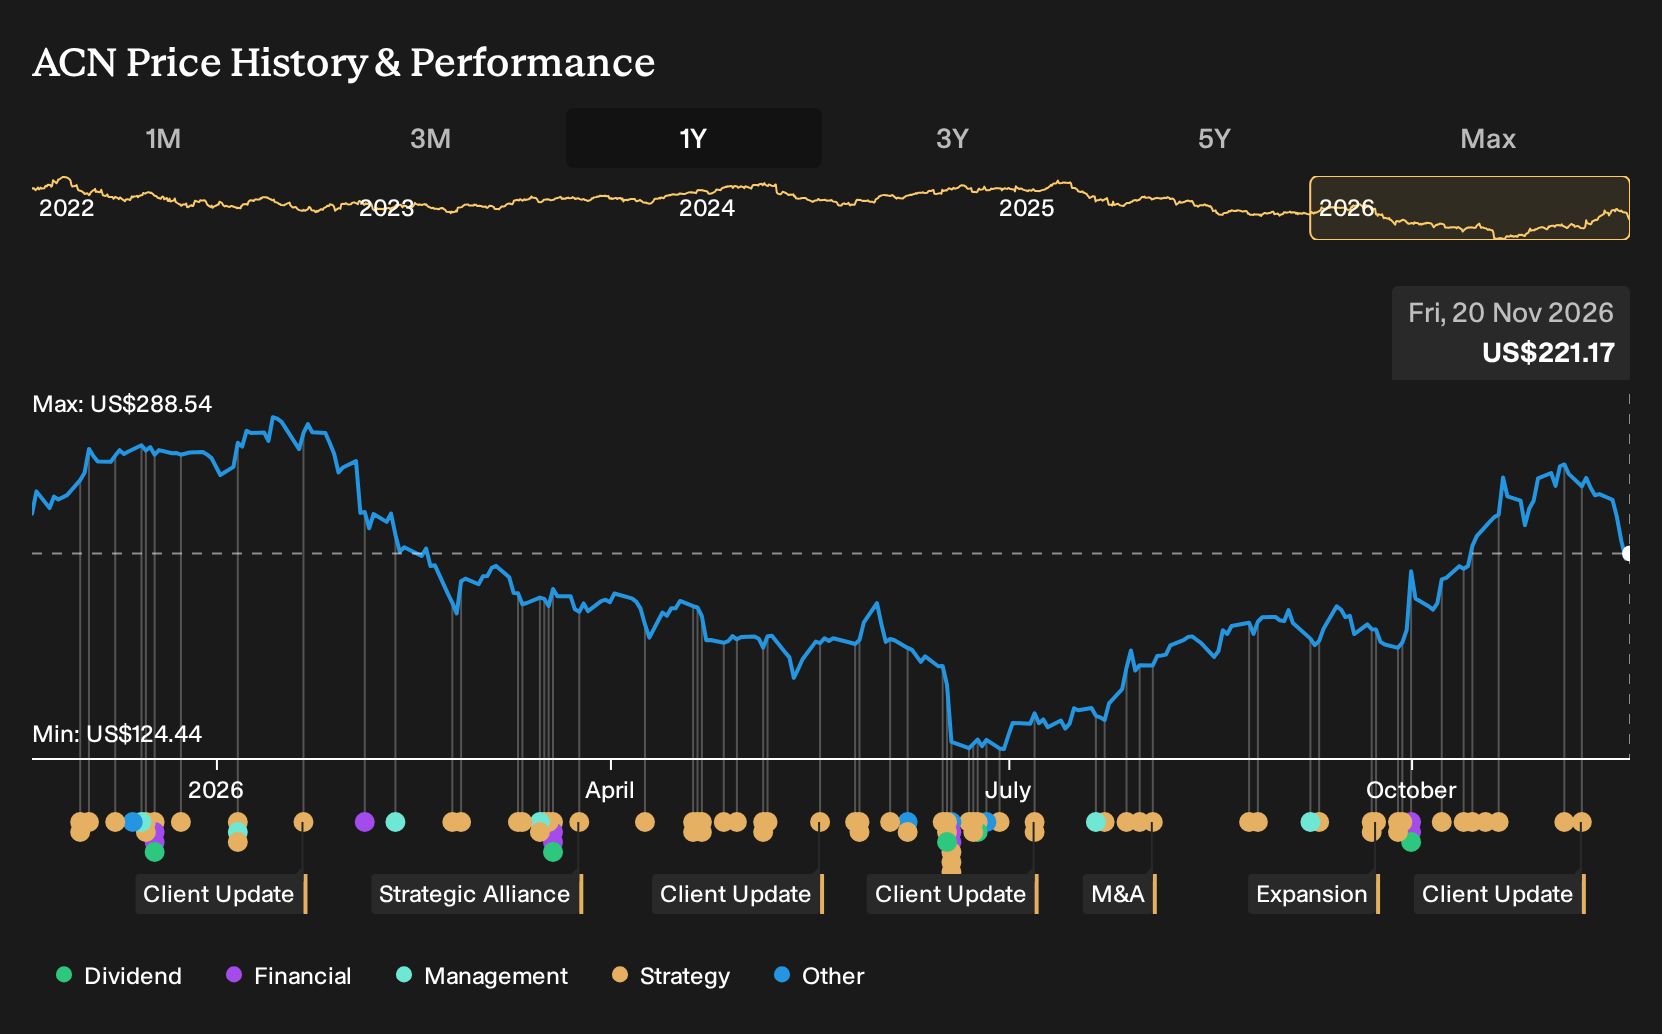
The key short term swing factor is demand translating into signed work, given management expects fiscal 2027 revenue growth of 3% to 6% in local currency. Pricing pressure in several service lines is the main operational risk, especially after the stock fell 4.9% on 18 November 2026. The Ontario project itself looks helpful for credibility, though not large enough to change that demand and pricing equation on its own.
The most relevant recent comment comes from the Carillon Eagle Growth & Income Fund, which flagged that fears around AI disruption at Accenture have eased as order backlogs continued to grow. That backlog reference pairs well with the Ontario win. It shows clients still look to Accenture to build and maintain complex automation and AI-ready infrastructure rather than bypassing it.
Carillon also suggested valuations might already reflect a tougher AI scenario, with Accenture still contributing to returns despite a weak start to the year and market pressures. For investors tracking catalysts, that sets a clear test. If backlog and AI-led workstreams hold up while pricing remains under pressure, the business leans on utilization, cost discipline, and execution quality on projects like the Ontario program.
C_Coffeen’s narrative calculates a US$280 fair value for Accenture by assuming revenue grows 10.8% a year and the future profit margin settles at 11.0%. That combination is used to support earnings power that, in the narrative, aligns with a P/E that indicates a value of US$280.
Discover why Accenture's fair value indicates a 27% potential upside to its current price, a gap that may narrow if sentiment changes.
Exploring Other Perspectives
Some of the most optimistic analysts frame the Ontario win through a different lens. They already expected Accenture to move toward about US$91.5b of revenue and US$10.7b of earnings by 2029, with margin gains on top. Those projections were set before this project update, so you might see their narrative shift even further, or not, as new data comes in.
Explore 8 other Accenture fair value estimates, including one that suggests as much as 36% potential upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Accenture research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Accenture. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Accenture's overall financial health at a glance.
Looking for more Accenture style investment ideas?
If the Accenture story has you thinking about portfolio upgrades, it can help to line it up against a broader watchlist of potential opportunities. The Simply Wall St Screener lets you filter by quality, balance sheet strength, or income focus so you can build a list that matches how you like to invest.
- For investors who want quality and value in the same place, start with a focused group of 42 high quality undervalued stocks that combine strong fundamentals with discounted market pricing.
- If capital preservation and steadier profiles matter most to you, narrow the field to 31 resilient stocks with low risk scores that score well on resilience and financial strength.
- For those hunting fresher stories that are not widely followed, widen your watchlist with 18 high quality undiscovered gems that already show solid business metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com